Understanding How Itemized Deductions Actually Work in Practice
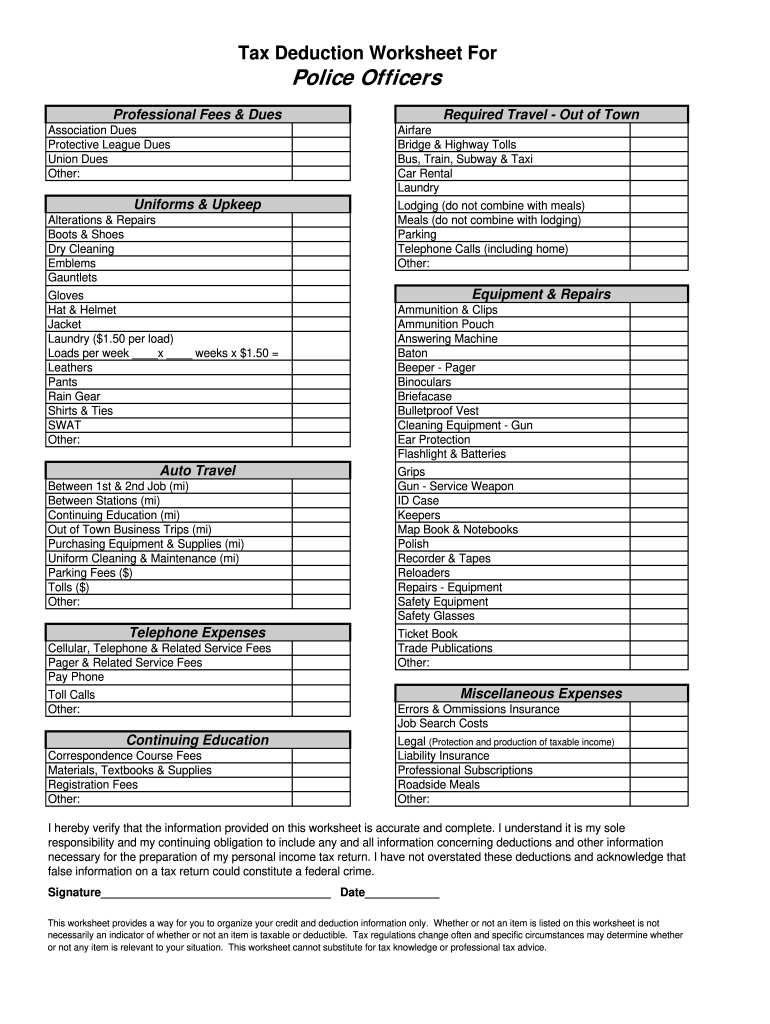
The Printable Itemized Deductions Worksheet is a tool that helps you track and organize expenses you plan to claim instead of taking the standard deduction. Most people don't realize they need to compare their total itemized deductions against the standard deduction amount before deciding which path to take. The worksheet itself is just a structured form, but the real work happens in the research phase before you ever fill it out. I've spent years watching people try to use these worksheets without understanding what actually qualifies. The most common mistake is including expenses that either don't qualify or are already covered elsewhere. For example, medical expenses only count if they exceed 7.5% of your adjusted gross income. That threshold catches a lot of people off guard.
Using the Printable Itemized Deductions Worksheet Effectively
Start by gathering all your receipts and documentation from the tax year you're working with. Medical expenses, state and local taxes, mortgage interest, and charitable contributions are the four main categories you'll be filling in. Don't mix up current-year payments with prior-year payments. I've seen people carry forward last year's property tax estimates into this year's numbers because they didn't distinguish between what was paid and what was merely owed. Here's something most beginners miss. State and local tax deductions are capped at $10,000 under current law. This cap applies to the combined total of property taxes, state income taxes, and sales taxes. It doesn't matter which combination gets you closest to that ceiling — once you hit $10,000, nothing extra counts. I had a client who owned a vacation property in a high-tax county and worked in a state with income tax. He was paying over $14,000 in combined property and income taxes and assumed he could deduct all of it. The worksheet forces you to notice the cap, but only if you add the numbers correctly before reaching the final line. Medical expenses require a different kind of attention. You need your adjusted gross income first, then calculate 7.5% of that figure. Only the amount exceeding that threshold enters the worksheet. If your AGI is $85,000, then $6,375 is your floor. Any medical spending below that number disappears entirely for deduction purposes. I made the error myself early on and wasted time categorizing expenses that would never make it onto Schedule A. The fix was simple: compute the AGI floor before entering any medical line items.
Charitable contributions often create confusion around non-cash donations. The IRS requires a qualified appraisal for items valued above $5,000. A Printable Itemized Deductions Worksheet won't flag this requirement, but tax software will if you're using it alongside the form. Without the appraisal, the deduction gets disallowed during review, and correcting that after filing costs time and potentially penalties. Keep the appraisal documentation with your tax records even if the worksheet says you deducted it. Mortgage interest deserves its own section because the rules changed significantly with the Tax Cuts and Jobs Act. Interest on mortgage debt up to $750,000 qualifies for acquisition indebtedness. Debt taken out after December 15, 2017, falls under this limit. If your mortgage was originated before that date, the older $1 million limit may still apply. Verify the origination date before entering the interest amount, and don't double-count points that were already deducted in a prior year. One practical workflow tip. Print the worksheet, but enter your numbers digitally first if you can. Mistakes happen when you're transcribing from memory or from messy receipts. I recommend entering everything into a spreadsheet with separate columns for category, amount, supporting document reference, and qualification notes. Once the spreadsheet checks out, transfer the totals to the printable form. This takes maybe twenty minutes extra upfront but saves hours of rework when errors surface later.
Get the Full Details

The limitations of a Printable Itemized Deductions Worksheet become obvious when your situation involves multiple states or foreign income. The form assumes a straightforward federal filing scenario. If you're dealing with state tax reciprocity, foreign tax credits, or rental property depreciation, the worksheet alone won't capture everything. In those cases, you need professional tax software or a CPA who understands the interaction between federal and state rules. No worksheet substitutes for that complexity. Another scenario where the worksheet falls short. Business expenses that should go on Schedule C rather than Schedule A. Some sole proprietors incorrectly route ordinary and necessary business costs through itemized deductions. These belong on the business schedule. Misclassifying them reduces your business deduction and inflates your itemized total, creating a mismatch that auditors flag quickly. Keep your documentation for at least three years from the filing date, or longer if the circumstances require it. A completed Printable Itemized Deductions Worksheet is useful only if you can back up every number when the IRS asks. Receipts, cancelled checks, acknowledgment letters from charities, and mortgage statements form the minimum folder. Organize them by category as you go, not after the year ends.
The standard deduction for 2024 is $14,600 for single filers and $29,200 for married filing jointly. Before you invest time in the worksheet, do a rough estimate of your total itemized deductions. If your educated guess falls below the standard deduction, completing the worksheet precisely probably isn't worth the effort. A quick mental math check takes thirty seconds and prevents wasted work. When the math shows itemizing makes sense, the Printable Itemized Deductions Worksheet becomes a genuinely useful organizing tool. It forces you to separate categories, sum subtotals, and produce a clean transfer to Schedule A. The form itself doesn't do the calculation for you, but having everything laid out on one page reduces the chance of missing a qualifying expense or double-counting one. That's the actual value of it.