Getting Your P&C License in Oklahoma: What Actually Works
Oklahoma requires you to pass two exams to get a Property and Casualty insurance license. One for Property, one for Casualty. That's the short version. The longer version involves choosing a testing provider, scheduling dates, studying for roughly 40 to 80 hours depending on your background, and then dealing with the fact that the exam questions are written in a way that deliberately tricks people who memorized definitions instead of understanding concepts. I've watched probably two hundred people go through this process over the years. Some breeze through. Most struggle with the same three things: timing, reading comprehension on tricky answer choices, and not realizing how much Oklahoma-specific content shows up on a supposedly national exam.
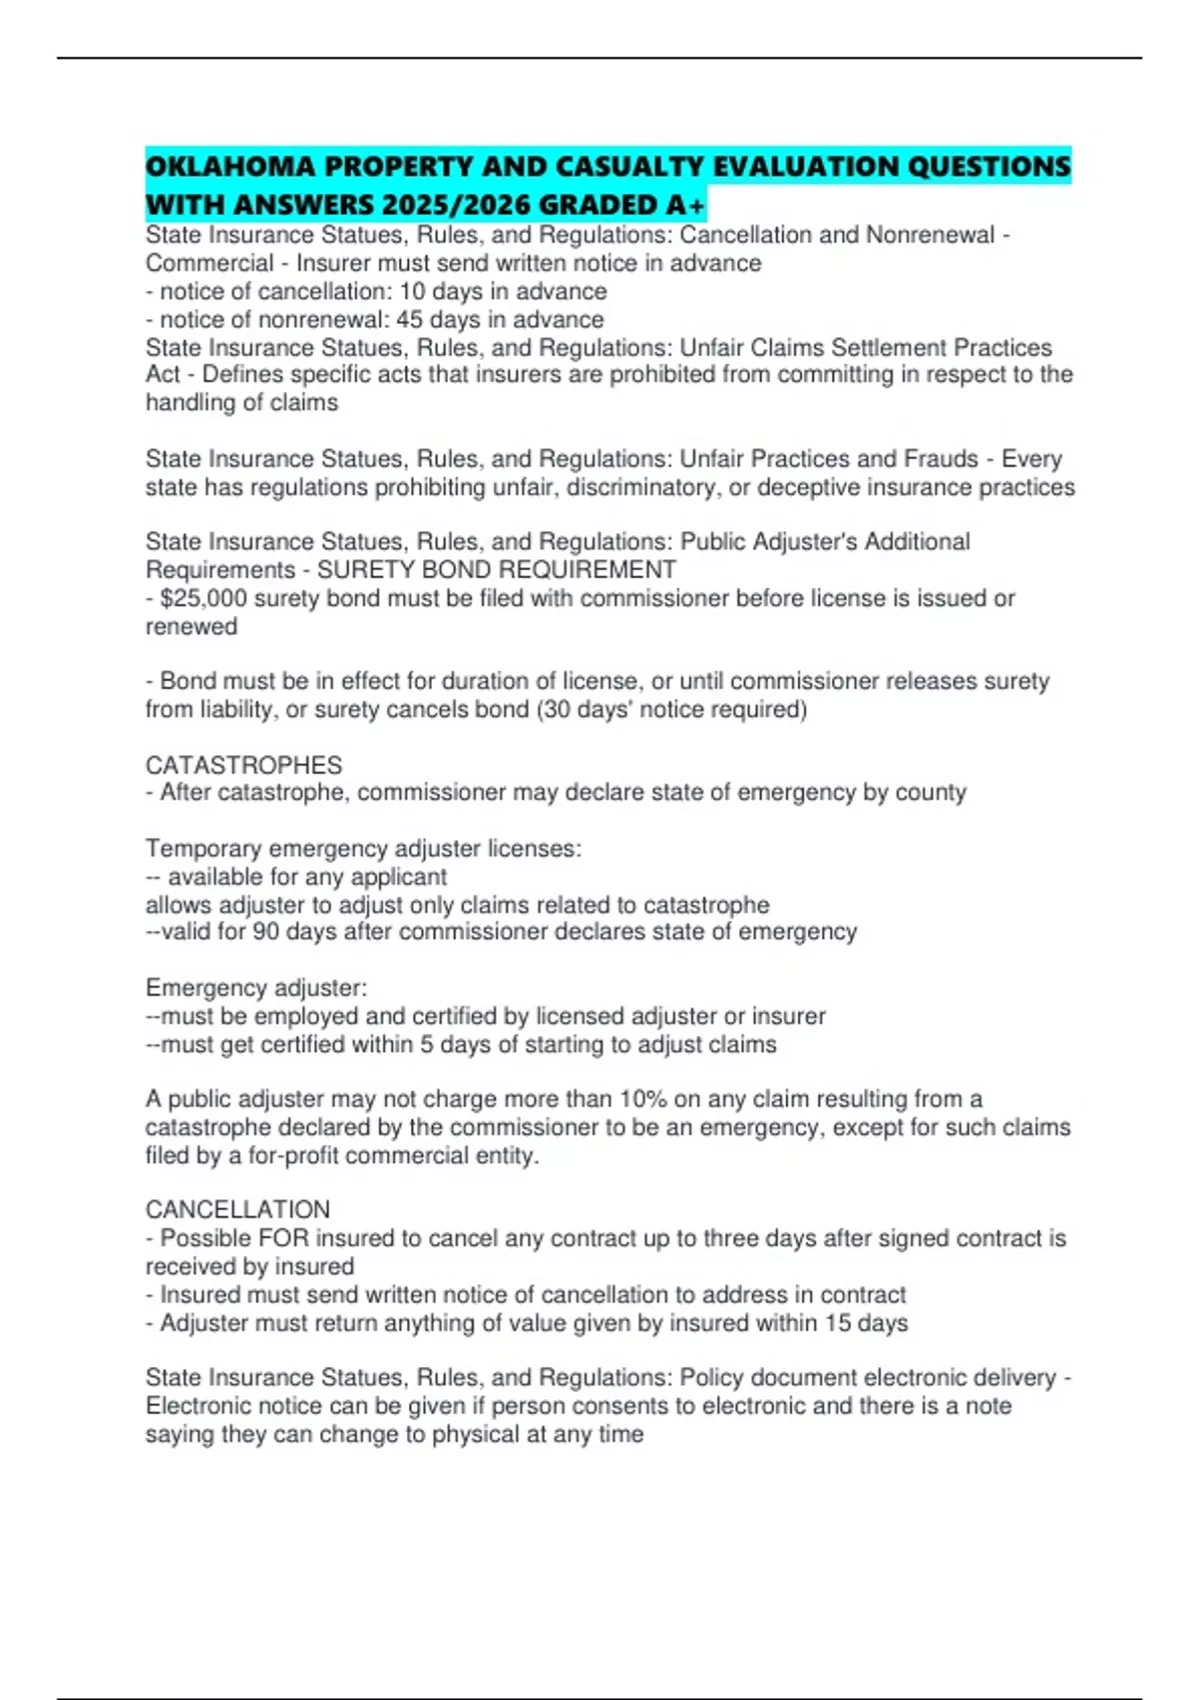
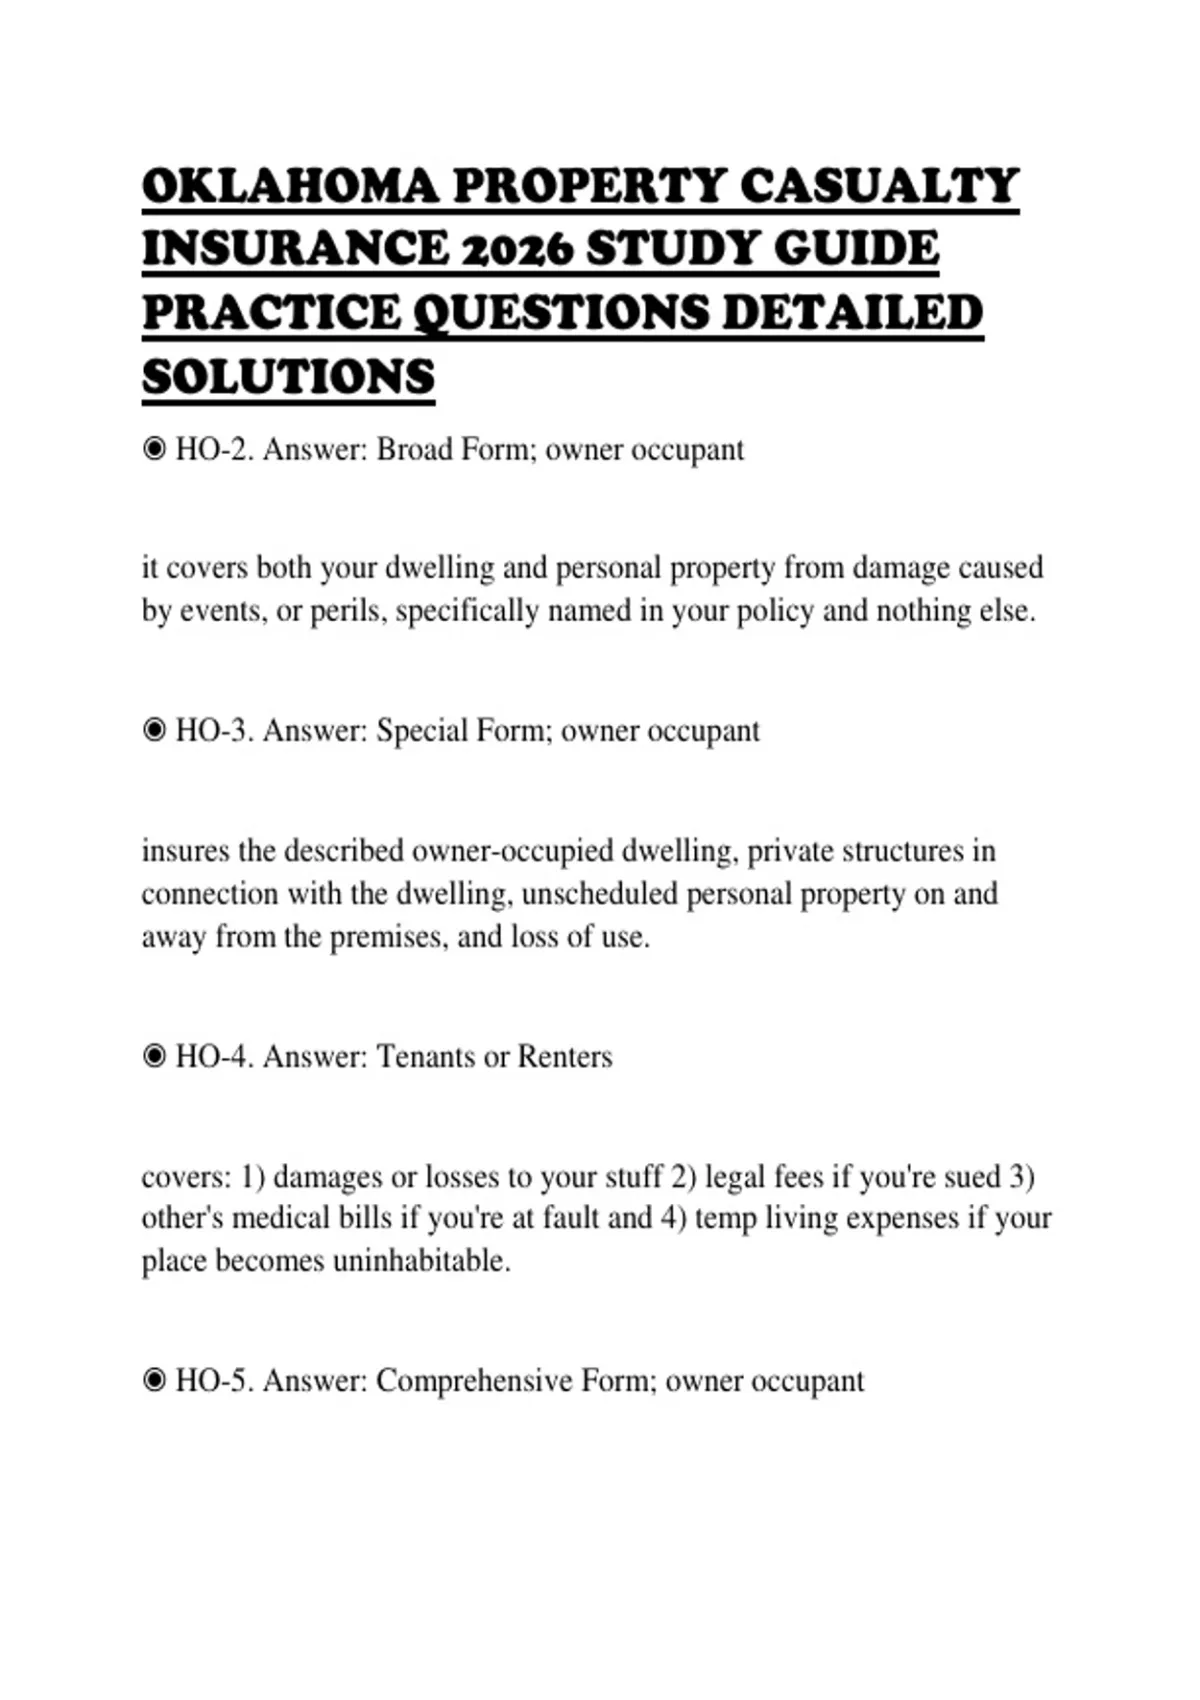
Property And Casualty Study Guide Oklahoma Resources That Aren't Waste Of Time
The most common question I see is about study materials. There are three main categories and each has a real tradeoff. Pre-built courses from major vendors. Kaplan, AnnuityEd, Midwest Insurance Training — these run between $100 and $300 and include textbook, online modules, and practice exams. They're structured, which helps people who need external deadlines. The downside is they cover the national syllabus broadly and tend to underweight state-specific content. You'll need to supplement with Oklahoma-specific rules on your own. State-specific study guides. These are narrower and usually cheaper, somewhere around $30 to $80. They focus heavily on Oklahoma statutes, the Oklahoma Insurance Department regulations, and state-level policy forms. The problem is quality is inconsistent. Some are well-written by people who actually work in the field. Others are copy-pasted from older editions and still reference repealed forms. Check the publication date and look for any mention of the Oklahoma Administrative Code titles 44 and 360, which are where the relevant regulations live.
The free government source. The Oklahoma Insurance Department publishes an official candidate handbook and pre-licensing requirements on their website. It's dry, it's not engaging, but it's accurate. I always tell people to start here before spending money on anything else, because it tells you exactly what will be on the exam and what the passing score is. For Oklahoma, the passing score on the computer-delivered exam is 60 percent on each section. That's lower than it sounds, and it matters because it changes how you should approach your study strategy. Here's the thing nobody tells you about that 60 percent threshold: the exam is adaptive in the sense that easy questions and hard questions are mixed together, but the scoring doesn't distinguish between them in a way that helps you. If you're sitting at 55 percent after the first half, you don't need to understand everything perfectly — you just need to stop getting the obviously wrong answers wrong. The questions that look like they have two correct answers usually don't. Pick the answer that is more specific to the scenario, not the one that sounds more general and "right." I ran into this exact issue last year with a client who was retaking the exam for the third time. She kept missing questions about the Oklahoma Uninsured Motorist Law. The textbook answer was technically correct but not the Oklahoma-specific answer. I had her go directly to the statute text in the Administrative Code instead of relying on secondhand summaries, and her score jumped from 52 to 71 on the next attempt. Reading primary source material for state law beats re-reading a study guide every single time when you're stuck on state-specific questions.
Get the Full Details
How The Exam Actually Works
The Oklahoma P&C exam is delivered through Pearson VUE. You'll schedule it through their website, show up with two forms of ID (one must be photo identification), and take each section — Property and Casualty — separately. Each section has roughly 100 to 120 questions and you get about two hours per section. The total testing window can stretch to three or four hours if you factor in the check-in and check-out procedures. There is no penalty for wrong answers. Ever. This changes how you should approach the exam completely. If you're sitting there leaving blanks because you're unsure, you are actively lowering your score. Guess on everything. If you can eliminate one or two choices, your odds improve from 25 percent to 33 or 50 percent. If you can't eliminate anything, you still have a 25 percent chance, which is better than zero. The questions fall into roughly five buckets, though the exam doesn't label them that way:
- Definitions and terminology — straightforward recall
- Policy provisions and exclusions — you need to know what standard ISO forms actually say
- Calculation questions — premium, deductibles, coinsurance, actual cash value vs replacement cost
- State law and regulation — Oklahoma-specific statutes and rules
- Scenario-based application — the hardest category, where you apply rules to a factual situation
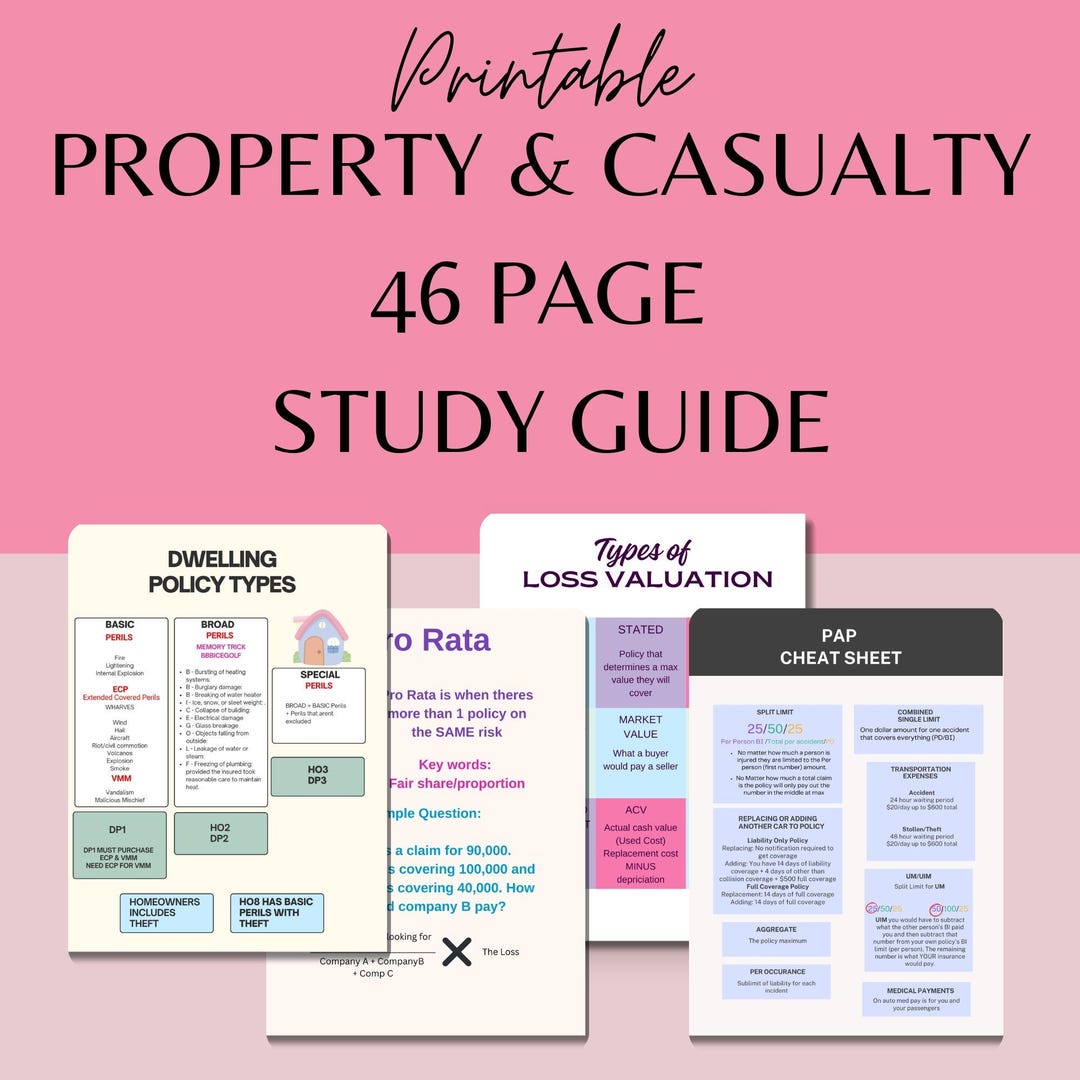
Most people underprepare for the calculation questions and overprepare for the definitions. The calculations are simpler than they look. Coinsurance penalties, for example, follow one formula and if you memorize it you'll never miss one. The definition questions are where people lose points because they know the term but pick the slightly-off answer choice. The scenario questions are where people who actually understand the material pull ahead. A good Property And Casualty Study Guide Oklahoma doesn't just list topics. It tells you which topics carry the most weight, which ones appear on almost every exam, and which ones you can skim. The exam blueprint from the testing provider breaks down the percentage distribution. In Oklahoma, Property and Casualty each make up roughly 50 percent of the content, but within each section the weightings vary. For Property, the heavy hitters are: property coverage forms (HO, BC, DP), fire and allied lines, valuation methods, and subrogation. For Casualty, it's: liability coverage, auto insurance (both mandatory and optional), workers compensation fundamentals, and professional liability. Anything outside those clusters is fair game but less likely to show up in depth.
Here's a practical warning: some study guides include outdated Oklahoma auto insurance requirements. The state has updated its no-fault and uninsured motorist rules in recent years. If your guide references older statutes without noting the change, it's not reliable. Cross-check anything about auto liability limits or compulsory coverage against the current Oklahoma Insurance Department publications. Another counter-intuitive point: practice exams are useful but not in the way most people use them. Taking ten practice exams and just checking your score tells you almost nothing. The useful approach is to take one practice exam, get every question wrong, and then spend two hours reading the explanation for why each wrong answer is wrong and each right answer is right. That single cycle is worth more than five cycles of just checking scores. You're building pattern recognition for how the exam writers phrase traps.
A Realistic Timeline
If you're studying full-time, eight to ten weeks is reasonable. If you're working a job and studying part-time, plan for twelve to sixteen weeks. Anything less than eight weeks total usually means you're either already in the industry or you're gambling. I've seen people pass in five weeks, but they all had prior insurance experience or a background in finance or law where the terminology wasn't foreign. Within that timeline, the sequence that works is: read the material once slowly, take a baseline practice exam cold, identify your weak areas, focus your second pass on those areas, then shift to timed practice exams in the final two weeks. The mistake most people make is jumping straight to practice exams without doing the reading first. You'll test your misunderstandings repeatedly and reinforce them. That's how you build confidence in the wrong answers.
The Limits Of Any Study Guide
No study guide covers everything. The exam pulls from a large question bank and adds new questions periodically based on regulatory changes. A guide that was published more than three years ago may already be missing recent updates to Oklahoma law. If you find yourself consistently missing questions on a topic that your guide says is minor, that's a signal the guide is out of date and you should look at the current statute directly. Also, passing the exam is not the same as knowing how to do the job. The licensing exam tests a snapshot of foundational knowledge. It does not test claims handling workflows, policy wording interpretation beyond the standard forms, or the practical nuances of Oklahoma insurance disputes. If your goal is just to get licensed, the exam-focused approach works fine. If your goal is to actually write policies or adjust claims in Oklahoma, you'll need on-the-job training that no guide can provide. The bottom line is that the exam is passable with focused preparation. You don't need to love insurance. You don't need to read every page of the Oklahoma Administrative Code. You do need to understand how the questions are constructed, know the key Oklahoma-specific rules cold, and practice enough that you stop second-guessing yourself on answer choices that look correct but aren't.