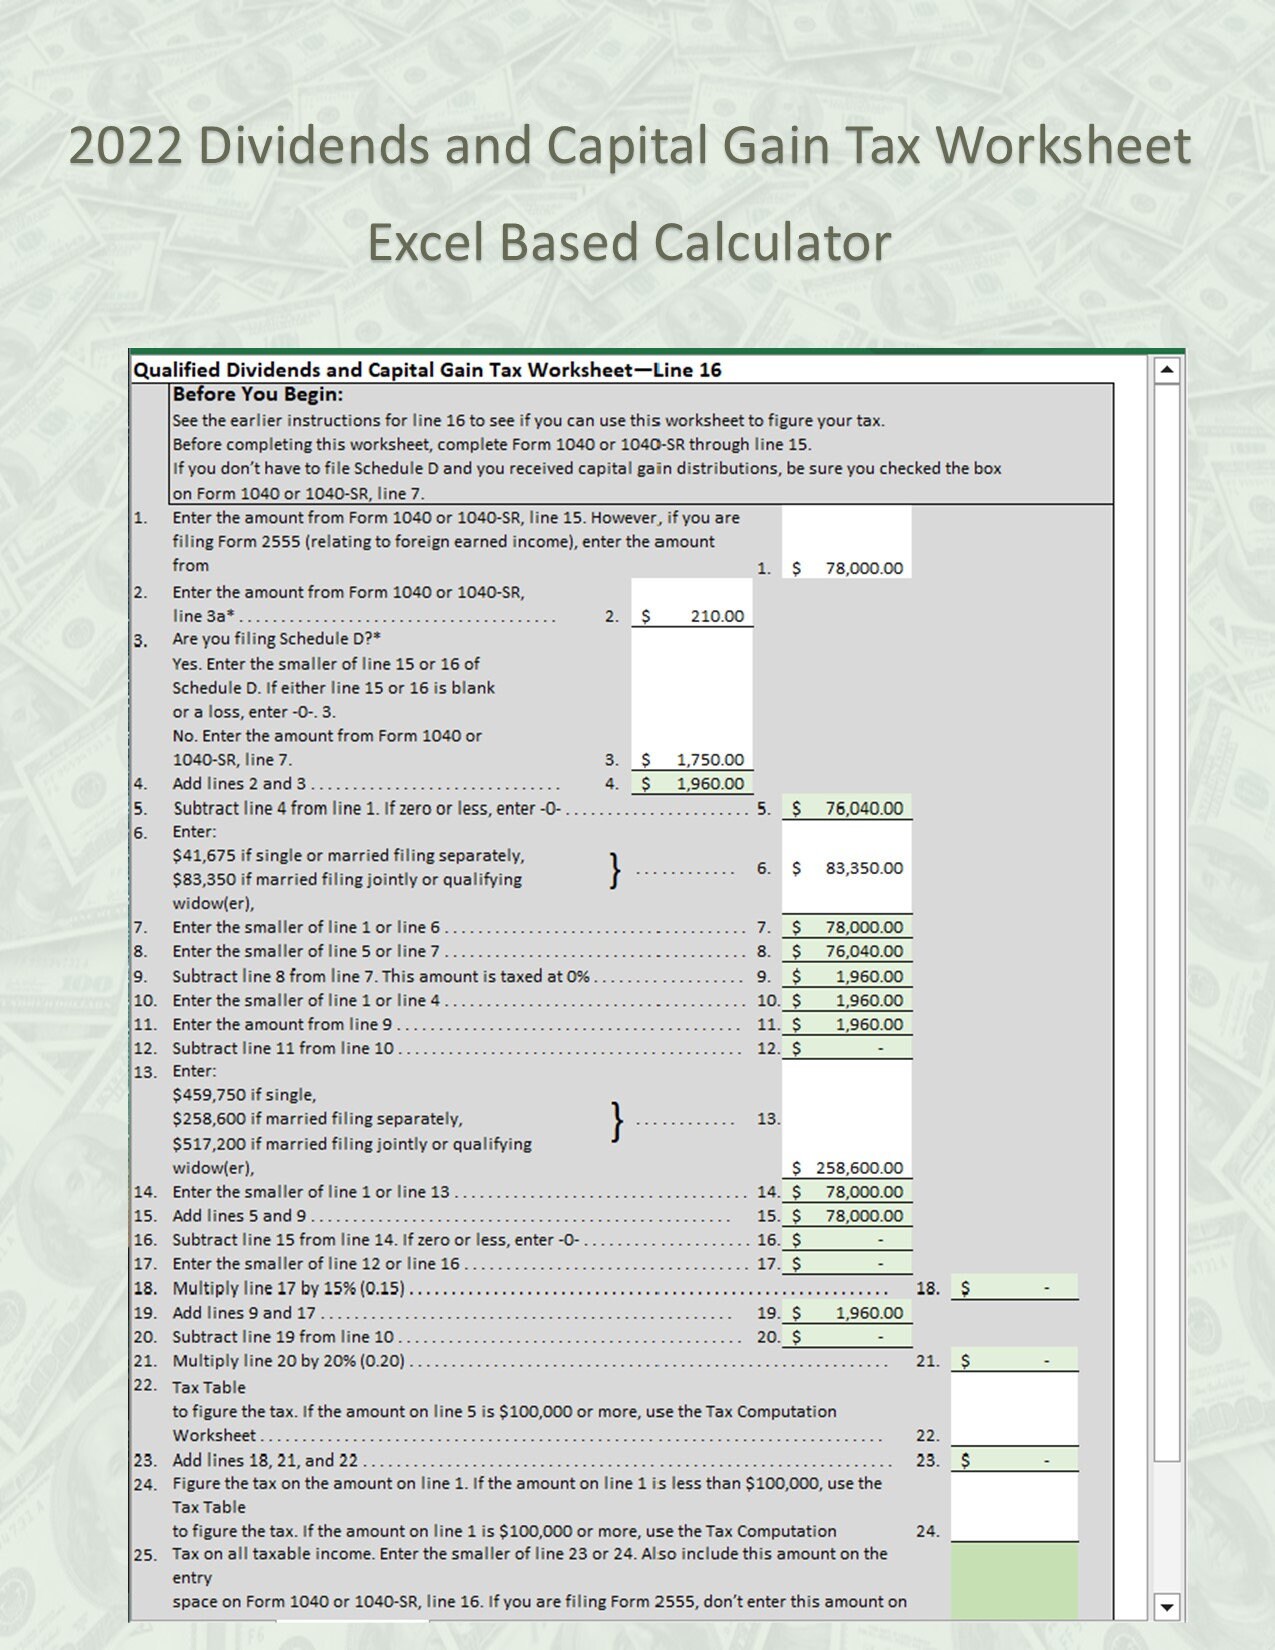
How The Qualified Dividends And Capital Gain Tax Worksheet Calculator Actually Works
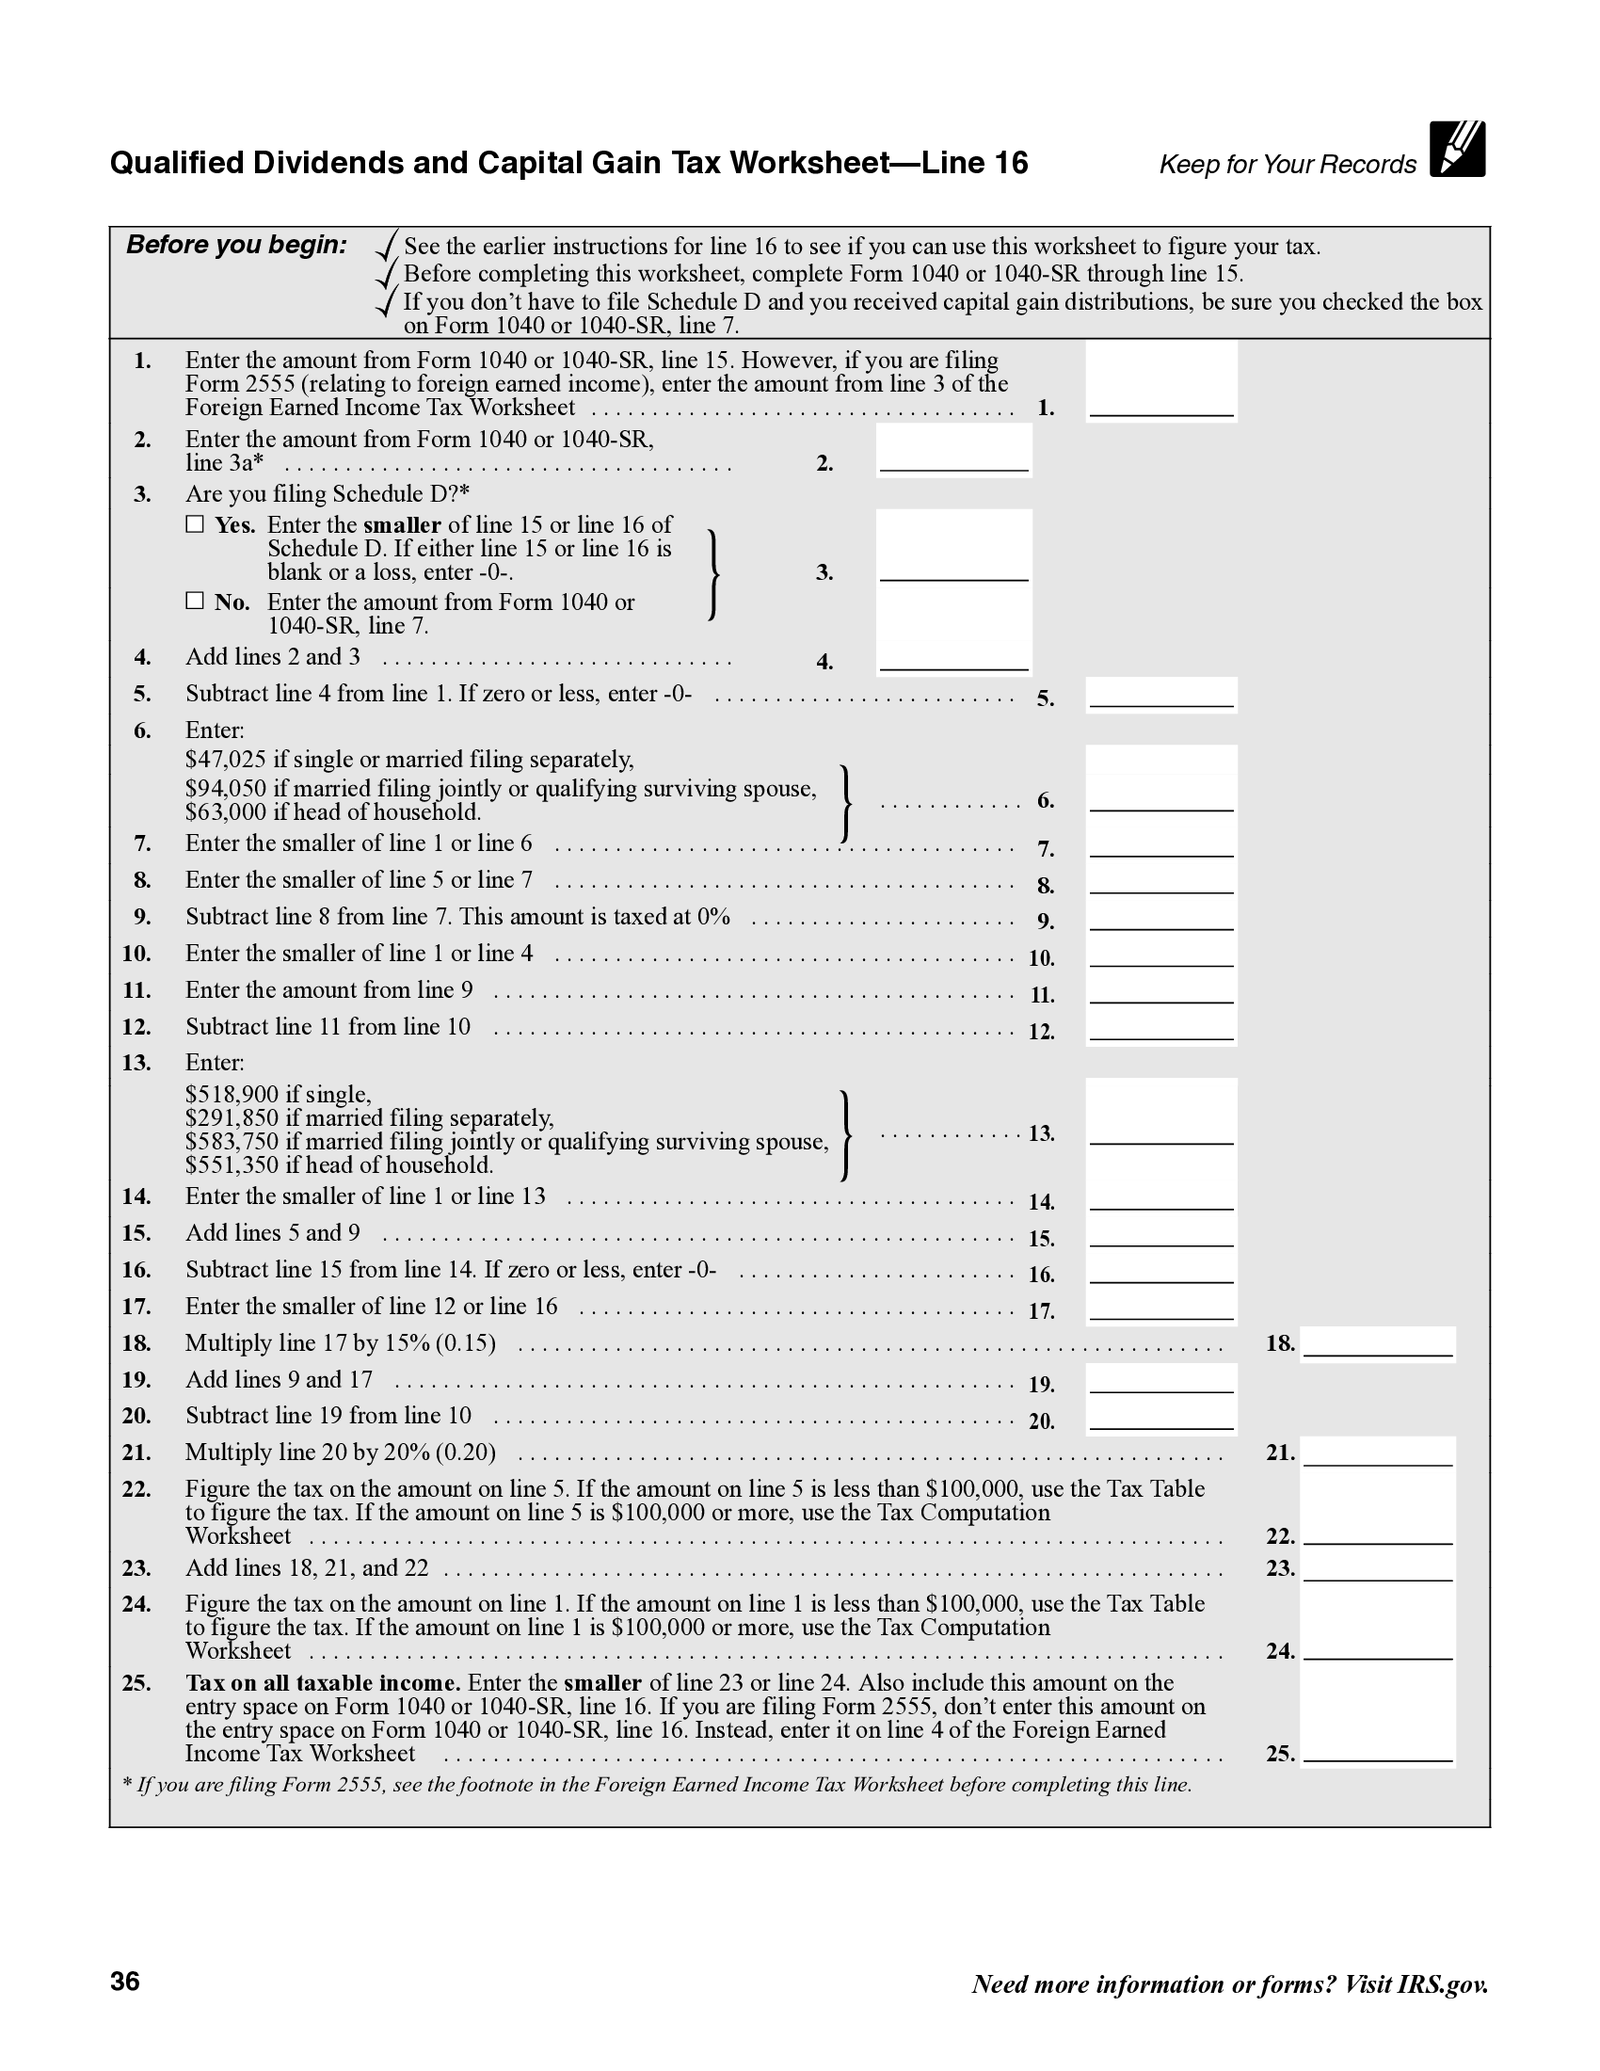
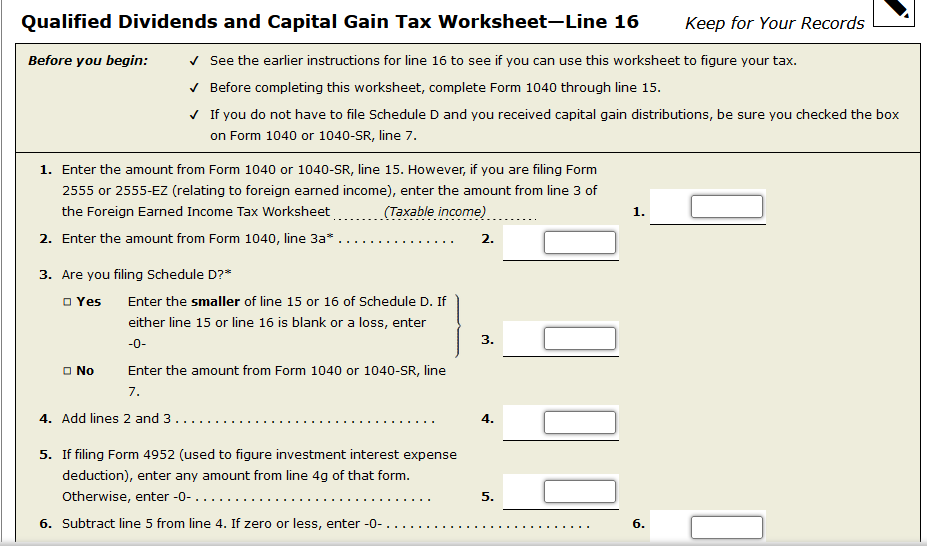
The worksheet sits on Schedule D of your tax return. It exists because qualified dividends and capital gains get taxed at different rates than ordinary income. The 2024 top ordinary rate is 37%. The top qualified dividend and long-term capital gain rate is 20%. There's also the 0% and 15% brackets sitting underneath. The worksheet figures out which bracket you land in by stacking your taxable income against the threshold numbers that change every year. You need three pieces of information before opening anything: your total taxable income from Form 1040 line 15, the amount of qualified dividends from Schedule B or your broker statements, and your net long-term capital gain or loss from Schedule D. If you have a Section 1231 gain, that goes into the mix too. The worksheet is line-by-line and deliberately boring. That's by design. I've filled this out for maybe forty tax returns across different income levels. The process takes about twelve minutes if you already have your documents organized. It drags to forty-five minutes when you're pulling K-1s from partnerships or untangling wash sale adjustments from a brokerage that doesn't report them cleanly. Most people skip the details because they use software. Software usually handles this correctly, but occasionally it makes a wrong assumption and you end up paying too much or triggering an audit trail that looks weird if someone reviews it.
The Mechanics Behind The Calculation
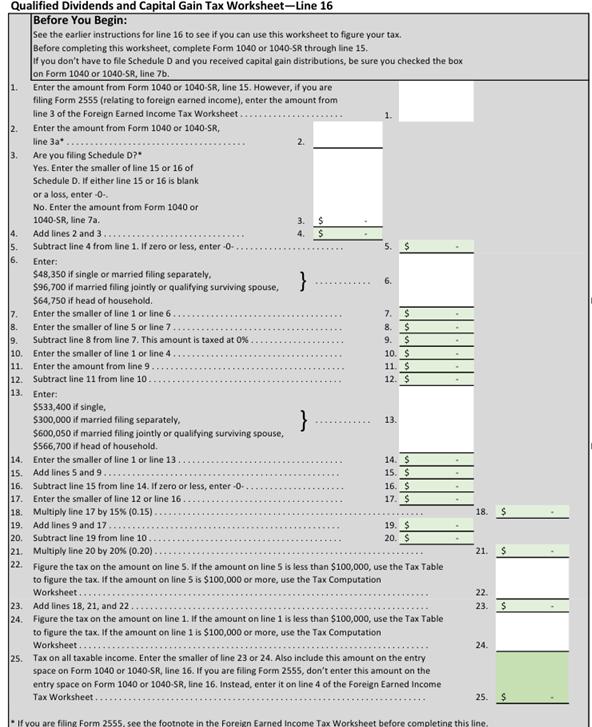
Here's how the worksheet actually functions. You take your taxable income and subtract your standard deduction or itemized deductions if they're already embedded in the numbers. Then you layer the preferential rate income on top of your ordinary income. The preferential rate income includes qualified dividends, net capital gain, collectibles gain, and certain Section 1231 gains. The worksheet compares that total against the bracket thresholds for your filing status. For single filers in 2024, the 0% bracket runs up to $47,025 of taxable income. The 15% bracket goes from $47,025 to $518,900. The 20% bracket kicks in above that. Married filing jointly has different numbers: $94,050, $583,750, and above. The tricky part is that the thresholds shift when you're subject to the net investment income tax or the additional Medicare tax. Those start at different income levels depending on filing status. The worksheet has separate sections for those scenarios. If you ignore them, you'll miscalculate your tax by a few hundred dollars at minimum. I ran into a real problem last April. A client had a significant Section 1231 gain from selling rental property, qualified dividends from a mutual fund, and also unrecaptured Section 1250 gain. The unrecaptured portion gets taxed at a maximum 25% rate, which sits above the 20% capital gains rate but below the ordinary income rate. The software I was using incorrectly lumped the unrecaptured gain into the 20% bucket. The Qualified Dividends And Capital Gain Tax Worksheet Calculator shows this separately on lines that most people skip. I caught it by going back to the IRS instructions line by line, identifying the error, and manually adjusting the Schedule D entry. The client owed an additional $1,840. Not catastrophic, but annoying to fix after filing season.
Common Mistakes People Make
The biggest error I see is treating all dividends as qualified. They're not. Some dividends from foreign corporations don't meet the holding period requirements. If you sold the shares less than sixty days during the one hundred twenty-day period around the ex-dividend date, those dividends reclassify as ordinary. Your broker should flag this, but they don't always do it clearly. I've seen people miss it on amounts over ten thousand dollars. Another mistake is ignoring the interaction between the capital loss carryover and the worksheet. If you have a capital loss carryforward from a prior year, it reduces your net capital gain before the worksheet even starts. Some calculators skip this step and apply the preferential rates to a gross number that's too high. The result is an understated tax liability. People also confuse the ordinary dividend portion of their income with the qualified portion. Schedule B line 5 asks specifically for qualified dividends. If you put the total dividend amount there, you'll overclaim the preferential rate treatment. The difference shows up on your return as a discrepancy that the IRS matching system flags quickly.
Get the Full Details
What This Tool Cannot Handle
The worksheet and any calculator built on it assume your income sources are straightforward. They break down when you're dealing with complex partnership allocations, S corporation distributions that blend return of capital with ordinary income, or foreign tax credit interactions that change your effective tax rate. If you have Amortizable Bond Premium that affects your cost basis, the calculator won't adjust your capital gain correctly without manual input. These edge cases require either a spreadsheet built for the specific situation or professional preparation. No online tool covers every scenario. There's also a limitation with state taxes. This worksheet is purely federal. Many states don't conform to the federal qualified dividend treatment. Some tax them as ordinary income. Some don't tax capital gains at all. If you live in California, for example, you'll recalculate this entire thing on your state return with different numbers. The federal worksheet gives you zero help with that. The other bottleneck is timing. If you realize you have a capital loss harvesting opportunity in December, you need to act before the market closes. The worksheet can tell you whether realizing a loss pushes you into a lower bracket, but it can't execute the trade or predict whether the wash sale rule will disallow the loss based on your specific security purchases. That requires manual tracking across accounts.
A Practical Walkthrough
Take a hypothetical case. Single filer, taxable income of $85,000, qualified dividends of $12,000, and net long-term capital gain of $8,000. The total preferential rate income is $20,000. The 0% bracket threshold for a single filer in 2024 is $47,025. Since $85,000 exceeds that, none of the preferential income falls in the 0% bucket. The excess over $47,025 is $37,975. The 15% bracket extends up to $518,900, so the entire $20,000 sits in the 15% bracket. The tax on that preferential income is $3,000. The remaining $65,000 of ordinary income gets taxed at the ordinary brackets. This is the basic calculation. Add in the net investment income tax if modified adjusted gross income exceeds $200,000 for single filers, and the picture changes. The worksheet has a separate computation for that additional 3.8% tax. I keep a personal spreadsheet that replicates the worksheet logic with a few extra columns for edge cases. It tracks the holding period issues, wash sale adjustments, and state-level differences. It saves me roughly twenty minutes per return and catches errors that standard software misses. The initial build took me about three hours, but it pays for itself after the first couple of tax seasons. If you're preparing your own return and want to use the Qualified Dividends And Capital Gain Tax Calculator, the IRS publishes the official worksheet in the Schedule D instructions. Download the PDF, work through it with your numbers before opening any software, and then compare your result to whatever the software produces. If they differ by more than a few dollars, something is wrong and you should investigate before filing. The difference between filing correctly and filing with a minor error is usually the difference between a clean return and a thirty-day delay while the IRS correspondence queue sorts it out.