What Rate Of Change Actually Means
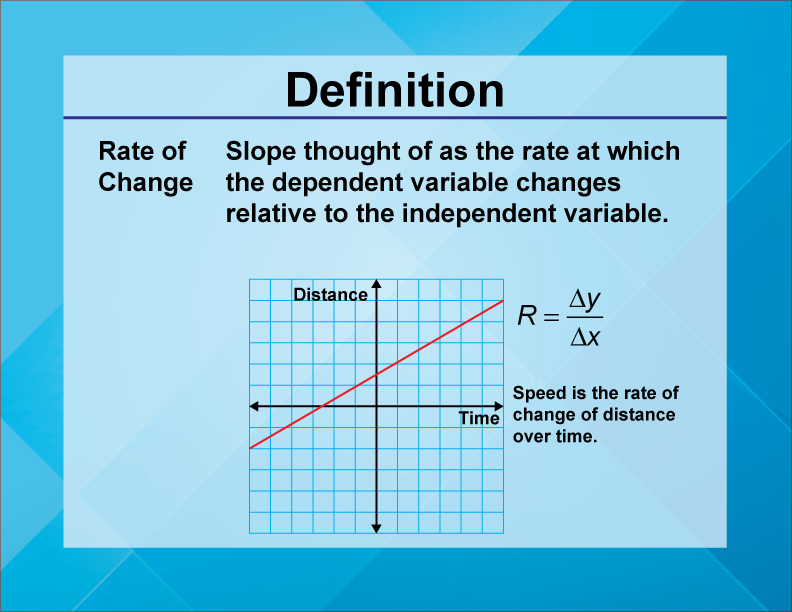
The rate of change definition sounds straightforward until you actually try to apply it, because the concept exists in multiple contexts and each one works slightly differently. In calculus, it's the derivative – how much one variable shifts as another variable shifts. In trading, it's an oscillator that measures momentum by comparing today's price to a price N periods ago. In physics, it's velocity or acceleration depending on whether you're talking about position or speed. People mix these up constantly, and that's where most mistakes happen. I've seen analysts use a financial ROC calculation on time-series data that wasn't evenly spaced, then wonder why their model produced garbage results. The core formula assumes uniform intervals. When that assumption breaks, everything downstream breaks with it.
Rate Of Change Definition
The Basic Math Behind It
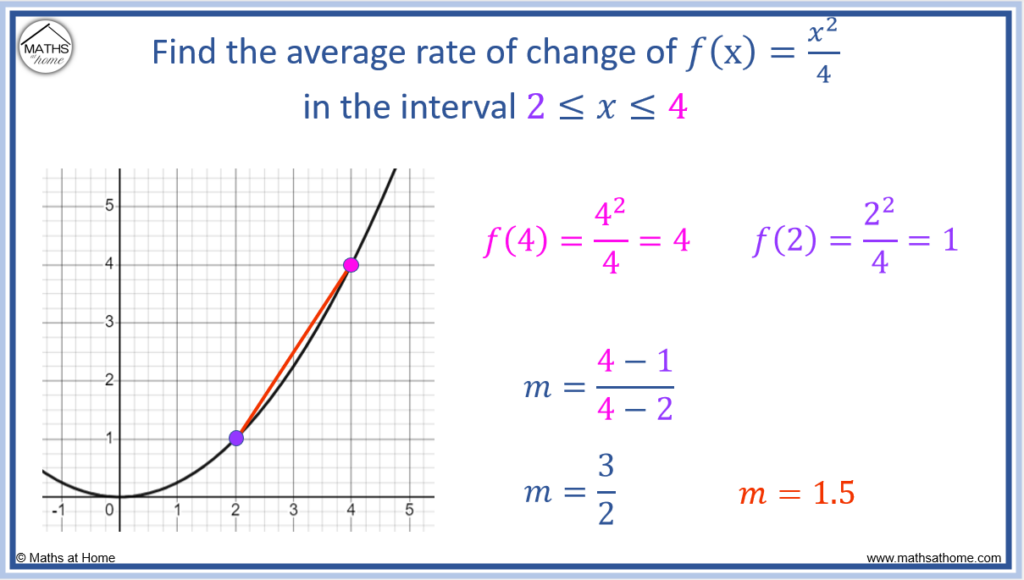
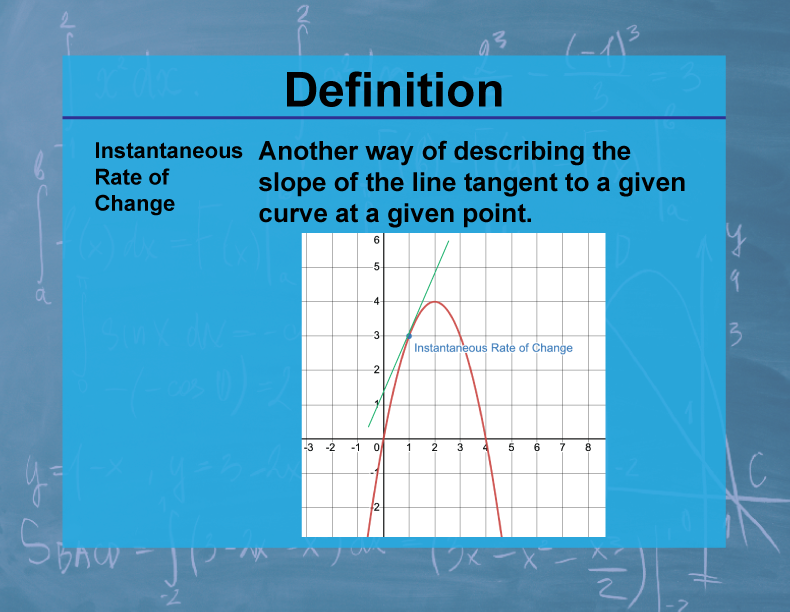
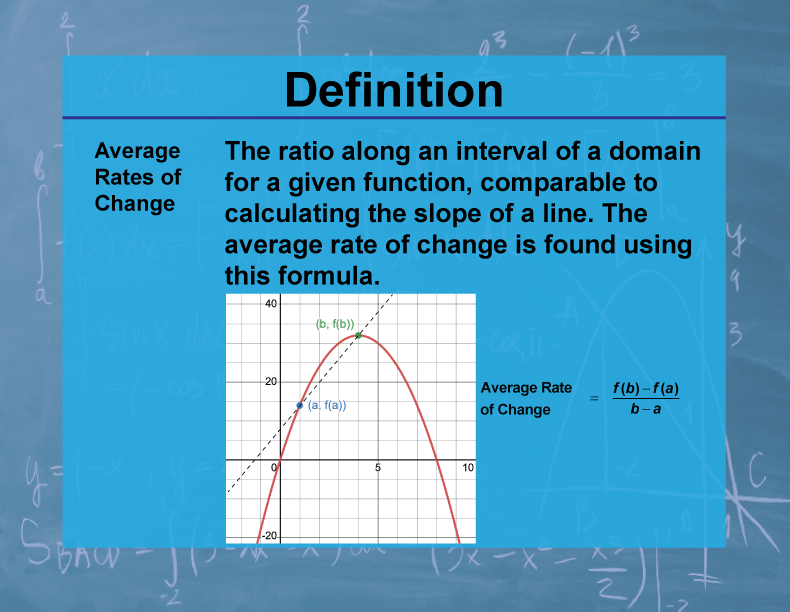
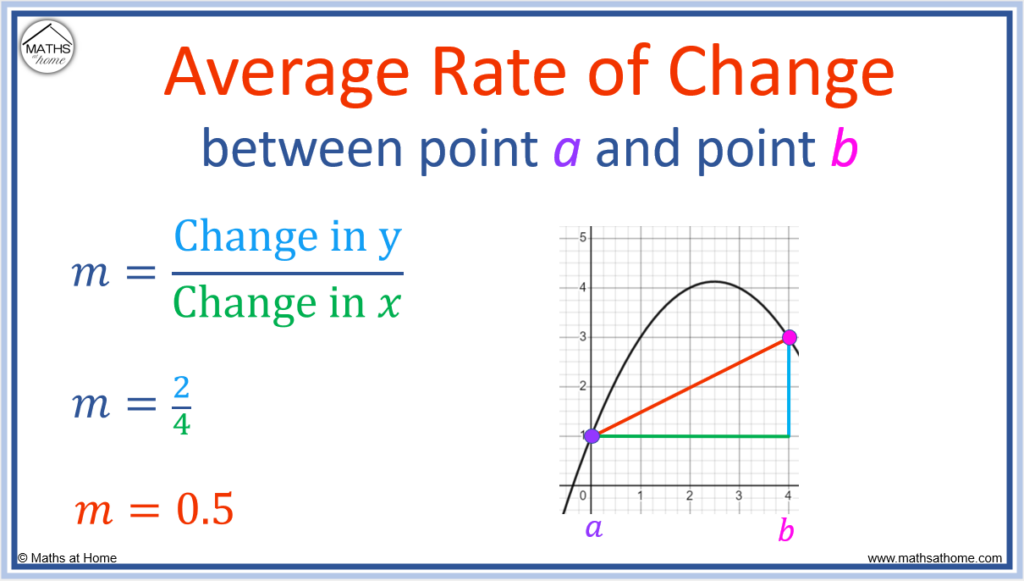
For a function f(x), the average rate of change between two points a and b is calculated as [f(b) - f(a)] / (b - a). That's literally just the slope of the secant line connecting those two points. The instantaneous rate of change, which is what most people mean when they talk about derivatives, is the limit of that expression as b approaches a. In notation, that's f'(a) or df/dx evaluated at the point in question. The difference quotient approach works fine for simple polynomial functions. Once you hit trigonometric or exponential expressions, you start needing chain rules, product rules, and quotient rules. The underlying concept doesn't change, but the mechanics get messier fast.
How It Works in Practice
I work with sensor data from industrial equipment – vibration readings, temperature gauges, pressure sensors. The rate of change tells me whether a bearing is degrading gradually or if something is about to fail catastrophically. A steady drift in temperature over weeks is one thing. A spike of four degrees per hour is another thing entirely, and I'd rather deal with the latter before it becomes a shutdown event. Here's the thing most tutorials skip: discrete data and continuous functions behave very differently. Real-world measurements come at intervals, not as smooth curves. So when I compute rate of change from actual sensor samples, I'm always working with finite differences, not true derivatives. The forward difference formula [f(x+h) - f(x)] / h is the simplest approach, but it introduces truncation error that grows with larger step sizes. The central difference formula [f(x+h) - f(x-h)] / 2h is more accurate for the same step size, roughly doubling precision without extra computational cost. I ran into a specific problem last year where my central difference approach started producing negative rates of change on a physical quantity that literally couldn't go negative. The sensor was measuring material thickness, and the reading should only decrease or stay flat. What was happening was measurement noise – tiny random fluctuations that the differentiation process was amplifying. Differentiation is fundamentally a high-pass filter, which means it amplifies high-frequency noise along with the actual signal. I ended up applying a Savitzky-Golay filter before computing the derivative, which smooths the data while preserving the shape of the signal. That brought the false negatives down to near zero and made the degradation trends readable again.
Get the Full Details

Common Pitfalls That Wreck Your Results
The most destructive mistake I see is applying a single rate-of-change metric across heterogeneous data. If your dataset contains steps, jumps, or missing values, the raw calculation will produce artifacts that look like real signal. A single missing data point in the middle of a time series creates a gap that the difference formula interprets as an enormous rate of change across that interval. You either need to interpolate the gap or explicitly mask those segments. Another issue is scale dependency. The numerical value of a rate of change depends entirely on your units. A stock moving from $50 to $51 has a rate of change of $1 per day. A stock moving from $200 to $201 also moves $1 per day. But percentage-wise, the first moved 2% and the second only 0.5%. In finance, people typically normalize by dividing the absolute change by the previous period's value to get a percentage rate of change. This makes it comparable across different price levels, which matters when you're running models on multiple assets simultaneously. In calculus courses, students routinely forget the chain rule when dealing with composite functions. If f(x) = sin(x^2), the rate of change isn't cos(x^2) – it's 2x * cos(x^2). The inner function's own rate of change multiplies into the outer function's derivative. This isn't a minor detail. It's the difference between a correct answer and a completely wrong one on any exam or real application.
When Rate Of Change Completely Fails
Differentiation requires continuity. If your function has a jump discontinuity, the rate of change at that point is undefined. I've encountered this in trading data where overnight gaps create effective discontinuities between consecutive closing prices. Computing ROC across those gaps produces meaningless numbers. The workaround is to only compute the metric within continuous segments and skip across the gap boundaries. Another hard failure mode is when the denominator approaches zero. In the formula [f(b) - f(a)] / (b - a), if b and a are extremely close together, floating-point precision limits kick in and the result becomes numerically unstable. This is why symbolic computation tools exist – they handle the algebra exactly instead of relying on numeric approximations that can collapse under edge cases. For highly oscillatory functions, the rate of change itself oscillates wildly. Take sin(1/x) near x = 0. The function oscillates faster and faster as you approach the origin, and the derivative blows up. No amount of smoothing fixes this – it's a genuine mathematical property, not a data quality issue. In those cases, you report that the limit doesn't exist rather than forcing a number out of it.
A Quick Calculation Example
Let's say you're tracking the depth of a chemical reaction over time and you have these measurements: at t = 2 seconds, depth = 4.1 cm. At t = 2.01 seconds, depth = 4.18 cm. The average rate of change over that interval is (4.18 - 4.1) / (2.01 - 2) = 0.08 / 0.01 = 8 cm/s. That's your finite difference approximation. Make the interval smaller and your estimate gets closer to the true instantaneous rate. With t = 2.001 and depth = 4.108, you'd get (4.108 - 4.1) / 0.001 = 8 cm/s again, which suggests the function is nearly linear in that neighborhood and the approximation is already quite good. The practical takeaway is that rate of change is a tool, not an answer. It tells you direction and speed of change, but nothing about absolute values, future behavior, or whether the change is sustainable. Pair it with other metrics and always validate against the domain constraints of your specific problem.