Why Most People Mess Up Rate Of Interest Comparison
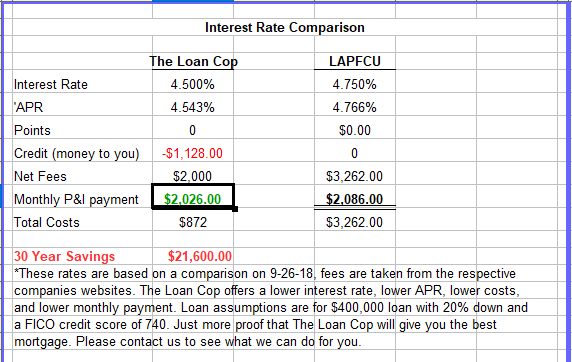
Here's what happens when you try to compare interest rates across different financial products: most people just look at the nominal rate and call it a day. The problem is that two loans with the same stated rate can cost wildly different amounts depending on compounding frequency, fees, and the payment structure. I've sat through meetings where a team convinced themselves one refinance deal was saving 2% annually. When we actually crunched the numbers, the effective rate difference was 0.3% because the "better" deal had heavy origination fees baked in. The core of Rate Of Interest Comparison isn't about which number is lower on the page. It's about translating everything into a single comparable metric so you can actually see what you're paying.
The APR Method
Annual Percentage Rate is the standard tool for this. It takes the nominal rate and folds in certain mandatory fees, giving you an effective annual cost number. In the US, lenders are required to disclose APR by law. In the EU, it's the same under the Consumer Credit Directive. The formula itself is straightforward enough that you don't need a special calculator for basic cases, but the real issue is knowing what gets included and what doesn't. APR includes things like broker fees, certain closing costs, and mandatory insurance if it's a condition of the loan. It does not include optional products like credit protection plans or voluntary early repayment insurance. That's where the first gap opens up. A lender can advertise a low APR while steering you toward add-on products that raise your actual cost significantly.
How to Actually Do the Comparison
Step one is gathering the right documents. You need the loan estimate or equivalent disclosure from each product you're evaluating. Don't rely on the marketing brochure or the website banner rate. Pull the official disclosure, the one with the fine print. In practice, I've seen people get tripped up by variable rate products where the introductory rate is locked for six months and then resets higher. The APR calculation handles this, but only if you give it the correct projected rate for the post-intro period. If you input the teaser rate as the permanent rate, your comparison is garbage. Step two is making sure the comparison period aligns. If one loan is a 15-year mortgage and the other is a 30-year mortgage, comparing their APRs directly is misleading because the amortization profile is different. Use the effective annual rate method for short-term products and stick with APR for longer-term consumer loans where the framework was designed. For investment products like bonds, you need yield to maturity instead, which is a completely different calculation. Step three is accounting for the timing of cash flows. This is where most DIY comparisons fall apart. A loan with monthly payments and a loan with biweekly payments at the same nominal rate will have different effective costs because of the accelerated principal reduction. I ran into this exact problem last year when a client wanted to compare a standard mortgage against a biweekly payment plan. The stated rates were identical at 5.75%. But the biweekly plan effectively made 13 monthly payments per year instead of 12. The APR didn't reflect that difference because APR assumes the payment schedule disclosed on the form, and the biweekly plan was marketed separately as a service, not as the loan product itself. What I did was recalculate the total interest paid over the full term using both schedules. The biweekly option saved about $3,400 in interest over 30 years, which is roughly equivalent to a rate reduction of 0.18%. Not nothing, but nowhere near the dramatic savings they were advertising.
Get the Full Details
The Internal Rate of Return Approach
For more complex comparisons, especially across different loan types or when fees are structured unusually, IRR gives you a cleaner answer. You lay out all cash flows—the money you receive, all payments you make, every fee you pay—and solve for the discount rate that makes the net present value equal zero. This handles variable rates, irregular payment schedules, and embedded fees that APR frameworks might exclude. The downside is that IRR requires more data upfront and a calculator or spreadsheet that can handle the iteration. It's not something you do on a napkin. But for business decisions or large personal loans, it's the only method that won't lie to you.
Common Pitfalls
One thing nobody warns you about is the prepayment penalty trap. Two loans might have nearly identical APRs, but one has a five-year prepayment penalty while the other doesn't. If you're planning to sell or refinance within that window, the penalty could easily erase any rate advantage. Always check the prepayment terms before declaring a winner on Rate Of Interest Comparison. Another gotcha is the fee capitalization issue. Some lenders roll closing costs into the loan balance instead of collecting them upfront. This increases the principal you're paying interest on, which raises your effective cost. APR should catch this, but only if the fees are classified as finance charges under the relevant regulation. In some jurisdictions, certain administrative fees slip through the cracks and don't get included in the APR figure. Then there's the inflation illusion. A lower nominal rate sounds better, but if one loan has a rate tied to a volatile index and the other has a fixed rate, the comparison becomes a guess about future rates. I once advised a small business owner who chose a variable-rate loan because it was 1.5% lower than the fixed alternative. At the time, the math was solid. Six months later, the index rate jumped and the variable loan cost more than the fixed one. The comparison was valid on paper but useless in practice because it didn't account for rate uncertainty.
When the Framework Doesn't Apply
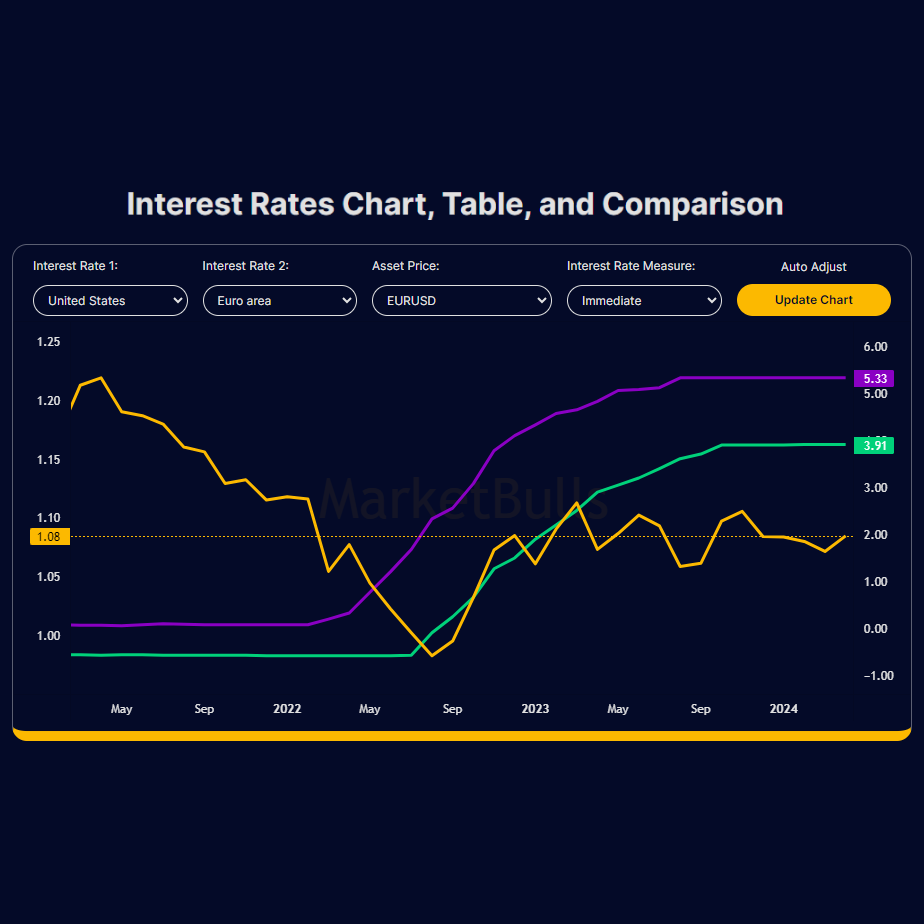
Rate Of Interest Comparison tools break down in a few scenarios. Private lending between individuals, for example, often involves non-standard terms that no disclosure form captures. Peer-to-peer loans with deferred payment structures. Revolving credit lines where you only draw part of the available amount. In these cases, the standardized metrics don't exist or don't mean much. You're better off building a cash flow model that reflects your actual usage pattern and comparing total cost rather than relying on published rates. Another area where comparison fails is across currencies. A loan in euros at 3% and a loan in dollars at 5% aren't directly comparable without factoring in expected exchange rate movement. The interest rate differential might be entirely offset by currency depreciation. This isn't a Rate Of Interest Comparison problem, strictly speaking, but it's the kind of thing that catches people off guard. The bottom line is that the method matters more than the numbers. Pick the right tool for the product, feed it complete data, and verify the output against a manual sanity check. Two minutes of recalculating by hand will catch most errors that automated comparison tools miss.