How to Actually Read a Pay Stub Without Losing Your Mind
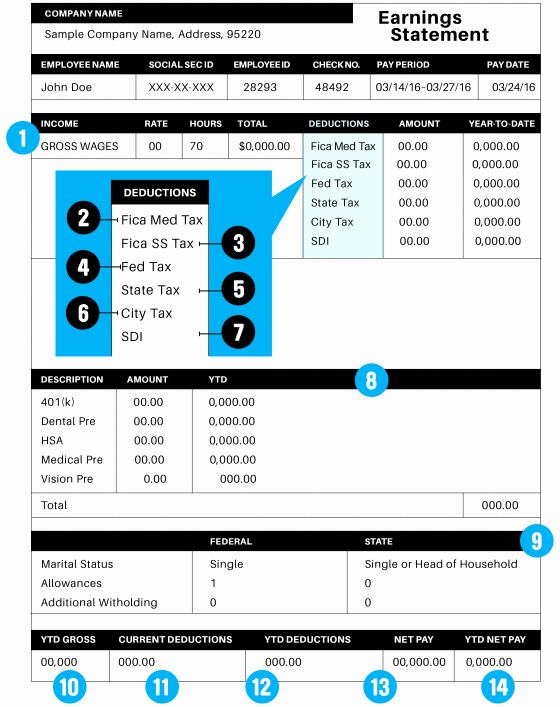
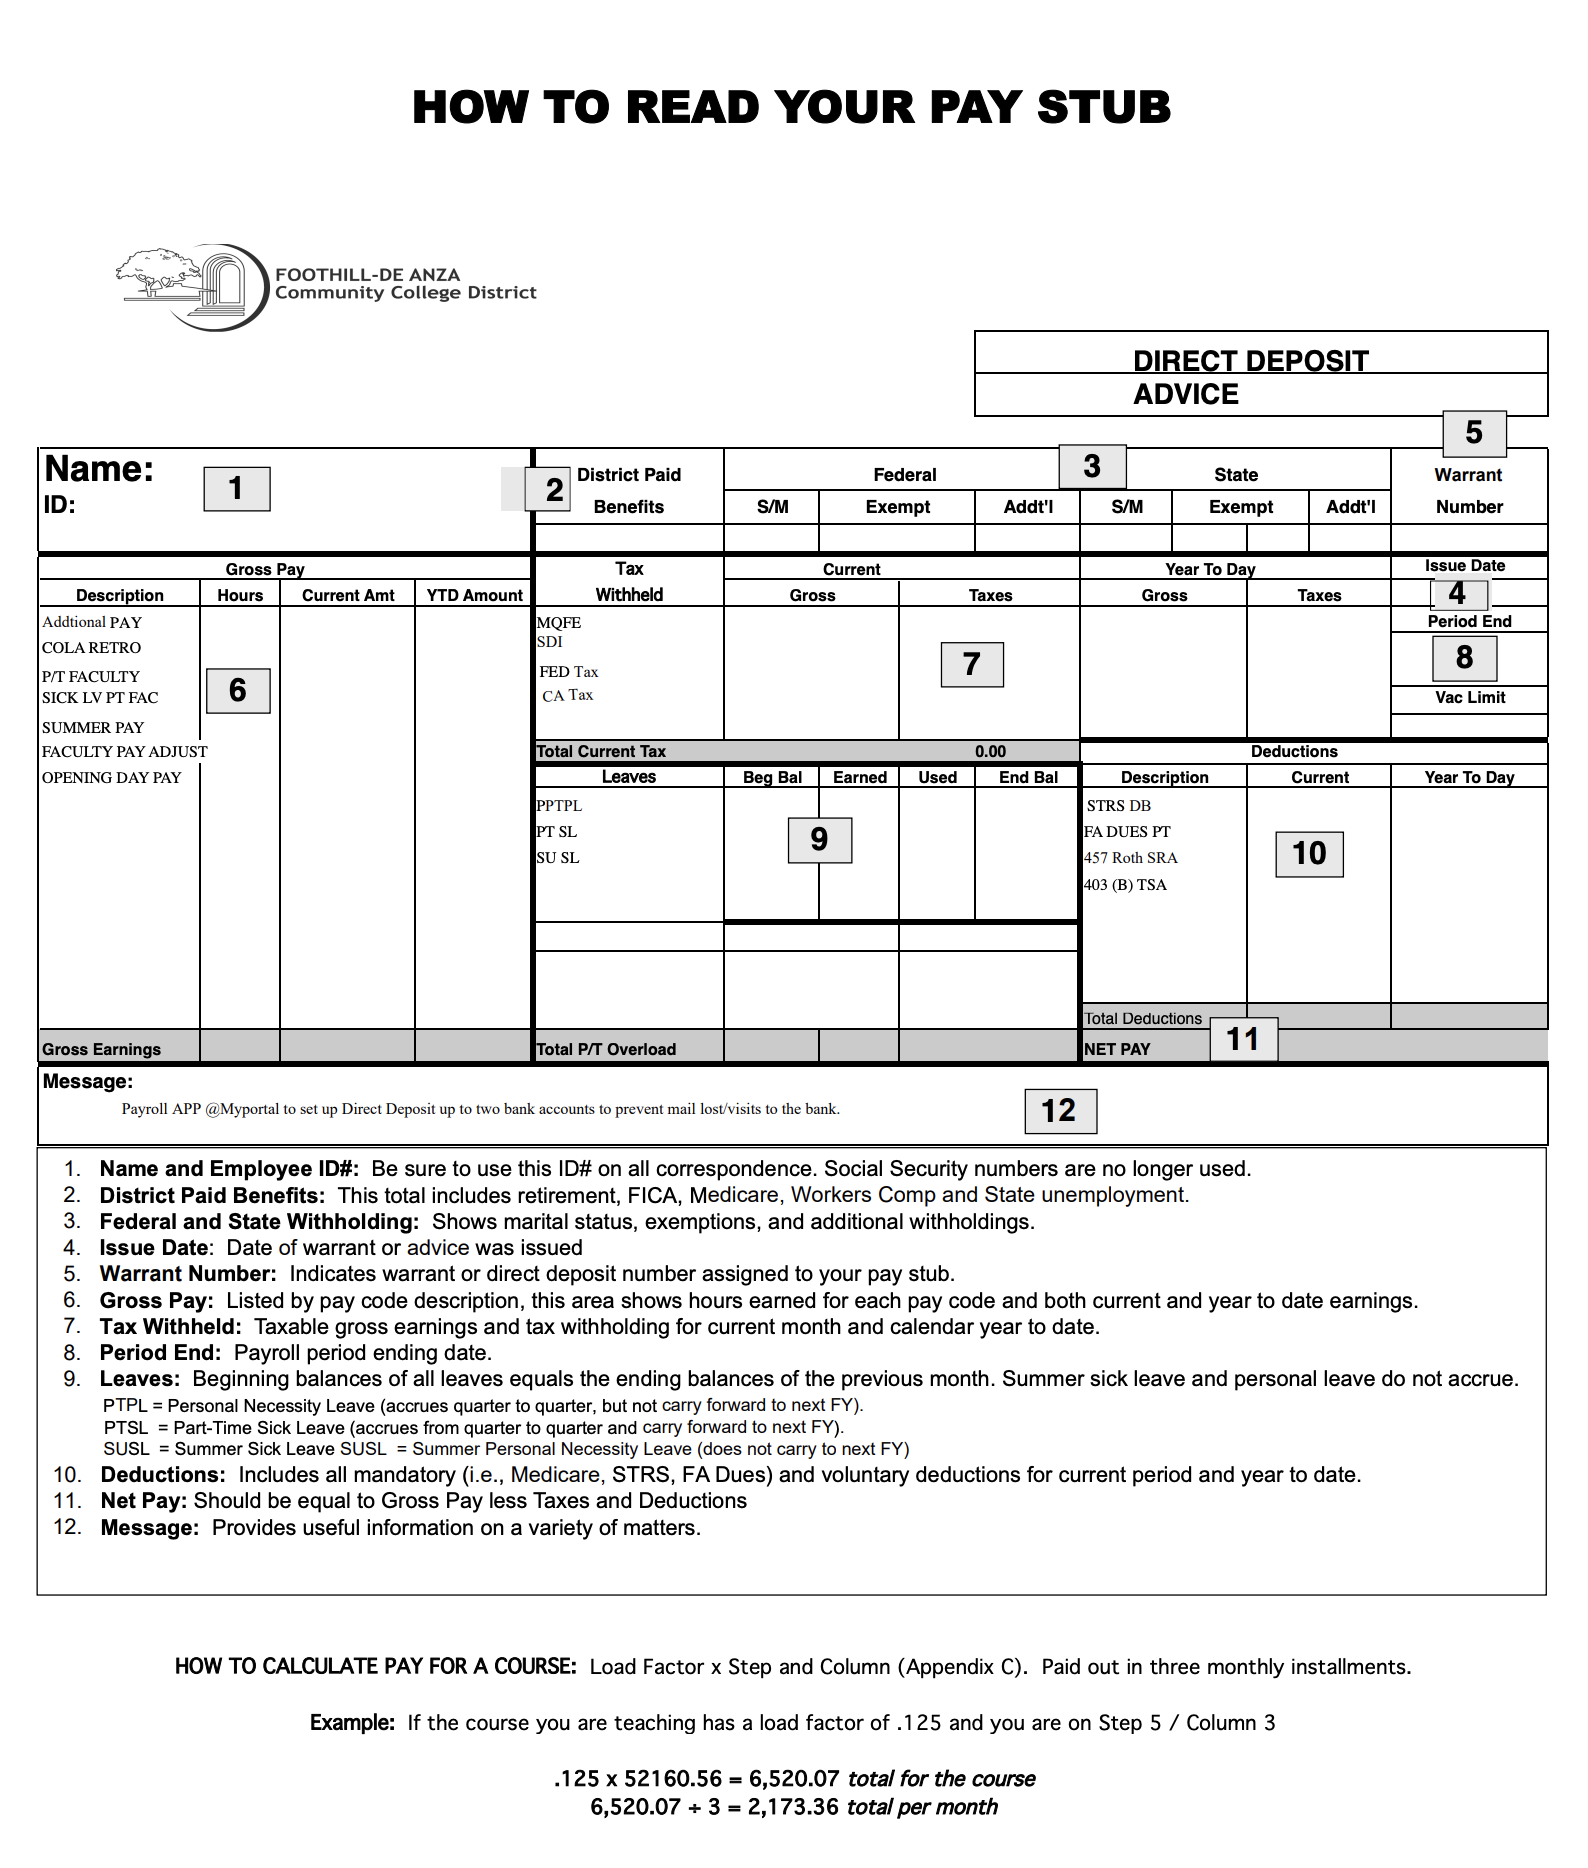
Most people glance at their pay stub and stop at the bottom line. That net pay number looks fine, so they move on. The problem is that the stub contains about a dozen line items that don't always add up the way you expect them to. When I first started reviewing pay stubs systematically for a consulting gig, I assumed they were straightforward. They aren't. The best way to approach Reading A Pay Stub Worksheet is to understand the anatomy of what you're actually looking at. A pay stub breaks down into three sections: gross earnings, pre-tax deductions, and post-tax deductions. The math between those three determines your final take-home. Simple concept, messy execution. Here is the formula most people miss because no one explains it this way. Your gross pay starts with your base earnings plus any overtime, bonuses, or shift differentials. From that gross, pre-tax deductions come out first. These include 401(k) contributions, health insurance premiums that are pretax, HSA contributions, and flexible spending account amounts. What remains is your taxable income for federal, state, and local purposes. Then the tax calculations happen. After that, post-tax deductions remove things like wage garnishments, Roth 401(k) contributions, and stock purchase plan withholdings. Whatever is left is your net pay.Reading A Pay Stub Worksheet
I built a simple spreadsheet template to track this breakdown across multiple pay periods. It started as a single tab for gross and net, then grew into a full worksheet with columns for each deduction category. The worksheet format lets you compare period over period and catch when something changes without a memo. A lot of payroll departments change rates quarterly and rarely send notifications about it. One specific problem I ran into involved a client whose stub showed a deduction labeled "Benefit Premium" that didn't match their known health insurance cost. I spent two days tracking it down by pulling plan documents and comparing them line by line. The deduction wasn't actually health insurance. It was a supplemental dental and vision plan bundled into a single payroll line item under the employer's benefits administration code. The stub didn't break it out separately. What finally made it click was cross-referencing the employee handbook, which listed the individual plan costs that added up to the total deduction amount. My workaround was to request a benefits summary directly from the plan administrator rather than relying on the payroll stub alone. Another edge case I encountered involved a retroactive pay adjustment that appeared on the stub as a single lump sum in the earnings section. The employee thought they had been overpaid because the gross looked inflated for that period. It turned out to be three months of missed overtime from a scheduling error being paid in one check. The withholding brackets pushed the effective tax rate higher for that single check, which created confusion about whether the calculation was wrong. It wasn't. But the stub format doesn't explain the compounding effect of stacking multiple periods of pay into one payment window.Common pitfalls people run into. The first is assuming your state taxes are deducted at the flat rate shown on the stub header. Many states use graduated brackets, and some cities have their own municipal tax that appears as a separate line but gets folded into the total tax withholding calculation. The second pitfall is misreading year-to-date columns. YTD numbers reset every January, so if you're reviewing a stub from late December or early January, the YTD fields will show drastically different values even if your current period hasn't changed at all. A third pitfall involves commission-based or hourly employees whose stubs combine regular and overtime hours into a single earnings line. Some payroll systems display this as a blended rate rather than separating regular hours from overtime hours at time-and-a-half. You have to know how to calculate the implied overtime rate from the total earnings divided by total hours to verify correctness. This usually takes about ten minutes per stub once you know the formula.
What to Look for When Checking Your Own Stubs
Start with the pay period dates and make sure they align with your actual work schedule. Mismatched periods are the most common error I see. An employee might receive a check for the wrong period, which cascades into incorrect YTD totals and potentially affects tax filing. Next, verify the gross earnings against your hours. If you're salaried, confirm that the pay frequency matches your agreement. If you're hourly, multiply your rate by your recorded hours and add overtime at 1.5x for anything over forty hours in a week. This is a federal requirement, and violations show up clearly when you do the math yourself. Check each deduction against your enrollment records. Health insurance should match what you selected during open enrollment or your life events change window. 401(k) percentages should reflect your contribution election. If you see a deduction you don't recognize, dig into it immediately. Unknown deductions are the fastest way to lose money on a pay stub. Tax withholdings are harder to verify without specialized knowledge. The W-4 you submitted determines federal withholding, and most payroll systems use IRS percentage method tables. State tables vary. You can approximate correctness using the IRS withholding calculator online, but the results won't be exact because your employer may use different payroll cycles or pre-tax adjustment timing.The Hard Truths About Pay Stub Accuracy
Pay stubs are not always accurate. Payroll systems make errors. Human input errors happen. Class code misclassifications can cause workers comp premium issues that show up as unexpected line items. The system is automated enough to process millions of payroll runs correctly, but it isn't infallible. Your first line of defense is reading the stub carefully and questioning discrepancies. A worksheet tracking your pay stubs over six months or more will reveal patterns that single-stub review misses. You'll start noticing when certain deductions shift, when tax withholdings change unexpectedly after a raise, and when overtime pay calculation seems consistently off by a small margin. That small margin matters when you're building a financial picture. I've seen people miss a duplicate deduction for several months because both the old stub and a corrected stub carried the same health insurance line item. The duplicate didn't appear as a single obvious error. It was buried across two different pay periods with slightly different reference numbers. A good Reading A Pay Stub Worksheet would flag this because you can compare total deduction amounts against your expected rates for that plan tier. When the total exceeds what you're supposed to pay, something is wrong. Another scenario where pay stubs fail you entirely is independent contractor payments versus W-2 employee payments. Contractors receive 1099 forms, not pay stubs. If your employer gives you a pay stub when you should be classified as a contractor, or vice versa, the tax implications are significant. Reading a pay stub doesn't tell you your employment classification directly, but it does signal it. W-2 stubs show tax withholdings. 1099 income shows no withholdings.For anyone serious about understanding their compensation, keeping a systematic record is worth the effort. The initial setup takes about twenty minutes. Ongoing maintenance is roughly five minutes per pay period. The alternative is discovering a payroll error three months later when tax season arrives and the paper trail is scattered across email attachments and printed stubs. The fundamental takeaway is that a pay stub is a document you should review, not just glance at. Most of the information you need to protect yourself is there. The challenge is knowing where to look and what to compare it against. Once you build the habit, it becomes automatic. Most people don't build that habit, and they pay for it later.