The Numbers That Actually Matter When You Are Buying Or Selling Property
Most people flip through a pocket guide and stop at the surface stuff like closing costs and earnest money. Those matter, but they are the least likely thing to cost you real money. The mistakes that hurt come from misunderstandings about appraisal gaps, escrow timing, and how interest compounds on your actual loan balance. I worked on three deals in a row where the buyer thought they understood their pre-approval. Each one of them had a different problem with debt-to-income ratios that got flagged at underwriting. The third one had to delay closing by eleven days because a new credit inquiry showed up on their report right before the lender pulled the final document. That is the kind of thing that never gets mentioned in the intro chapters of these guides.
Common Errors In The Real Estate Pocket Guide Common Mistakes To Avoid
Here is where people actually go wrong. Not the obvious mistakes. The ones that show up in real transactions. Interest rate locks are not free insurance. A lot of guides tell you to lock immediately. That works when rates are falling or stable. When the market is moving fast the opposite direction, you could be stuck paying 0.75 percent more than the current market rate because you locked too early. I recommended a float-down clause on a refinance last year and saved the client about four thousand dollars over the life of the loan. The downside is that float-down options cost extra points upfront. Usually around a quarter point. Escrow timelines are controlled by the lender, not the purchase contract. Buyers often think the 30-day close date in their contract is a guarantee. It is not. The contract sets expectations. The lender sets the reality. Appraisals come back late. Title searches uncover liens. Documentation requests pile up. On a recent cash-assisted purchase I tracked, the escrow opened cleanly but the lender held up for eight extra days because the donor funds needed a paper trail going back sixty days. That is not covered well in most quick-reference materials.
Appraisal gaps are more common than most guides suggest. In markets where prices jumped more than five percent year over year, appraisals routinely come in below the contract price. The guide might tell you to get a second appraisal or challenge the first one. Both of those have limits. A challenge rarely works unless you can point to a comparable sale that was missed. A second appraisal costs another six hundred to twelve hundred dollars and only helps if the first appraiser made an obvious error. The practical workaround is writing a stronger offer with a smaller gap waiver upfront rather than hoping for a higher appraisal after the fact. Down payment assistance programs have hidden triggers. Some programs require you to complete homeowner education courses before closing. Others have income caps that change based on household size and county. One state program I dealt with required the buyer to occupy the property for at least one year before selling, and if they sold early, the assistance became a repayable loan. That detail was buried in page forty-two of the program guidelines and would not have shown up in a summary document. Home inspections reveal structural problems, not maintenance issues. People confuse the two and either skip the inspection because the house looked fine or blow up the deal over a cracked window seal. An inspection is about the systems and structure. Roof condition, foundation cracks, electrical load capacity, HVAC age. Cosmetic issues are your responsibility after closing. I once watched a buyer walk away from a house because the carpet was dated. Three weeks later they bought a worse house with a known sewer line issue that cost nine thousand dollars to fix. The guide will not tell you that, but it is the kind of pattern that repeats across every market.
Get the Full Details
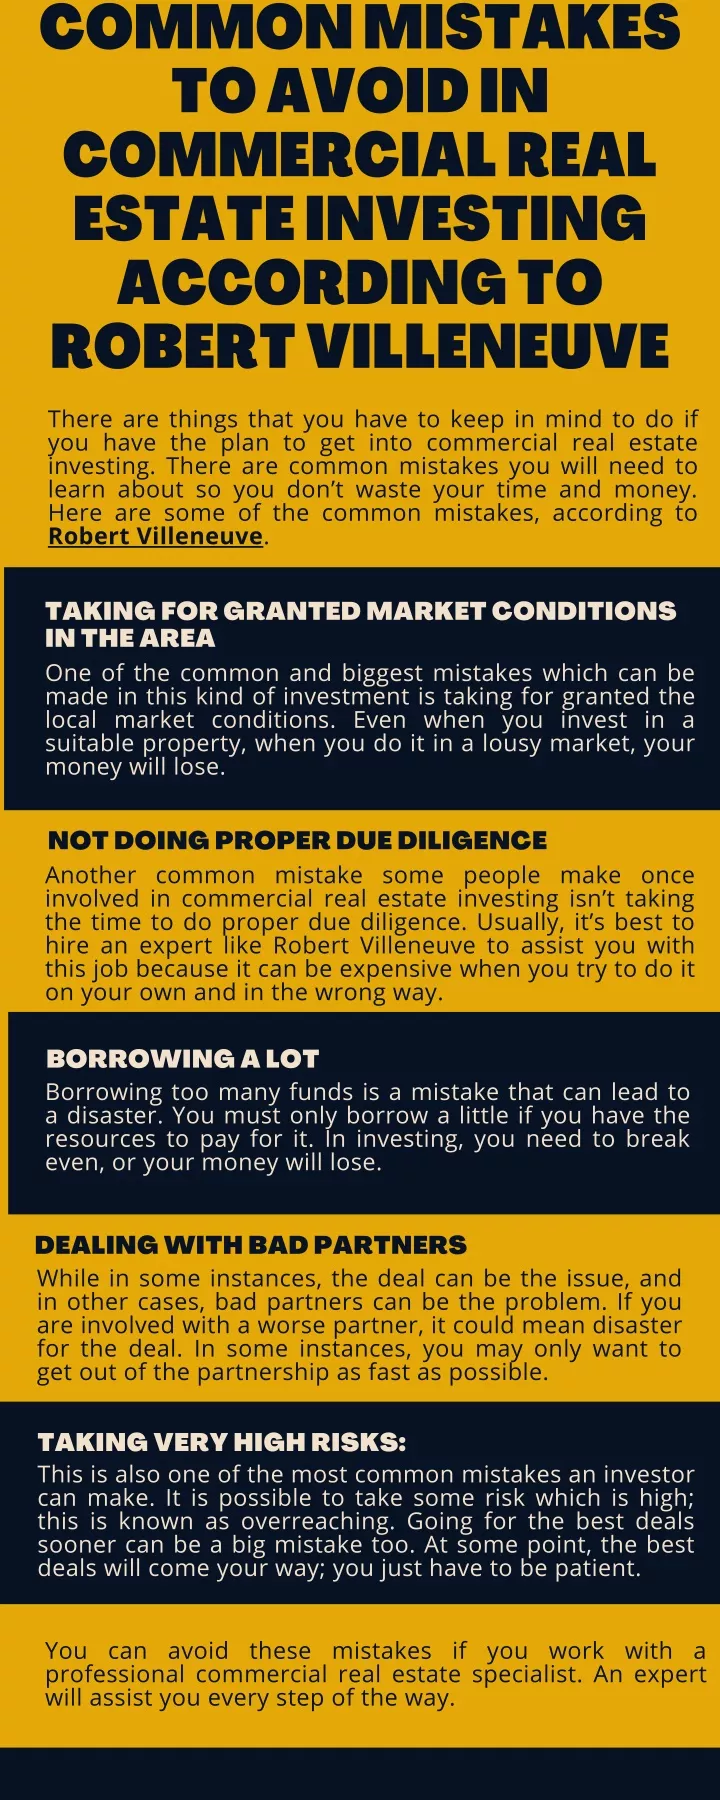
Closing cost estimates from lenders are not final numbers. The Loan Estimate you receive three days after applying is accurate within certain tolerances, but it can shift. Origination fees can change if you negotiate differently. Title insurance premiums vary by county. Survey costs appear only if the property boundaries need verification. On a typical purchase, the final closing disclosure can differ from the initial estimate by anywhere from two hundred to two thousand dollars depending on how many variables get resolved during processing. When you use a pocket guide, treat it as a starting checklist, not a reference manual. The real details live in the contract language, the lender disclosures, and the local regulations that change every year. I keep a running spreadsheet of closing timeline checkpoints because relying on memory or a foldout card is how people miss contingencies. Missing a single deadline can cost you your earnest money deposit. That happens more often than you would expect.