How the whole thing actually works, not what the brochures say
Rent to own RV programs are basically a lease-to-own arrangement where you pay a monthly fee that gets partially applied toward the purchase price. You're not renting a trailer and hoping to buy it later. The contract itself is structured so that a portion of your payment reduces the balance over time, and at the end of the term you either buy it or walk away. Simple enough on paper. The companies running these programs make their money from the markup. An RV that retails for $45,000 will often be listed at a higher value in the rent-to-own contract, and the monthly payments are calculated to cover that inflated price plus interest disguised as a "rental premium." You'll pay more overall than if you financed straight through a dealer, but the approval bar is lower and the credit check is softer.
What to look for when you find a Rent To Own Rv listing
The first thing I always check is whether the company actually holds the title or if they're just brokering the deal. Some outfits operate as middlemen who collect your payment and forward it to a lender. That adds a layer of risk because if they mismanage the paperwork, your payments might not be building equity at all. I learned this the hard way with a unit I looked at in 2022. The broker was forwarding payments to three different entities without clear documentation. I stopped the deal and walked away. Took me two weeks to get my deposit back because the contract said deposits were non-refundable within 30 days, but since they'd never actually sent a single payment to any lender, I cited breach of good faith and got it returned after some back and forth. The second thing is the rent credit percentage. Some programs offer 25% of each payment going toward the purchase price. Others go as low as 10%. A 10% credit on a $1,200 monthly payment means only $120 builds equity. Over 36 months that's $4,320. Compare that to a program offering 30%, which would give you $12,960 in equity. The monthly payment might look identical between the two, but the end result is completely different. Always read the contract line by line before signing anything. The third detail nobody mentions is the maintenance responsibility split. In most rent-to-own agreements, you're responsible for all repairs once you take possession. That means a new water pump or a failing HVAC compressor is on your dime, not theirs. I've seen contracts where the company covers major mechanical failures but not wear items like tires, brakes, or seals. Make sure you know exactly what falls on you before you move in with the unit.
Then there's the early buyout option. Some companies let you purchase the RV at any time during the lease term at the current market value or the original contract price, whichever is lower. Others lock you into the full contract price regardless of depreciation. If you plan to buy early, find out the buyout terms upfront. A contract that forces you to pay the full inflated price even after 18 months of payments is a bad deal if the RV has already depreciated significantly. Rent to own RV contracts also vary on whether you can sublet or use the unit commercially while under the agreement. Most prohibit it, but a few allow it with written permission. If you're looking at this as a side income stream through vacation rentals, confirm that in writing before you sign. Verbal promises don't hold up in arbitration. The biggest trap I see people fall into is not calculating the total cost of ownership. Add up all the monthly payments, plus any application fees, inspection fees, and the final purchase price, and you'll often see the total coming in 30 to 50 percent above what you'd pay financing the same RV outright. For someone with decent credit, traditional financing through a credit union usually costs less over the life of the loan. But if you have a 550 credit score and need a place to live or travel right now, rent to own is the only door that's open.
Get the Full Details
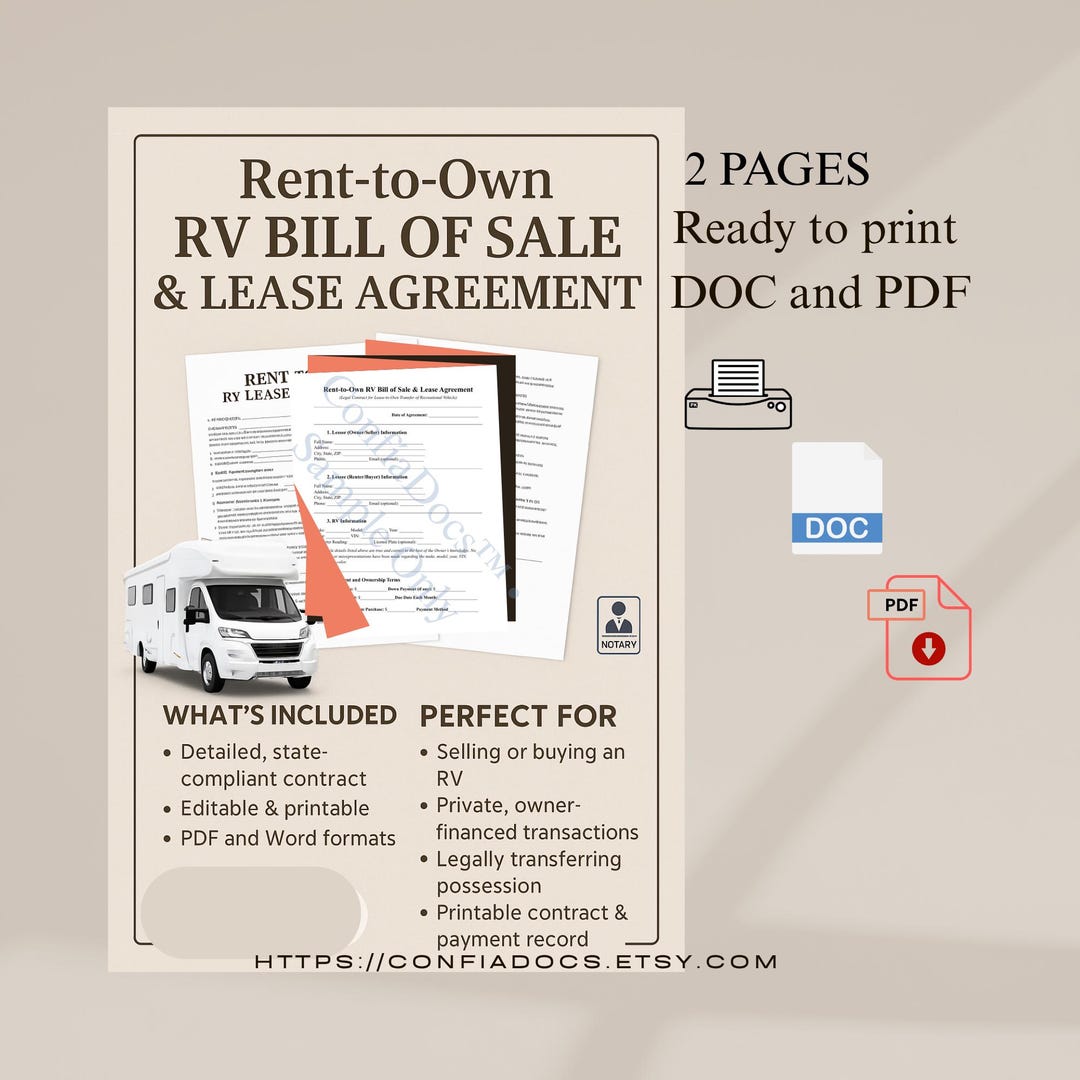
Another counter-intuitive thing: some of the larger national programs are actually easier to exit cleanly than the small local operators. I know that sounds backwards. The big companies have standardized contracts and automated processes. If you need to terminate early, you can usually call a number and get paperwork within 48 hours. The local outfit in a town of 10,000 might not have a dedicated contracts department, and resolving an early termination could involve mailing letters and waiting weeks for a response. Shop the process, not just the price. When you get to inspection, bring a checklist and take photos of every scratch, stain, and malfunction. I once took delivery of a unit with a cracked windshield that the previous renter had reported but the company never logged. When I signed the intake form, it looked like new damage because nothing was documented. The contract stated I was responsible for all damage beyond normal wear, and I ended up eating a $600 windshield replacement. Photograph everything. Have the employee acknowledge the condition on the intake report before you sign. The other thing people overlook is the insurance requirement. Most rent-to-own programs require you to carry full coverage insurance with them named as loss payee. That's standard for financed vehicles, but the minimum coverage amounts can be higher than what you're used to. One program I looked at required $500,000 in liability coverage, which added about $80 a month to my insurance bill compared to my standard auto policy. Factor that into your monthly budget or the savings from a soft credit check disappear fast.
If the rent-to-own route isn't working out for you partway through, refinancing the remaining balance is sometimes possible. A few companies will let you convert to a traditional installment loan if your credit has improved. Others won't allow it and require you to sell the unit back, usually at a loss. Ask about the conversion clause before you sign the initial contract. It saves a massive headache later if your financial situation changes. There's a niche approach some people use that's worth mentioning. Buy a used RV privately with cash, then offer it to a rent-to-own company on consignment. They handle the tenant placement and collections while you retain ownership. You still get monthly payments and eventual sale proceeds, but you're the lender instead of the borrower. It only works if you have a unit that's already paid off and the company accepts third-party placements, which most don't, but it's an option if you can find one that does. The bottom line is that rent to own RV programs exist for a reason. They fill a gap for people who can't qualify for traditional financing and need mobility now rather than in two years. They are not cheap. They are not the best deal on paper. But they are real and they do work when you understand the contract terms, document everything, and calculate the total cost before committing. If your credit is salvageable, try to improve it for six months and then go the financing route. If you need this solution today, read every page of the agreement and negotiate the rent credit percentage while you're at it.