How to Estimate Reverse Mortgage Payments Without Sharing Your Data
I spent three weeks last fall digging through lender portals just to find one that didn't require a hard credit pull before showing me an actual numbers screen. Most of them do. You type in your address, your age, your home value, and suddenly they're pulling your credit report from TransUnion. It's a sales funnel, not a calculator. The ones that work without any of that tend to be public-domain tools hosted by HUD or university extensions. I'll tell you exactly where to find them and what to watch out for. The cleanest starting point is the HUD reverse mortgage calculator at hud.gov. It lives at the link labeled "Reverse Mortgage Calculator" on the HUD reverse mortgage page. You don't create an account. You don't enter your name, your address, or your Social Security number. You put in a property value, your age, and the current interest rate range, and it spits out principal limits and monthly payment estimates. The tradeoff is that it gives you illustrative ranges, not binding offers. That's the point. You get ballpark figures fast enough to decide whether a particular scenario is worth bringing to a loan officer. I used it to sanity-check a quote a broker in Tampa sent me for a 78-year-old borrower with a $420,000 home. The broker's number came in at roughly $2,100 per month for the first five years. HUD's calculator showed $1,950 to $2,250 depending on whether you picked the floating or fixed track. That told me the quote was in the right neighborhood and not padded. Without that check I would have either accepted it or walked away based on a gut feeling.
Another solid option is the AARP reverse mortgage calculator. Same pattern: no login, no personal data, just inputs and outputs. It doesn't track cookies aggressively like some commercial sites, which matters if you're comparing three or four scenarios back to back. I've noticed AARP's numbers run about five percent higher than HUD's on the monthly side for the same inputs. That's likely because AARP embeds a slightly more optimistic annuity pricing factor. Neither is wrong. They're just using different reserve assumptions.
What the Calculators Actually Show You
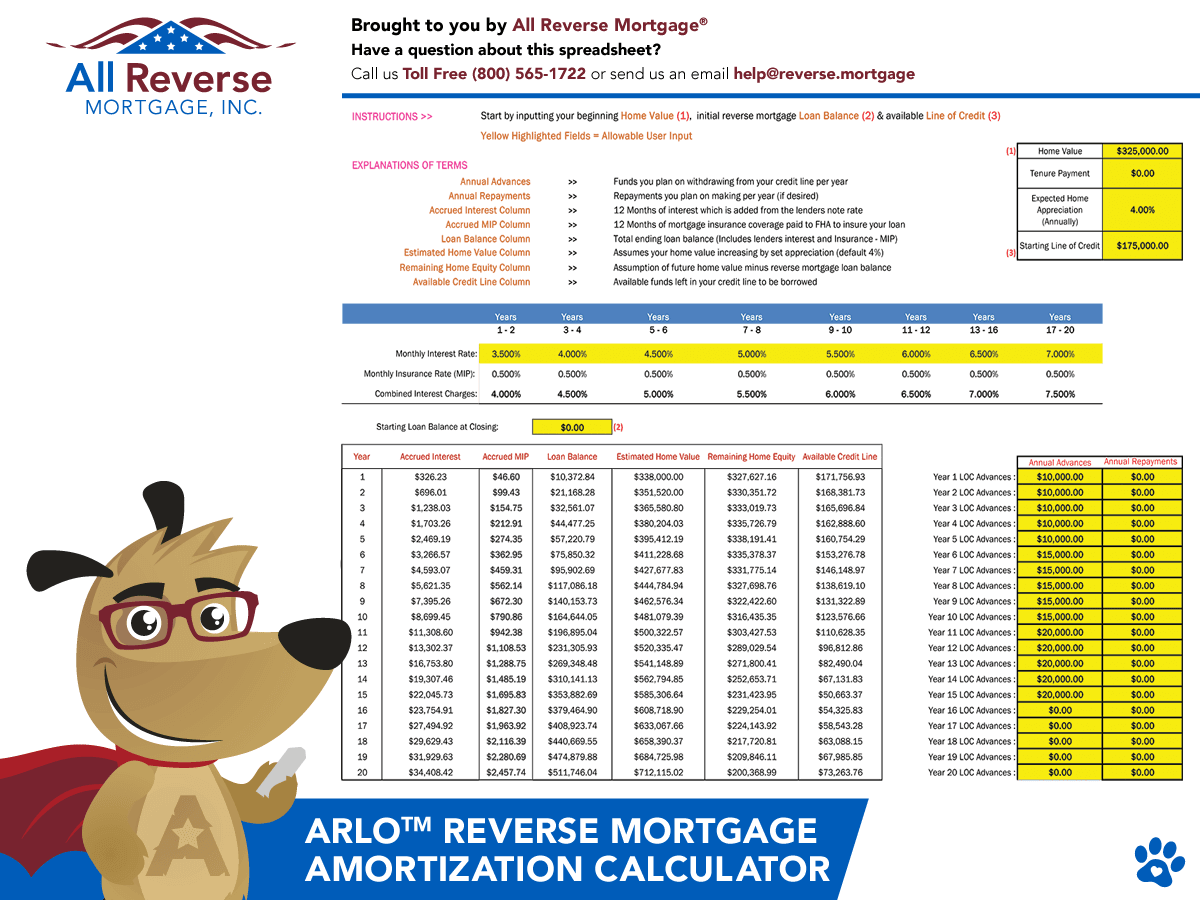
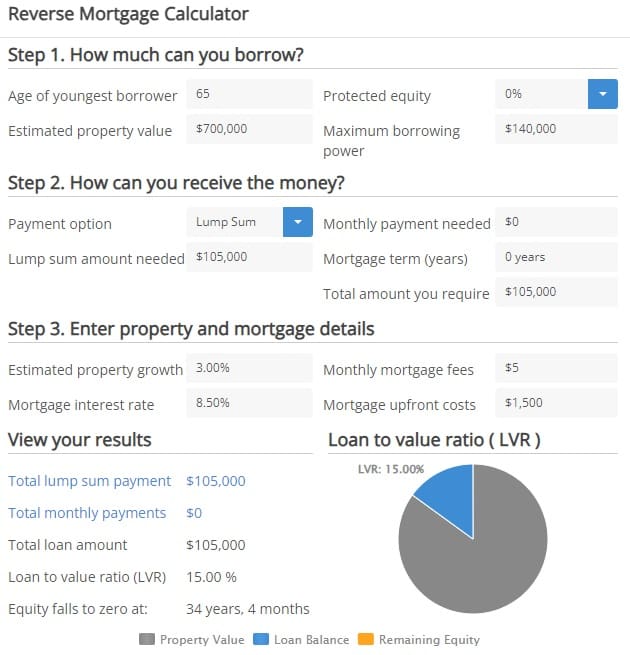
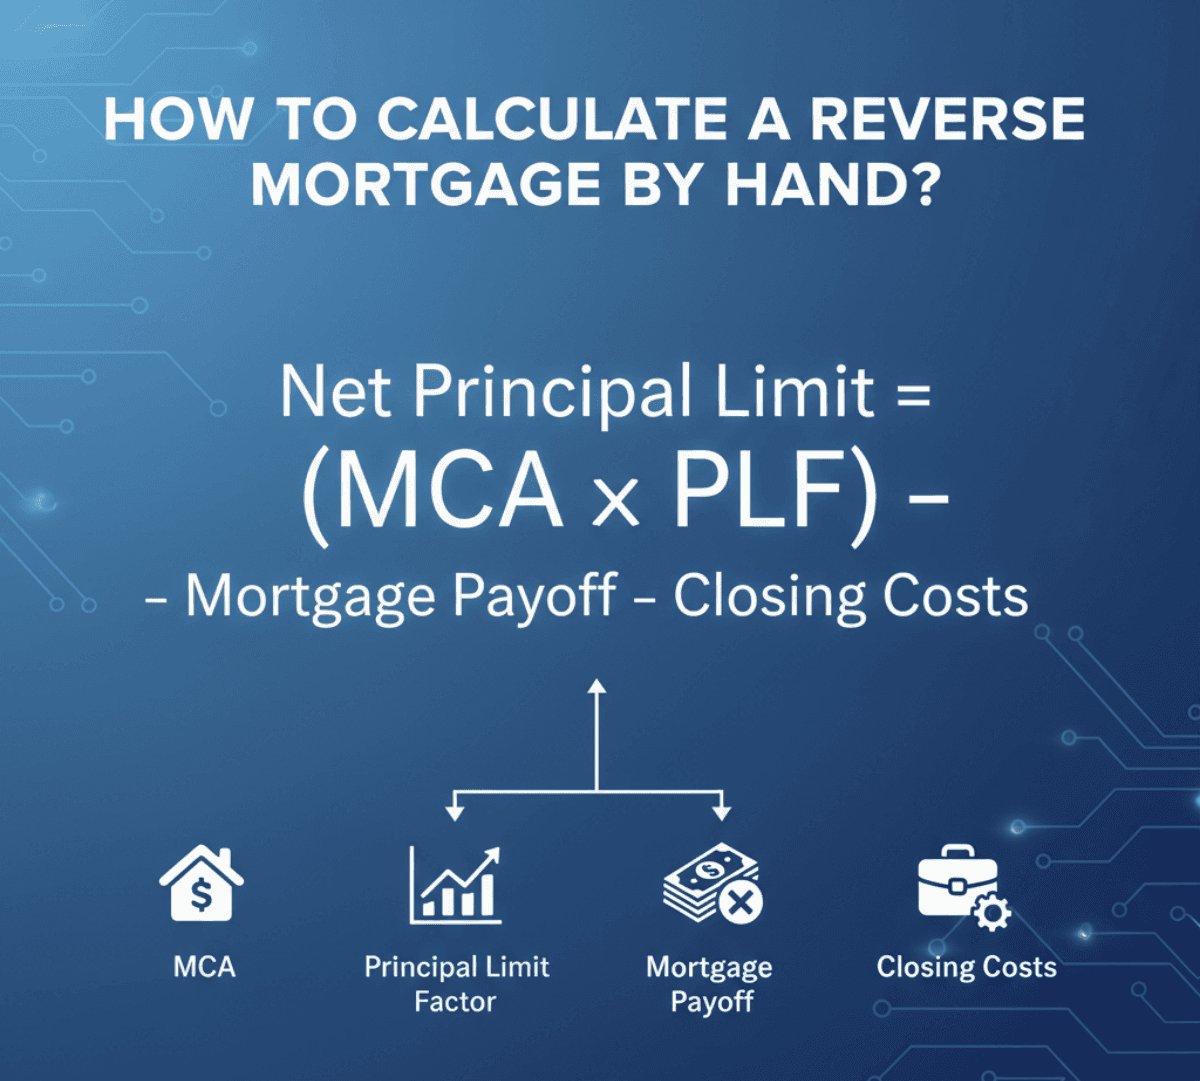
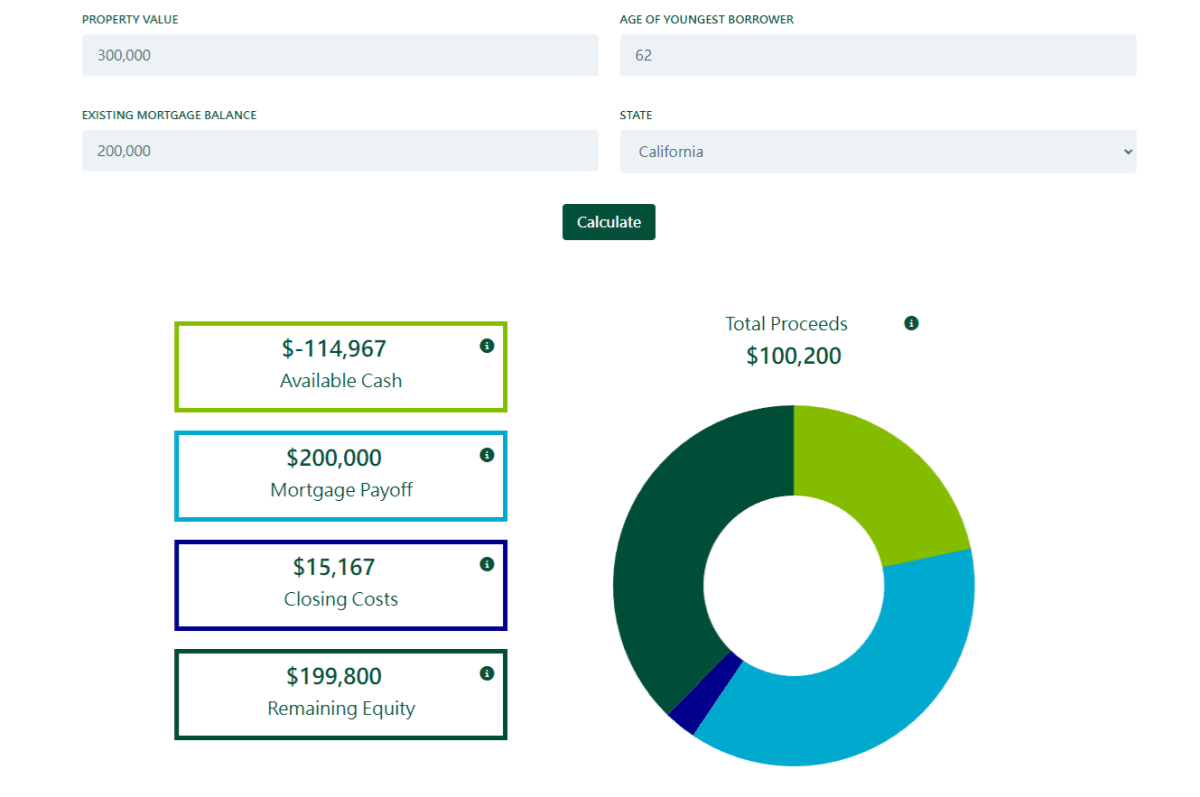
A reverse mortgage calculator gives you the principal limit factor, the maximum amount you can borrow, and often a projected monthly disbursement schedule. The principal limit factor is the percentage of your home equity the lender will let you convert into cash at your age bracket. At 62 it's roughly 50 to 55 percent of appraised value. At 75 it climbs toward 65 to 70 percent. At 80 it can reach 75 percent or so. The exact number changes with the interest rate environment. When rates are below five percent, the factor jumps. When rates sit above six, it drops. The calculator captures that automatically. Most calculators also show you two payment tracks: a line of credit that grows over time, and a tenured monthly payment that stays level. The tenured track is what people usually want to see first. The line of credit is the one that appreciates and can cover future needs without a new application. Understanding both matters. I've seen borrowers focus entirely on the monthly number and miss that the line of credit option would have been more useful when their roofing cost showed up three years later. The calculator won't show you closing costs directly. It assumes a standard set, but your actual costs depend on the state, the property type, and whether you're doing an HECM or a proprietary product. Expect $3,000 to $6,000 in upfront fees for a typical HECM on a single-family home. That's not trivial. It reduces the net proceeds you actually receive. Some calculators let you subtract closing costs from the principal limit. If yours doesn't, do it manually before you present the number to a borrower or yourself.
Get the Full Details
A Specific Edge Case I Ran Into
Last winter I was running numbers for a couple in their late seventies who owned a condo in Florida with a HOA special assessment pending. The calculator assumed clean title and steady property values. It didn't know about the $18,000 special assessment the board had just levied. That assessment effectively reduced their available equity. I had to subtract it from the home value input before running the calculation. If I hadn't, the calculator would have shown a principal limit about $1,500 too high. In a tight margin situation, that's the difference between qualifying and not. Here's the workaround I use now: always enter the property value minus any known assessments, liens, or escrow obligations into the calculator. Write down what you subtracted and why. When you bring the numbers to a loan officer, they'll appreciate the honesty and it saves everyone time. The assessment itself will come out during underwriting anyway, but showing you already accounted for it makes the process smoother. Another edge case that catches people is the property type mismatch. The calculators assume a standard single-family attached or detached home. If you're looking at a cooperative, a timeshare fraction, or a manufactured home that's classified as personal property, the numbers shift. HUD's calculator doesn't handle co-ops cleanly. You'll get a number, but it won't reflect the actual lending constraints. I've learned to flag those early and switch to a manual estimate or a lender-specific tool instead of trusting the calculator blindly.
Common Pitfalls and What Beginners Miss
The biggest mistake I see is treating the calculator output as a final offer. It's not. It's a planning screen. The real principal limit comes down to the appraised value, the age of the youngest borrower, the current MIP rates, and the lender's margin. Change any of those and the number moves. A 200-point shift in the interest rate can change a monthly payment by $50 to $100 over the life of a typical loan. That matters when you're budgeting for medical costs or property taxes. Another nuance people overlook is the climbing line of credit. The calculator shows it growing at a theoretical rate. In practice, the growth is guaranteed by the FHA insurance fund, which means the unused portion of your line of credit actually increases annually by a set percentage tied to the principal limit factor. This is one of the real advantages of a reverse mortgage that calculators barely explain. If you take a small monthly payment now and leave most of the line untouched, it can grow significantly over five or ten years. That's not marketing copy. It's the mechanism. I've watched it save borrowers from having to refinance when unexpected expenses hit later. A third pitfall is ignoring the total cost of ownership. Reverse mortgages carry monthly mortgage insurance premiums, origination fees, and servicing charges. The calculator folds some of this in, but not all. If you're comparing a reverse mortgage to a home equity line or a traditional refi, you need to add those costs to your total. Otherwise the reverse mortgage looks cheaper than it actually is on an annualized basis.
When a Calculator Fails Completely
There are scenarios where even a good calculator gives you misleading numbers. If the home has significant deferred maintenance, the calculator can't account for it. If the borrower has a complex title situation with multiple liens, the calculator won't adjust for the priority issues. If the property is in a flood zone with elevated insurance costs, the monthly housing payment estimate will be low. In each case, the number is still useful as a baseline, but you should treat it as a starting point, not a conclusion. For high-value homes above the HECM lending limit, the calculator shows you the FHA-insured amount only. The jumbo portion requires a proprietary product from a private lender. The numbers diverge significantly from the HUD output. I once worked with a client in Connecticut whose home was worth $1.2 million. The HUD calculator showed a monthly payment around $3,200. The actual proprietary product offered $2,800 because of the higher interest rate and different pricing model. That's a $400-per-month gap that matters over a five-year horizon. If your home value is above roughly $1 million depending on the county and current rates, expect the calculator to understate the gap between FHA and proprietary products.
How I Actually Use These Tools in Practice
My routine is simple and repeatable. I open the HUD calculator and the AARP calculator side by side. I enter the same numbers into both and note the variance. If the variance is under five percent, I trust the range. If it's over ten percent, I dig into why. Usually it's a difference in how they treat the interest rate assumption or the MIP schedule. Then I run a third check with a lender-specific calculator if the borrower already has a pre-approval. That gives me the most accurate snapshot because the lender's margin is baked in. I always write down the inputs: property value, age, interest rate, and the date. The date matters because rates move. A calculator result from six months ago can be off by a few hundred dollars compared to today's pricing. I've lost track of how many times I've pulled an old estimate and presented it without realizing the rate environment had shifted. Writing the date forces me to notice. If you want a downloadable alternative that doesn't require personal information, the HUD principal limit factor tables are public. You can download them as PDFs from the HUD website and use them with a basic spreadsheet. That gives you full control over every variable and lets you build scenarios without hitting any rate limits on web calculators. It takes about 20 minutes to set up if you know Excel. After that, you can generate estimates in seconds.
The bottom line is that reverse mortgage calculators without personal information exist, they're accurate enough for planning, and they save you from giving away data you don't need to share until you're ready to talk to a lender. The ones I recommend are the HUD tool, the AARP tool, and the principal limit factor tables for advanced users. Use them as screening devices, not as final quotes. And always check your inputs against a real lender's numbers before you make any decisions based on what the calculator showed you.