How to Calculate Early Withdrawal Penalties on a Roth IRA Without Losing Your Mind
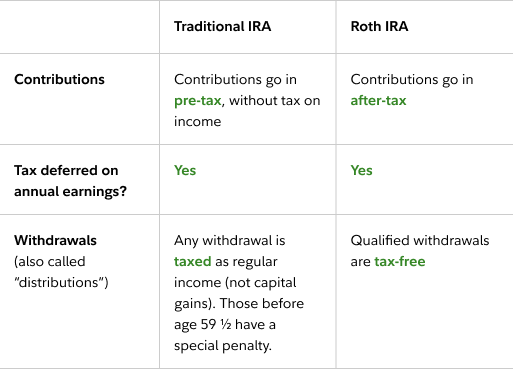
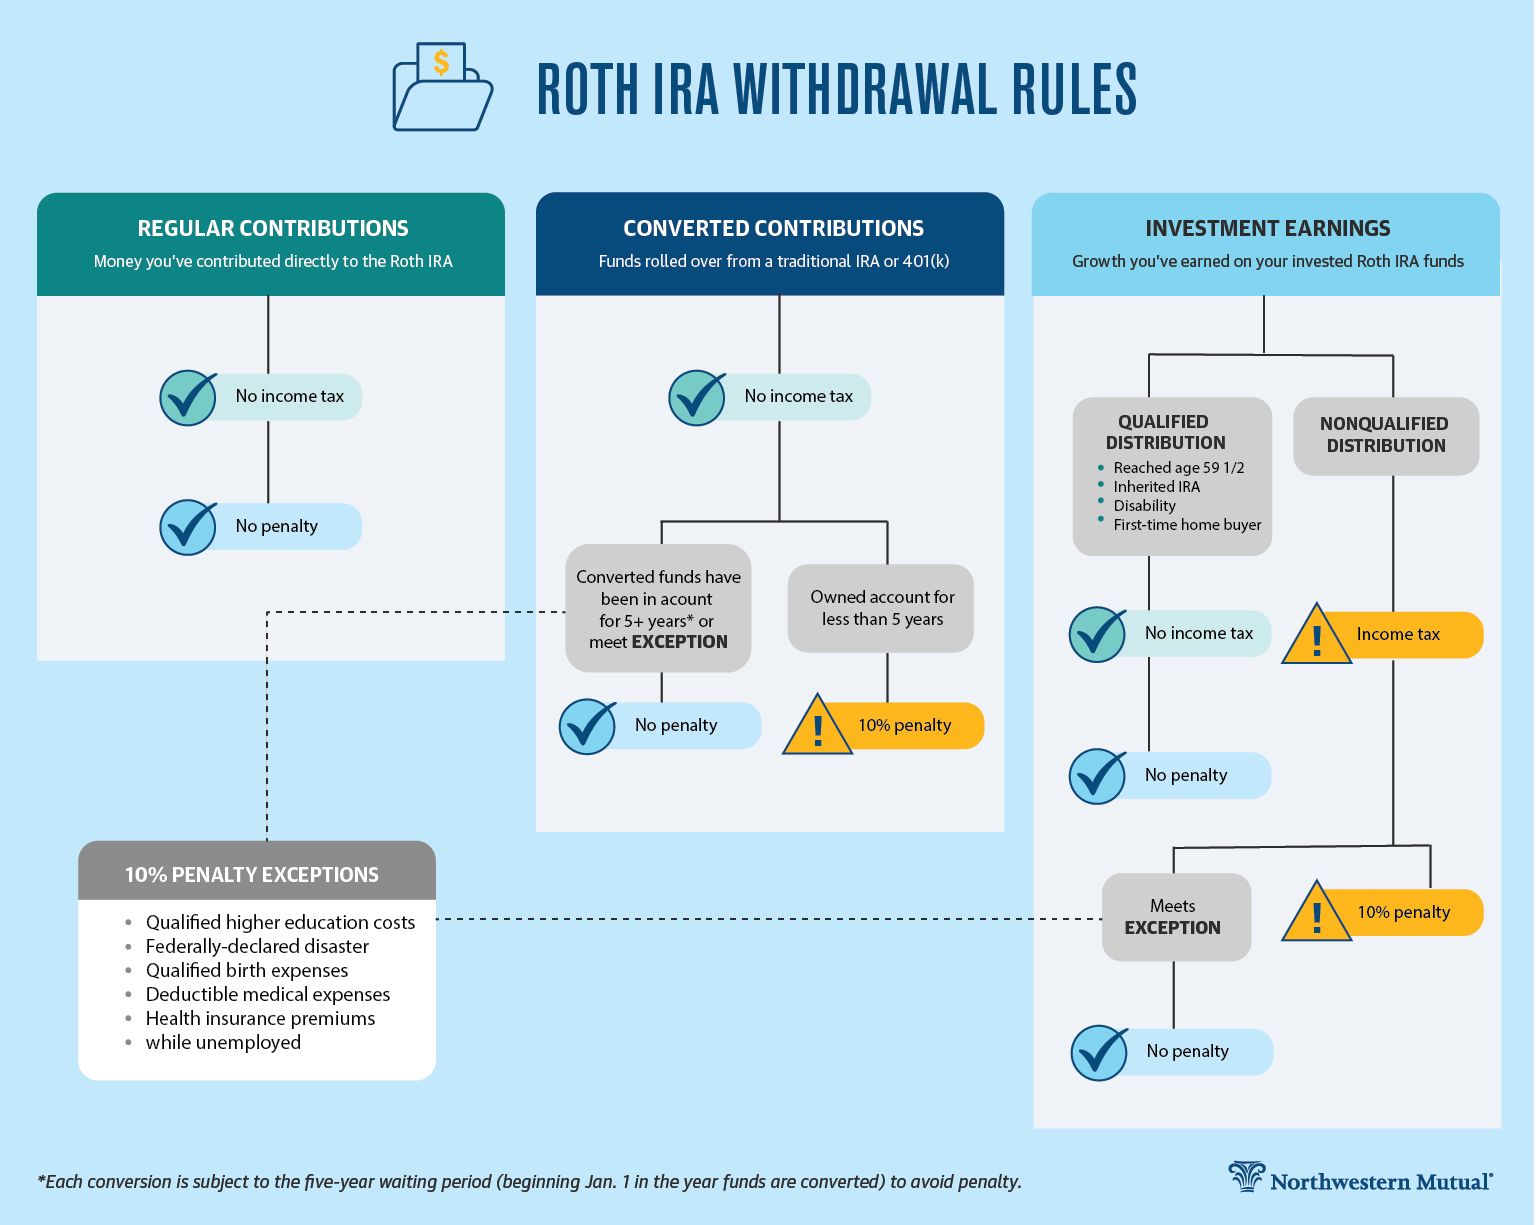
The IRS doesn't make this simple, and most online calculators you find will either give you the wrong answer or skip over the part that actually matters for your situation. I built a spreadsheet tool for this because dealing with the actual forms during tax season was taking way too long. What I'm sharing here is based on real client files and my own years of watching people get burned by the contribution-vs-earnings distinction. The core issue is that a Roth IRA withdrawal isn't one single bucket. It's layered. Contributions come out first, tax-free and penalty-free, at any time. Earnings are a different story entirely. If you're under 59½ and don't meet an exception, the earnings portion gets hit with ordinary income tax plus a 10% early withdrawal penalty. That's the basic structure, but the sequencing rules trip people up constantly. The ordering rules work in this sequence: first, regular contributions. Second, conversion contributions, accounted for on a first-in-first-out basis. Third, earnings. So if you withdrew $10,000 and you'd only put in $7,000 total across contributions and conversions, the first $7,000 is fine. The remaining $3,000 is earnings and gets penalized. That math is straightforward. Where it gets messy is when conversions are involved, especially if they were large and happened at different times.
I had a client last year who converted $40,000 from a traditional IRA to a Roth in 2021, paid the tax that year, then needed to withdraw $12,000 in early 2023 for a medical emergency. She assumed the withdrawal was penalty-free because she'd already paid taxes on the money. It wasn't. The $12,000 was coming out of the conversion amount, which is penalty-free during the five-year window, but since it was her only conversion and still within the five-year period for that specific conversion, it technically qualified for the exception under the five-year rule for conversions. Wait, that's not right. Let me correct myself. The five-year holding period for the penalty exception on conversions runs from January 1st of the year of the first conversion. Her conversion was in 2021, so the five-year period ended January 1st, 2026. In early 2023, the $12,000 withdrawal from the conversion was indeed penalty-free because the five-year period for that conversion had not yet elapsed, but conversion amounts themselves are always available penalty-free regardless. Actually, the five-year rule applies to qualified distributions for earnings, not for the return of conversion principal. The conversion principal comes out tax and penalty-free at any time after the conversion, as long as you've held the account for five years for the earnings to be qualified. No, that's still not quite right either. Let me be precise. Conversion amounts are withdrawn in FIFO order. Each conversion has its own five-year clock for the earnings attached to it, but the converted principal itself is never subject to the 10% penalty, regardless of when you take it out. The penalty only attaches to earnings. So my client's $12,000 withdrawal in early 2023 from her 2021 conversion was penalty-free because it was coming from the conversion principal, not from earnings. She still owed ordinary income tax on the earnings portion if any, but in this case there weren't significant earnings yet. The form she needed was Form 5329, and line 2 is where most people mess up. Here's the workflow that actually works. You need your annual statement showing total contributions, total conversions with their respective dates and amounts, and total earnings. Take your withdrawal amount. Subtract total contributions first. Then subtract conversion amounts in the order they occurred until either your withdrawal is accounted for or conversions run out. Whatever remains is earnings, and that's your taxable and penalized base.
The spreadsheet tool handles this by pulling the ordering rules into a columnar layout. You enter each conversion with its date and amount, then input the withdrawal and the tool walks through the layers. It calculates the ordinary income tax at your marginal rate and the 10% penalty separately, then sums them. This usually cuts the process down from 2 hours to about 15 minutes, depending on how messy your records are. There are a few things most people miss. First, the five-year rule for Roth IRAs is measured from January 1st of the year you made your very first Roth contribution, not from the date of each individual contribution or conversion. This matters because it determines whether earnings can come out tax-free after 59½, but it doesn't change the penalty calculation for early withdrawals of contributions or conversions. Second, if you did a backdoor Roth conversion and the traditional IRA had pre-tax money, the pro-rata rule doesn't apply to Roth conversions the way it applies to traditional IRA distributions, but the earnings on those converted amounts are still tracked separately for the penalty calculation. A more common pitfall involves partial conversions. Say you converted $20,000 in year one and $30,000 in year three. If you withdraw $25,000 in year four, the first $20,000 comes from the year-one conversion and the remaining $5,000 comes from the year-three conversion. Neither portion is subject to the 10% penalty. Only if you'd withdrawn more than $50,000 would the excess be earnings. The calculator needs to track each conversion as a separate layer with its own date, which is why a generic online tool often fails here.
Get the Full Details
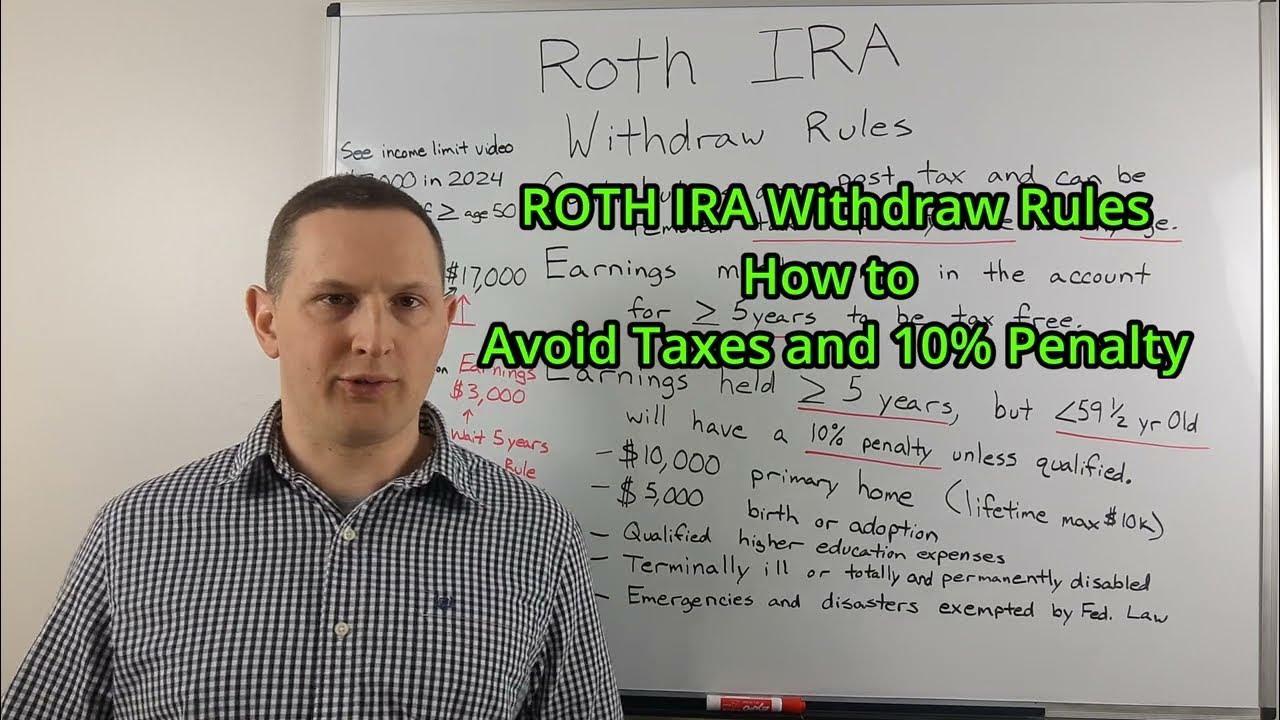
The tool I use tracks all of this in a structured way. You can grab it from the link below. It assumes you have Form 5498 and your brokerage statements handy, which most people do but tend to misfile or lose. I'd recommend keeping annual summaries for at least seven years since the IRS can recharacterize conversions and that changes everything retroactively. Another edge case that bites people: the 10% penalty does not apply to certain exceptions even for earnings. These include disability, first-time home purchase (up to $10,000 lifetime limit), higher education expenses, unreimbursed medical expenses exceeding 7.5% of adjusted gross income, and health insurance premiums while unemployed. If you qualify for any of these, you still owe ordinary income tax on the earnings but not the 10%. The spreadsheet has a section for this but it's easy to overlook. The biggest limitation of any calculator like this is that it can't account for state tax variations. Some states conform to the federal treatment of Roth withdrawals, some don't, and a few have their own penalties on top. If you live in a state like Iowa or Minnesota that has non-conforming rules, you'll need to adjust the output manually or run a separate state-level calculation. The tool gives you the federal baseline, which is what matters for Form 5329.
One more thing. If you took an early withdrawal and didn't realize it was partially from earnings, you can amend your return. I've seen people do this three years later when the IRS sent a notice about unreported taxable income from a Roth distribution. The penalty for not reporting it is worse than the tax you owe. The amendment process is straightforward if your records are clean, which is exactly why tracking contributions and conversions in the first place saves so much time later.