Understanding Roth IRA Early Withdrawal Penalties
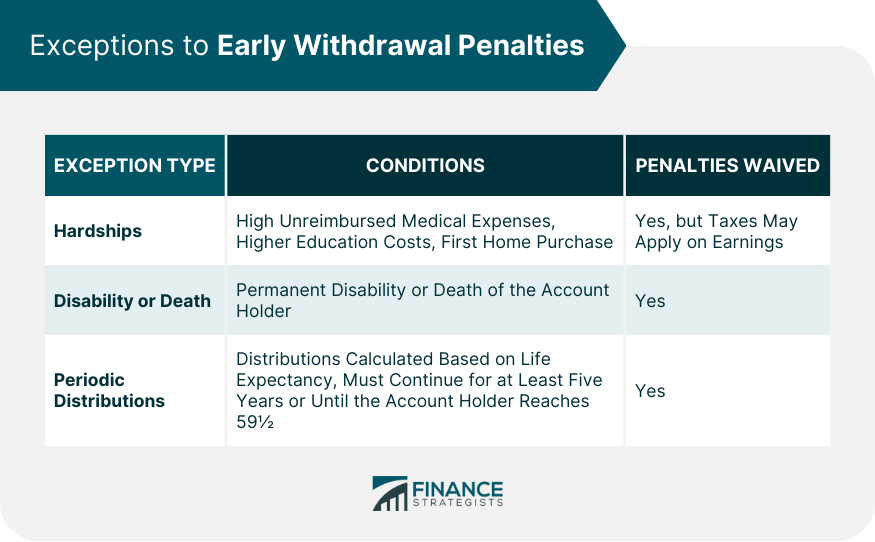
When you take money out of a Roth IRA before age 59½, the IRS doesn't just tax it — they penalize it. The standard rule is a 10% early withdrawal penalty on taxable distributions. But Roth IRAs are weird because of how they handle contributions versus earnings, and that's where most people get tripped up. I've seen a lot of folks overpay their penalties because they didn't separate these two buckets properly. At its core, the calculator needs three things: your total distribution amount, how much of that came from contributions (which are always tax- and penalty-free), and how much came from earnings. Contributions come out first under the ordering rules, and only the earnings portion can trigger both income tax and the 10% penalty. If you meet any exception — disability, first-time home purchase up to $10,000, qualified education expenses, substantial equal periodic payments — the penalty part drops away entirely. The calculator cross-references your situation against IRS exceptions and tells you exactly what you owe. I ran into this problem once when I was helping a client who had rolled over a 401(k) into a Roth IRA and then needed money for medical expenses. She'd contributed over several years at different income levels, and the conversion had complicated her basis tracking. A basic calculator just spat out a number based on her total balance, which was wrong because it didn't account for the ordering rules and her converted amounts versus contributed amounts being separated. I had to manually reconstruct her basis year by year using Form 8606 logic, which took about two hours but saved her roughly $3,400 in unnecessary penalties. The takeaway is that most free online calculators don't handle conversions properly. They treat all dollars the same, and that's a serious flaw.
The Common Pitfalls
Most people miss that Roth contributions and Roth conversions are treated differently for penalty purposes. Contributions leave penalty-free anytime because you've already paid tax on them. Conversions also leave penalty-free since you paid tax at conversion time. But earnings — that's where the 10% penalty lives if you're under 59½ and don't qualify for an exception. Another trap is the five-year rule. Even if you're over 59½, earnings can still be penalized if your Roth IRA is less than five years old. The clock starts from January 1 of the year you made your first contribution or conversion. A Roth Penalty Calculator that ignores the five-year rule will give you a false sense of security on those early withdrawals from older accounts. There's also the issue of partial conversions and partial withdrawals happening in the same tax year. The IRS requires you to track these separately, and the ordering rules apply per transaction, not per year. Most consumer calculators batch everything together and produce inaccurate results. You're better off working through Form 8606 line by line if your situation involves multiple years of contributions, conversions, and partial distributions.
What These Calculators Get Wrong
Let me be clear about the limitations here. The typical online Roth Penalty Calculator assumes a simple scenario: one contribution year, no conversions, no recharacterizations, and one clean withdrawal. If your situation has any of those complexities, the output is guesswork. I've seen tools that don't distinguish between traditional-to-Roth conversions and direct Roth contributions, which can shift your penalty liability by thousands depending on when you converted and whether your income was taxed at different brackets. Some calculators also ignore state-level penalties. A handful of states impose their own early distribution penalties on top of the federal 10%. If you live in California or Iowa, for example, you might be looking at an additional state tax hit that the calculator never mentions. You need to factor that in separately. For straightforward cases — someone who contributed consistently over the years and takes a single distribution — a Roth Penalty Calculator gets you in the right ballpark within minutes. For anything involving conversions, recharacterizations, or mixed withdrawal strategies, you're better off pulling your prior year Forms 5498 and 8606 and running the numbers manually, or paying a CPA who actually understands Roth ordering rules. The tool is fine for estimation, not for filing accuracy when your situation isn't basic.
Get the Full Details