Dealing with Rushmore Loan Management Complaints
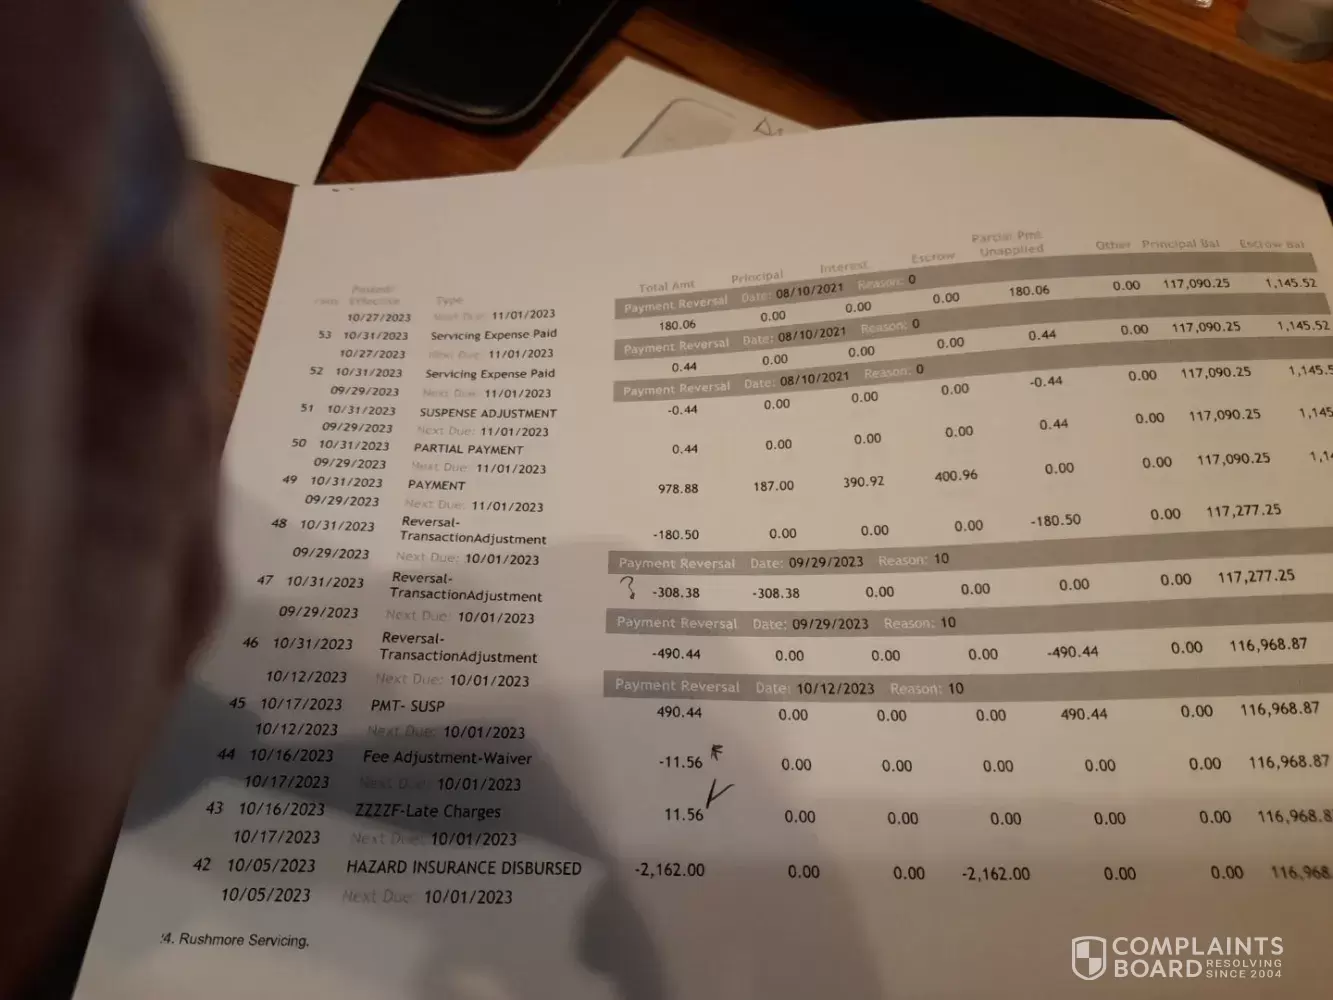
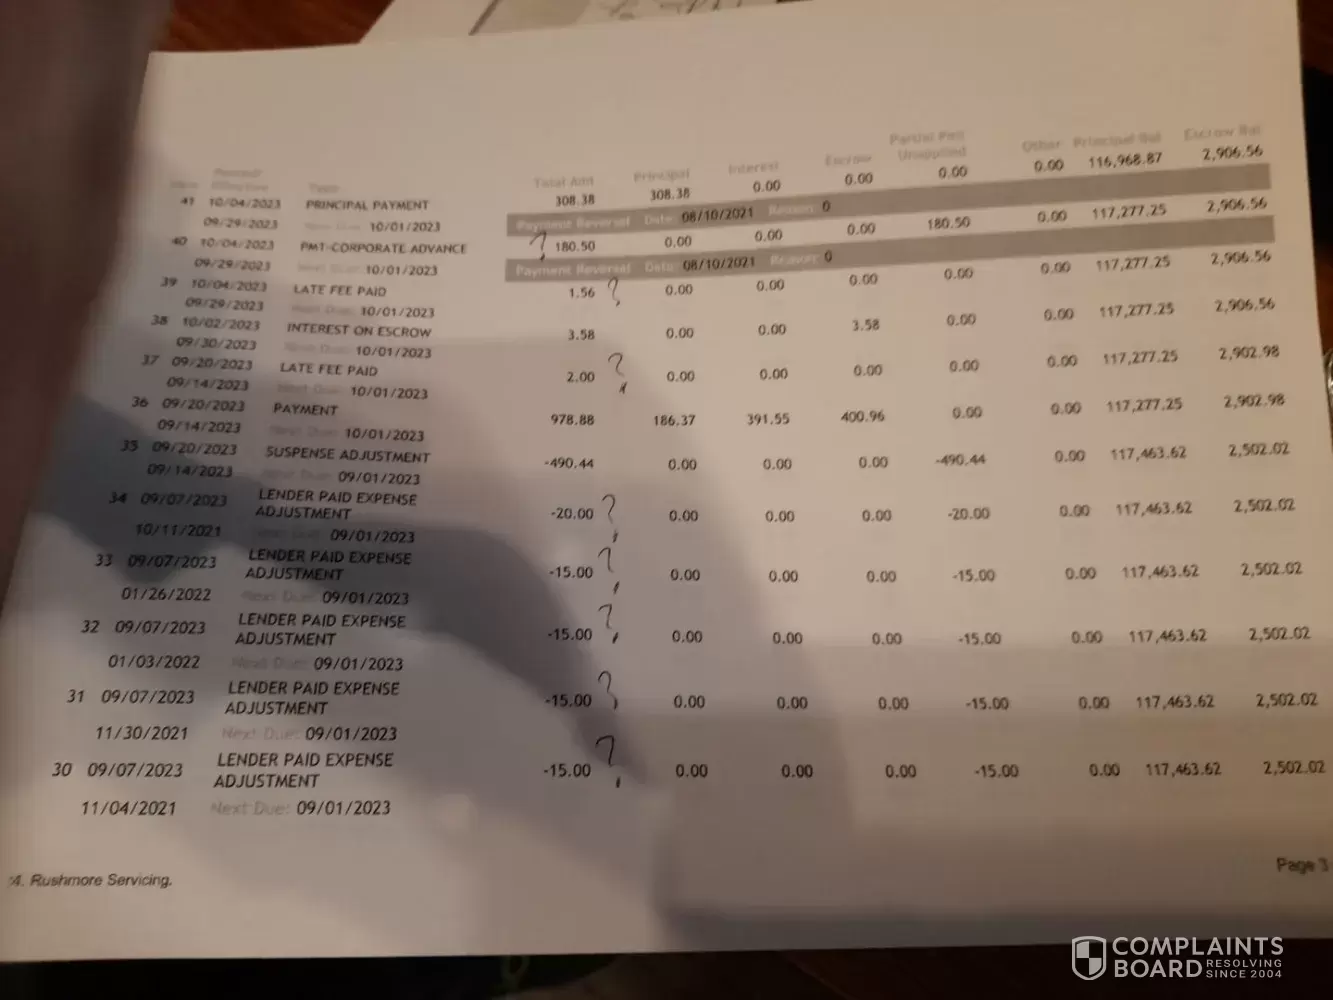
I've spent more years than I care to count helping people navigate the mortgage servicing nightmare that is Rushmore Loan Management. If you're reading this because you're stuck in a dispute with them, you probably already know the drill. Slow responses, payment errors, insurance premiums that don't make sense, and the general feeling that nobody on the other end actually gives a damn about your situation. Let me give it to you straight. First off, let's talk about what actually happens when you try to file a complaint. You pick up the phone, wait on hold for forty-five minutes, and then some guy named "David" tells you he's going to look into it and get back to you in three to five business days. That's year one. By year three, they'll tell you seven to ten business days. Nobody ever calls back in that window. I learned this the hard way back in 2019 when I was trying to get a simple escrow adjustment corrected for one of my clients. The system showed a $200 error that had been compounding monthly for two years. David was the third person I talked to that week. It took me eight months and four separate escalation forms to get it fixed. Here's the thing most people miss when dealing with Rushmore Loan Management Complaints — they treat it like a normal customer service issue. It's not. Mortgage servicing companies operate on a completely different timeline than retail businesses. When you call a cell phone company, they can usually resolve things in real-time. With Rushmore, the backend systems are aging, the staff turnover is high, and the compliance infrastructure is designed to make individual complaints drag until you give up. It's not personal malice. It's institutional inertia.
The first move you need to make is stopping the verbal dance. Every conversation you have on the phone needs a paper trail. I send everything via certified mail with return receipt requested, even when they have an online portal. Their portal logs disappear into some digital black hole that doesn't count toward any regulatory deadline. Certified mail creates a legal timestamp that actually matters if this goes to the CFPB or your state's attorney general office. Now, let's talk about the actual process. There are three tracks you can take simultaneously, and honestly, this is where most people screw up because they pick one and wait. Don't wait. File your complaint directly with Rushmore's compliance department at the same time you're submitting it to the Consumer Financial Protection Bureau, and at the same time you're notifying your state's attorney general. Three separate channels create three separate tracking numbers, and eventually one of them is going to produce a human response. I've seen cases resolve in as little as two weeks when the CFPB reference number appears on the complaint letter Rushmore eventually sends you. The CFPB complaint process is free and takes about fifteen minutes. You fill out the form online, get a case number, and Rushmore gets notified within three business days. Here's the counter-intuitive part — most people think the CFPB "investigates" their complaint. They don't. The CFPB just forwards it and watches Rushmore respond. But that response matters. Rushmore takes CFPB complaints seriously because they count toward their regulatory standing. I've had people who received written responses from Rushmore within four business days after filing through the CFPB portal, whereas their direct phone calls went unanswered for weeks.
State-level complaints vary, but North Dakota is Rushmore's home jurisdiction, so filing with the North Dakota Attorney General's office carries extra weight. I've also found that filing with your own state's attorney general creates additional pressure, especially if you're in a state with active mortgage servicing enforcement units. States like California, New York, and Maryland have dedicated divisions for this kind of thing. Let me share a specific edge case I ran into last year. A client of mine had a complaint about a forced-placed insurance charge that Rushmore refused to remove. The weird part was that the insurance policy was paid and active, but Rushmore's system showed a lapse. Standard procedure would be to keep calling and email after email. Instead, I pulled the original servicing transfer documents and found that Rushmore had acquired this loan through a portfolio purchase from another servicer. The insurance data didn't transfer over correctly. The workaround was requesting a full servicer transition audit under Reg CC and the SAFE Act requirements. That triggered a review that found seven other discrepancies in the same account. We got the insurance charge removed and a $400 credit for the entire mess. Here's another nuance people don't understand. There's a difference between a complaint and a qualified written request under RESPA. If you're disputing the accuracy of information on your account — things like payment history, escrow balances, fee charges — you can send a qualified written request. This creates a legal obligation for Rushmore to acknowledge receipt within five business days and resolve the dispute within thirty days, or explain why they can't. Regular complaints have no such deadline. Qualified written requests do. I use these almost exclusively now because they force a response timeline into existence.
Get the Full Details
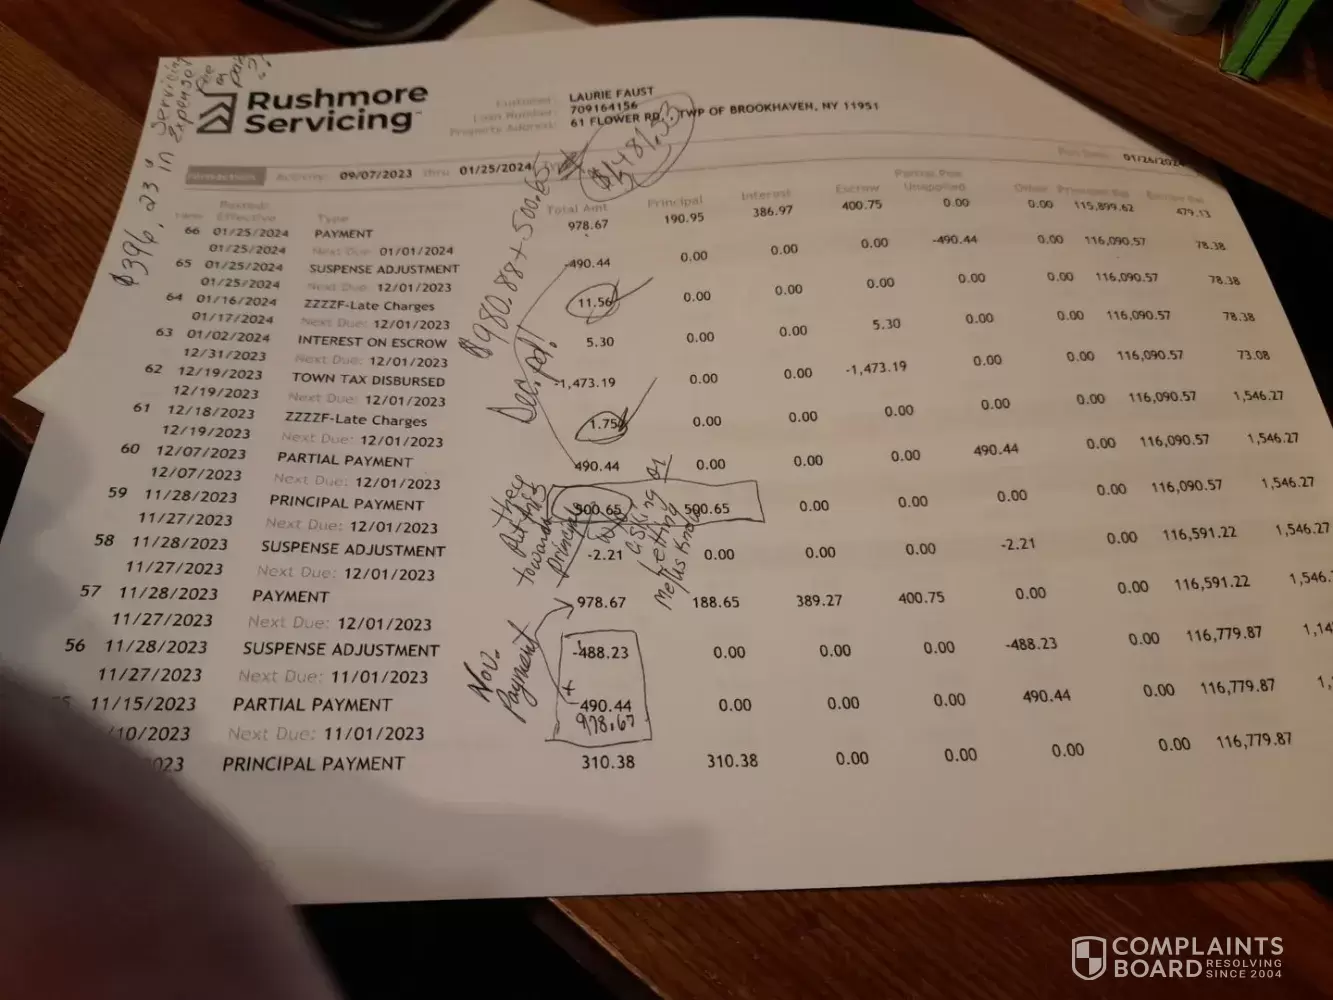
The downside of this approach is that QWRs require a specific format and mailing address. You need to send it to the address listed in your periodic statements, not the main customer service line. Rushmore's QWR processing center appears to be in a different location than their general complaints department. Send it to the wrong place and you'll get a generic acknowledgment that doesn't trigger the regulatory clock. I keep a running list of current addresses for each major servicer. They change occasionally, usually when companies consolidate their operations. If your issue involves a loan modification or repayment plan, that's a separate track entirely. Rushmore has specific hardship programs and modification options, but they also have internal approval thresholds that most complaint processes don't address. A complaint about an error and a request for a modification are different animals. I always separate these. If someone has both a billing error and needs a modification, I file the QWR for the error and the modification application independently. Combining them tends to slow everything down because the servicing team has to route the modified request through additional approval layers. There's also the matter of documentation. When you're dealing with Rushmore Loan Management Complaints, your evidence needs to be organized chronologically and labeled clearly. I recommend a simple spreadsheet with dates, contact names, reference numbers, and summaries of each interaction. Take screenshots of any online communications. Save copies of all letters. This sounds obvious but most people don't do it until they're three months into a dispute and realize they can't remember what was promised on a phone call in January.
One final piece of practical advice that isn't really about the complaints themselves but about managing the process. Set up a dedicated email address for all correspondence with Rushmore. Using your personal email means these messages get buried under regular mail. A dedicated address lets you search, reference, and export your entire communication history in one place. I've had situations where a single email thread spanning six months contained the exact language I needed to prove a promise that was never honored. The whole process is tedious and frankly exhausting. But it's manageable if you treat it systematically instead of emotionally. The people on the other end are processing hundreds of complaints a day. Being the one with a clear paper trail, a regulatory reference number, and a chronologically organized file is how you cut through the noise. Not by being louder or more dramatic, but by being the one who followed every procedure exactly right.