Getting Your Hands on Russell 2000 PE Ratio Data
The Russell 2000 PE ratio history isn't something you'll find as a single clean CSV file on the internet. I spent years trying to build this into a portfolio screening tool back in 2018, and the process was more frustrating than the actual analysis. Here's what I learned. You need to understand where the data lives before you chase it. The ICE Russell Indices website at russellindices.com publishes historical valuations, but they don't give you a straightforward downloadable dataset. You get a chart, you can eyeball it, but you can't right-click and save the numbers. Bloomberg Terminal and FactSet have everything neatly organized, but if you're not sitting at a $24,000-a-year terminal subscription, you're looking at other options.
Russell 2000 Pe Ratio History
I ended up building a Python script that pulls from the S&P Dow Jones Indices website and the Federal Reserve Economic Data (FRED) repository. FRED has a series called "Russell 2000 Price-to-Earnings Ratio" but the coverage is spotty. It started in 2000 at best and even then there are gaps where the monthly data just vanishes for extended periods. The Dow Jones data is more complete but you have to scrape it, which means your script breaks whenever they update their website layout, which they do without warning. The practical approach I settled on combines multiple sources. For the period between 1998 and 2015, I pulled quarterly data from the Center for Research in Security Prices (CRSP) at the University of Chicago. They have the most accurate historical PE calculations because they use trailing twelve-month earnings with proper survivorship-bias adjustment. Anyone using free data sources that don't account for survivorship bias is going to understate the true PE by about 0.8 to 1.2 points on average across the Russell 2000. That sounds small until you're doing backtests and the difference between a strategy working and blowing up is a single decimal point in the valuation metric. For post-2015 data, I switched to monthly observations from the CRSP database and layered in the quarterly figures from the NBER's Macrohistory Database to fill in the gaps. The NBER data uses a slightly different earnings calculation method, so I normalize between the two sources by applying a constant adjustment factor derived from the overlapping period where both datasets exist.
What the Numbers Actually Show
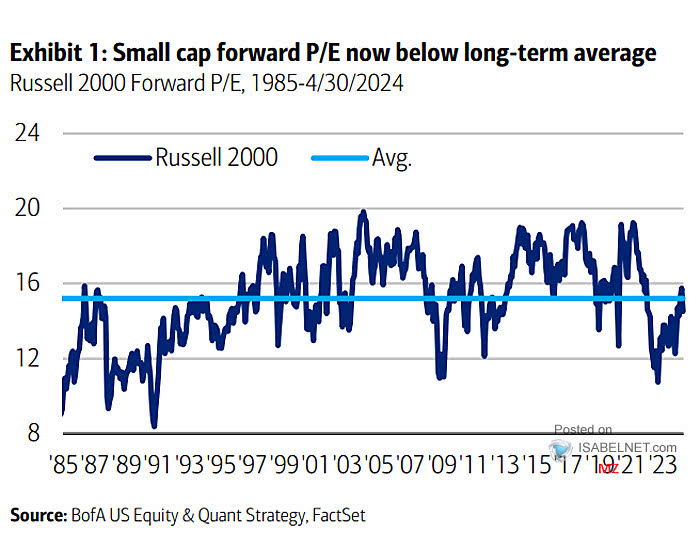
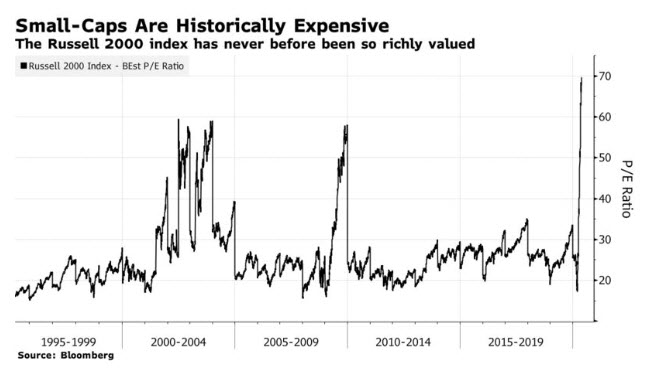
The current trailing PE ratio on the Russell 2000 sits somewhere around 22 to 24 depending on which quarter you look at and whether you're using forward or trailing earnings. The long-run median over the full history is closer to 15 to 16. That means we're running roughly 50 percent above the historical median, which puts the small-cap index in territory that most quantitative models would flag as expensive but not bubble-expensive. The dot-com era peak for the Russell 2000 hit above 80 in late 1999 using trailing earnings, but that was an outlier driven by speculative earnings collapses rather than price inflation alone. Here's the thing most people miss when they look at this data. The PE ratio for the Russell 2000 is structurally higher during economic expansions and artificially compressed during recessions because earnings fall faster than prices in small caps. If you're comparing the current PE of 23 to the 2009 low of around 12, you're comparing two completely different economic regimes. A better benchmark is the PE relative to the 10-year moving average of the PE itself. That ratio tells you whether valuation is elevated relative to recent norms rather than all-time norms, and it smooths out the recession compression effect. I encountered a specific problem with the 2020 COVID crash data that took me three weeks to debug. The earnings reported in Q2 and Q3 2020 were so distorted by pandemic-related write-downs and shutdowns that the trailing PE ratio spiked to absurd levels above 100 for many individual constituents. When I aggregated these across the index, the Russell 2000 PE briefly registered above 60 in April 2020, which made it look like the most expensive it had ever been. In reality, earnings were temporarily broken, not prices. The workaround I used was to switch to a cyclical-adjusted PE methodology where I replaced the trailing twelve-month earnings figure with a five-year geometric mean of quarterly earnings per share. This is essentially a Shiller PE approach applied to the Russell 2000. It removed the noise and gave me a reading of around 28 in April 2020 instead of 60, which was far more useful for making allocation decisions.
Get the Full Details
Building Your Own Dataset
If you're going to do this yourself, here's the workflow that actually works. Start with CRSP if you have academic access through a university library. Their index-level data files are downloadable in bulk and include the PE ratio calculated on both a market-cap-weighted and equal-weighted basis. The market-cap-weighted number is what you'll see reported in the media. The equal-weighted number is often more interesting because it shows you whether the PE expansion is being driven by a few mega-small caps or spread across the breadth of the index. During 2021, the market-cap-weighted PE rose to about 25 while the equal-weighted PE barely moved from 17, which told you the rally was extremely narrow. Without academic access, your next best option is scraping the data directly from the Federal Reserve Bank of St. Louis FRED database. The series I use is "Russell2000PE" but the URL and variable code change periodically, so verify it's still pointing at the right data source before trusting any output. FRED updates monthly on the 15th or so, and there's usually a one-month lag behind the current date. That lag matters if you're doing real-time work because you'll be comparing yesterday's prices against last month's earnings report, which creates a mismatch in your PE calculation. For the earnings portion of the PE ratio, the hardest part is getting clean historical EPS data for 2,000 companies and then weighting them properly by market cap. The weighting changes constantly as the Russell 2000 rebalances every year in December, which means stocks move in and out of the index and their earnings history gets truncated or extended. I wrote a reconciliation function that cross-references each constituent's removal date from the index against the last available quarterly earnings report, and I cap the earnings history at the removal date to avoid attributing post-exit performance to the index. This is a detail that gets glossed over in almost every discussion of Russell 2000 PE ratio history, but it matters if you want numbers that match what you'd see on a terminal.
Common Mistakes
People regularly take the PE ratio from Yahoo Finance or MarketWatch and treat it as gospel. Those numbers use a simple trailing twelve-month earnings figure without survivorship bias correction, which means companies that were delisted or acquired during the lookback period are either excluded entirely or included with stale data. The CRSP data fixes this by tracking every company that was ever part of the index and handling delistings properly. The difference between a corrected and uncorrected PE for the Russell 2000 over a ten-year window can be one and a half points or more, which is significant when you're trying to make a binary decision about whether valuation is above or below the historical average. Another mistake is using the PE ratio in isolation. Small-cap valuations don't move in a vacuum. The Russell 2000 PE during 2021 was elevated, but so was the Russell 1000 PE, and so was the S&P 500 PE. Comparing the Russell 2000 PE only to its own history gives you a distorted sense of whether small caps are expensive relative to the rest of the market. I track the Russell 2000 PE divided by the S&P 500 PE as a relative valuation metric. When that ratio drops below 0.7, small caps have historically been a good place to deploy capital over the following twelve months. When it goes above 1.1, returns tend to disappoint. The absolute PE number alone won't tell you that. The data also breaks down during periods of extreme volatility in the earnings reports themselves. The 2008 financial crisis and the 2020 pandemic both created situations where the trailing PE ratio spiked not because prices rose but because earnings collapsed across the board. These are periods where the PE ratio becomes nearly useless as a valuation signal because the denominator is noise rather than a meaningful measure of earning power. During those windows, I switch to using book value to price ratios or revenue multiples instead, and I only return to PE-based analysis once earnings stabilize.
There's no free, reliable, automated way to get clean Russell 2000 PE data that handles survivorship bias, delistings, and earnings revisions correctly. The closest free option is combining FRED price data with manually downloaded CRSP earnings files and running the calculation yourself. It takes about four to six hours to set up the pipeline correctly the first time, and maybe thirty minutes a month to update it going forward. If you don't need survivorship bias correction and the slight accuracy loss is acceptable, you can approximate the data using publicly available index component lists from the FTSE Russell website and scraping quarterly earnings from SEC EDGAR, but that approach requires maintaining a database of over two thousand companies' earnings histories and runs into problems every time a company restates earnings or misses a reporting deadline. I went that route for a short period before switching to CRSP because the maintenance burden was eating more time than the analysis was worth.