Starting an Rv And Boat Storage Business Isn't What People Think
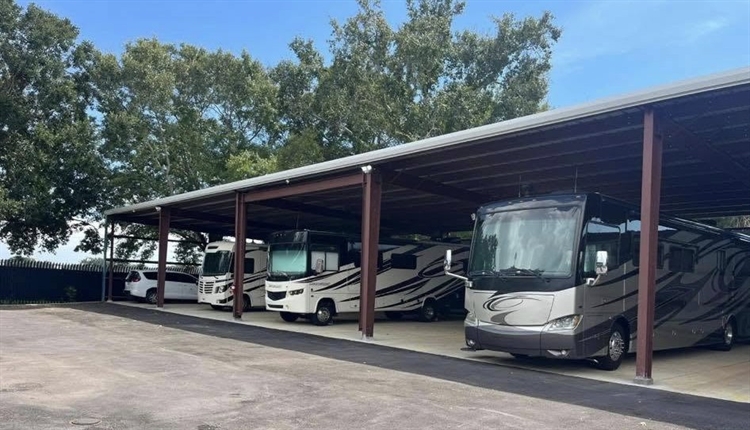
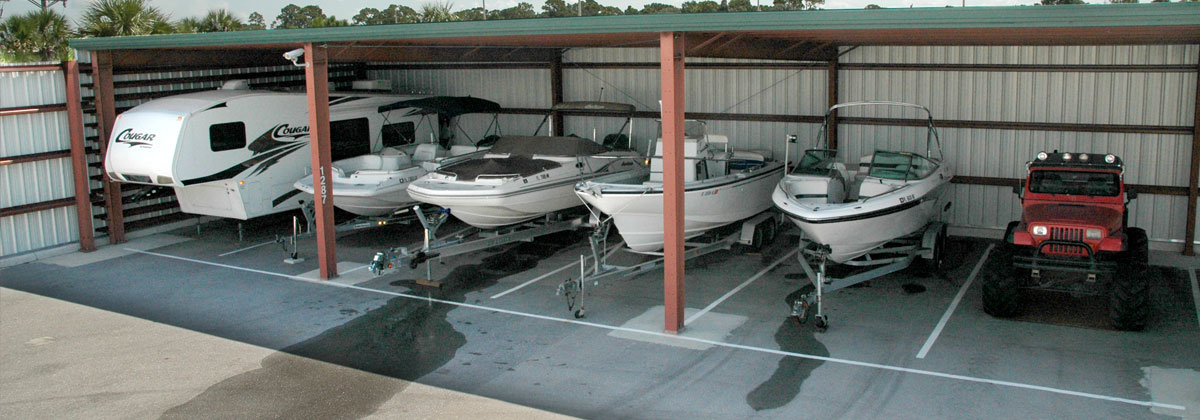
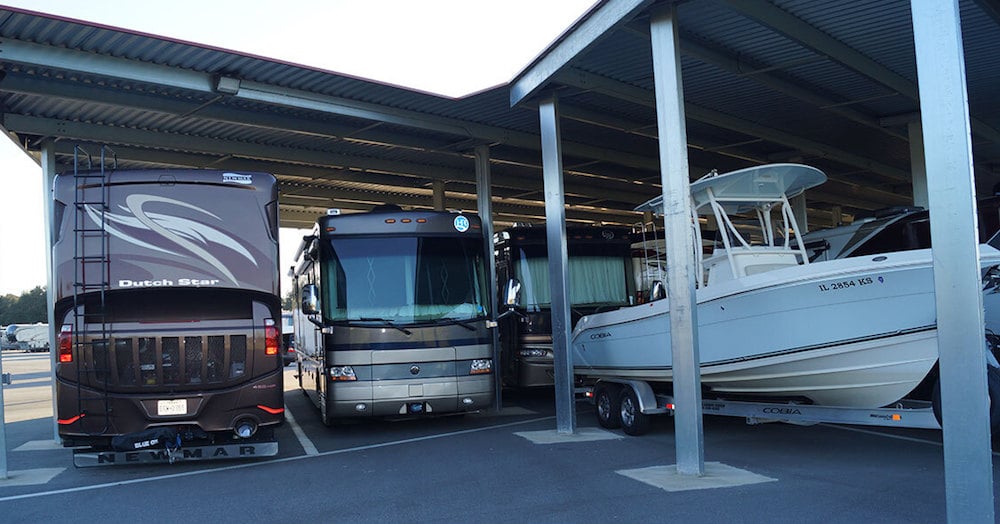
Most people picture it as setting up a fence, pouring some concrete, and collecting monthly checks. The reality is more complicated and involves zoning battles, insurance nightmares, and a lot of time spent figuring out why a customer's 45-foot motorhome won't fit between two other vehicles the way the floor plan promised it would. I've been running a facility that handles both rv and boat storage for roughly eight years. We started with about twelve spaces on a quarter-acre parcel and now sit at around sixty covered units and forty open stalls. The business model is straightforward on paper, which is exactly why people keep trying it and failing within eighteen months. Let me walk through what actually happens when you try to make this work.
Understanding the Rv And Boat Storage Business Model
Revenue generation here is deceptively simple. You lease square footage to people who own vehicles they use seasonally or infrequently. The standard pricing structure runs between $75 and $300 per month for open air storage depending on your region and unit size. Covered storage typically commands $125 to $450 monthly. Indoor climate-controlled environments push into the $300 to $800 range but require significantly higher capital investment upfront. The counter-intuitive part most operators miss is that your actual profit margin depends almost entirely on space utilization rates rather than pricing power. I learned this the hard way after spending $18,000 on a digital sign at the road frontage. Traffic went up about twelve percent for the first two months, then returned to baseline. What actually moved the needle was rearranging my layout to convert four oversized open spaces into three covered bays that rented out faster and at higher rates. That single change added roughly $1,200 in monthly recurring revenue with zero additional marketing spend. The zoning landscape for this business is brutal in most counties. You need commercial or industrial zoned land, not agricultural or residential. Even then, many jurisdictions treat rv and boat storage differently from standard self-storage. Some classify it as a vehicle impound lot. Others have minimum acreage requirements that effectively eliminate suburban options. Before you sign a lease or buy land, call the planning department and ask specifically about recreational vehicle storage use. Get the answer in writing because verbal assurances mean nothing when a neighbor complains.
The Physical Setup That Actually Works
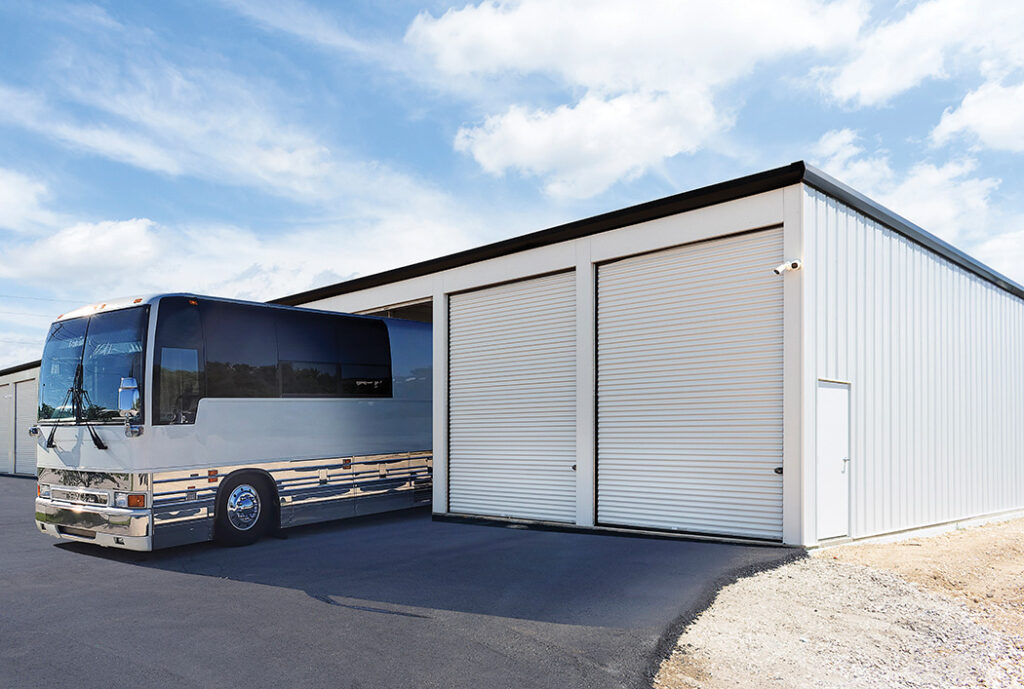
Your site design determines everything after day one. I see too many operators lay out spaces like a parking lot and then spend years trying to fix the problems that create. The critical measurement most people skip is turn radius clearance. A 40-foot fifth wheel trailer needs roughly 60 feet of maneuvering room to enter and exit a space without hitting adjacent units. If your aisles are under 20 feet wide, you're going to have fender benders monthly. I once had a customer back into a space that measured exactly to spec on paper. The problem was the approach angle. The entrance dip was four inches and combined with the trailer's low ground clearance at the tongue, he backed in, got high-centered on the lip, and tore his landing gear loose. Solving that required grading the approach area and adding a gravel ramp, which cost about $600 in materials and a weekend of equipment rental. Drainage is another area where beginners lose money. Water pooling around stored boats and rv's causes hull degradation, tire flat spots, and customer complaints that escalate quickly. I recommend a minimum cross-slope of two percent across all driving and parking surfaces. French drains along the perimeter and catch basins at low points handle the rest. One facility I consulted for had chronic flooding during spring rains because the grading sloped toward the building instead of away. Fixing it required regrading approximately 2,000 square feet of pad and redirecting downspouts, which ran about $4,500 total. Prevention through proper site grading during initial construction costs maybe 15 percent of that amount.
Get the Full Details
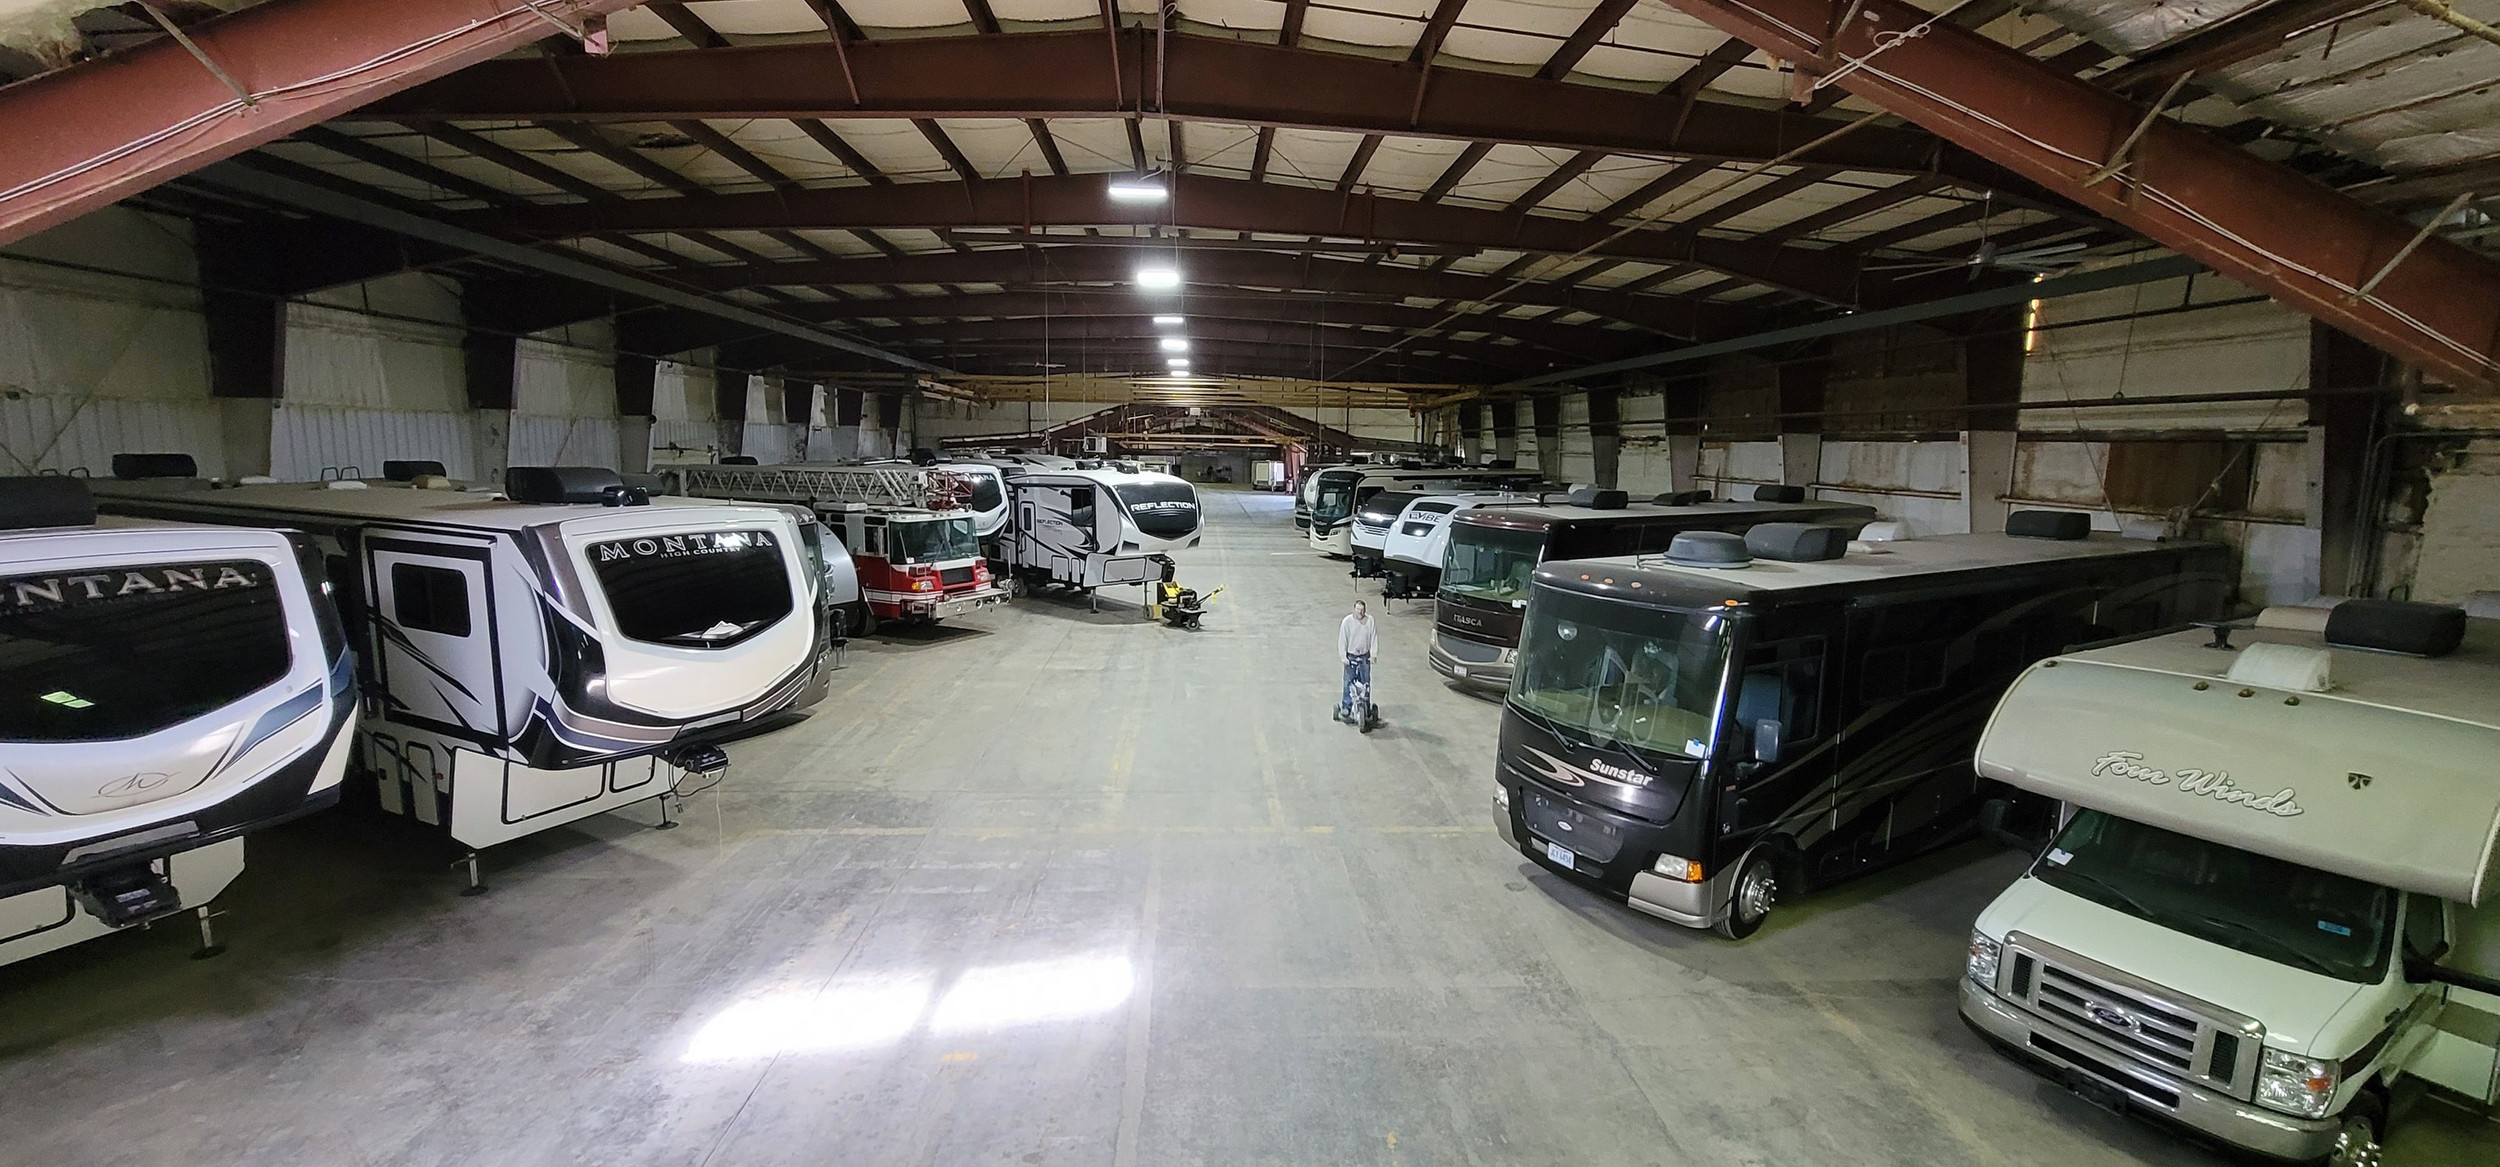
Lighting deserves its own consideration. Security cameras are table stakes but inadequate alone. Motion-activated LED floodlights spaced at 50-foot intervals along aisles make a visible difference in incident reports. My current facility uses a combination of fixed camera poles at entry and exit points plus pan-tilt-zoom units covering the interior. The initial installation ran roughly $3,200 including wiring and a 16-channel DVR. Monthly cloud storage fees add about $45. The insurance premium reduction from having a monitored system typically covers the monthly cost within the first year.
Insurance and Liability Considerations
This is where the business model gets expensive fast. Standard commercial property insurance doesn't cover vehicles stored on your lot. You need a specialized inland marine policy or a self-storage floater that explicitly covers rv and boat storage. Liability exposure is real and frequently underestimated. A boat that comes loose during a wind event can damage multiple units. An rv whose stabilizer jack sinks through unstable ground can tip over. I had a situation last spring where a gust front hit the facility at about 55 mph. One customer's 35-foot travel trailer wasn't properly secured because the previous month's inspection had missed a cracked wheel chock. The trailer shifted, clipped two others, and caused approximately $8,000 in combined damage across three units. My insurance covered most of it after a lengthy claims process, but the deductible was $5,000 and my premiums increased by 22 percent the following year. The workaround I use now is a mandatory pre-storage inspection checklist that gets signed by both the operator and the customer before any unit is assigned. It documents the condition of wheel chocks, tie-down points, and any pre-existing damage on the vehicle. This documentation has protected me in two disputed claims already. The process takes about seven minutes per vehicle and eliminates the "I didn't know it was already damaged" conversation.
Operational Realities and Hidden Costs
Monthly recurring costs for a medium-sized facility typically include: property taxes on commercial land, which run 1 to 3 percent of assessed value annually depending on your county; liability and property insurance around $2,400 to $6,000 yearly; software subscriptions for access control and billing at $150 to $400 monthly; maintenance equipment like mowing, graffiti removal, and pavement sealing at roughly $3,000 to $8,000 yearly; and security system monitoring at $45 to $150 monthly. Staffing depends on scale. A facility under thirty units can often be managed part-time with remote access controls. Between thirty and sixty units typically requires one on-site manager working weekday hours. Beyond sixty units and you're looking at additional coverage for evenings and weekends. I run my sixty-space facility with two part-time staff members covering different shifts plus myself handling maintenance and administrative work on an as-needed basis. Total labor cost comes to approximately $52,000 annually including payroll taxes and benefits. Payment processing is another overlooked detail. Most customers pay through automated billing systems. Credit card processing fees run between 2.5 and 3.5 percent of revenue. On $120,000 in annual storage income, that's $3,000 to $4,200 going to payment processors every year. Some operators absorb this cost into their pricing. Others charge a small transaction fee that customers resent. The honest assessment is that it's a cost of doing business and factor it into your per-unit pricing from the start.

Common Pitfalls That Kill New Facilities
The number one reason new rv and boat storage businesses fail is underestimating the time between initial investment and reaching break-even occupancy. Most people budget for six months of occupancy growth. The realistic timeline in most markets is nine to fourteen months. If you're carrying debt on land acquisition and construction during that period without sufficient cash reserves, you're in dangerous territory. A second pitfall involves oversizing your initial buildout. I watched a competitor in the next county over commit to forty covered units on day one because the architecture looked impressive in a brochure. He only filled twelve units in the first eighteen months and spent $200,000 more than necessary on construction. A phased approach where you build in stages tied to actual demand is almost always the better path. Start with open air spaces, gauge demand, then add covered units as revenue supports the investment. Customer acquisition cost is another metric operators ignore. Digital advertising through Google and Facebook typically runs $25 to $60 per qualified lead in the self-storage space. Conversion rates from inquiry to lease average between 30 and 45 percent. That puts your actual cost per acquired customer at roughly $60 to $180. Factor that into your first-month revenue calculation because paying $150 to acquire a customer who pays $150 in their first month means you're starting nearly break-even on that relationship.
What Actually Drives Profit
After eight years in this business, the patterns are clear. Occupancy rates above 85 percent are where profitability accelerates because fixed costs are already covered. The difference between 70 percent and 90 percent occupancy on a sixty-unit facility can mean $14,400 to $28,800 in additional annual revenue with minimal incremental cost. That's why marketing and customer retention matter more than anything else in the early years. Retention is where most operators drop the ball. A customer who stays eighteen months is worth significantly more than one who leaves after six. Move-out fees, unit turnover cleaning, and re-marketing costs eat into margins. My approach has been to implement a simple loyalty discount structure: five percent off after twelve months, ten percent after twenty-four months. The lost revenue per customer is minor compared to the acquisition cost of replacing them. It also reduces turnover-driven vacancy periods that kill cash flow. The secondary revenue stream that most people overlook is vehicle maintenance services. Offering oil changes, battery testing, tire inflation, and winterization for stored rv's and boats adds $8,000 to $25,000 annually depending on facility size and local demand. I partner with a mobile mechanic who comes in biweekly. He takes a 20 percent commission on labor and keeps the parts markup. The arrangement requires no additional staff, no shop space, and generates revenue from customers who are already paying to store their vehicles.
Access control technology has improved significantly in the last few years. Smartphone-based entry systems eliminate the need for physical keypads and plastic fobs that break or get lost. The upfront cost is higher but the long-term savings on replacement hardware and reduced support calls justify it. My current system runs about $1,800 for a sixty-unit facility including gates, readers, and controller hardware. Monthly cellular connectivity for remote monitoring adds $80. Seasonality affects this business more than most operators expect. In northern climates, occupancy typically drops 15 to 25 percent between November and March as seasonal rv owners store their units elsewhere or sell them. Boat storage follows a similar pattern with spring pickups creating congestion and fall turn-ins creating empty spaces. Planning your cash flow around these cycles prevents the panic when March rent checks are smaller than February's.
Getting Started Practically
If you're serious about this, start by studying your local zoning code and visiting three competing facilities. Talk to their operators during off-peak hours. Ask about their worst operational headaches and what they'd do differently. Most will be candid because they assume you're months away from being a threat. That assumption gives you useful information while you still have time to adjust your plan. Run the numbers conservatively. Assume it takes fourteen months to reach 70 percent occupancy. Assume your first-year insurance premium is 20 percent higher than quote estimates because you're a new operator. Assume one major incident in your first two years that triggers a deductible and a premium increase. If the business works under those assumptions, it's viable. If it doesn't, you've saved yourself a costly mistake. The rv and boat storage business is a real operation with real margins, real headaches, and real upside. It's not passive income. It's a property management business that happens to store recreational vehicles. Treat it like one and you'll do fine. Treat it like a check-writing opportunity and you'll learn why most facilities flip ownership within five years.