How RV financing actually works when you sit down to calculate payments
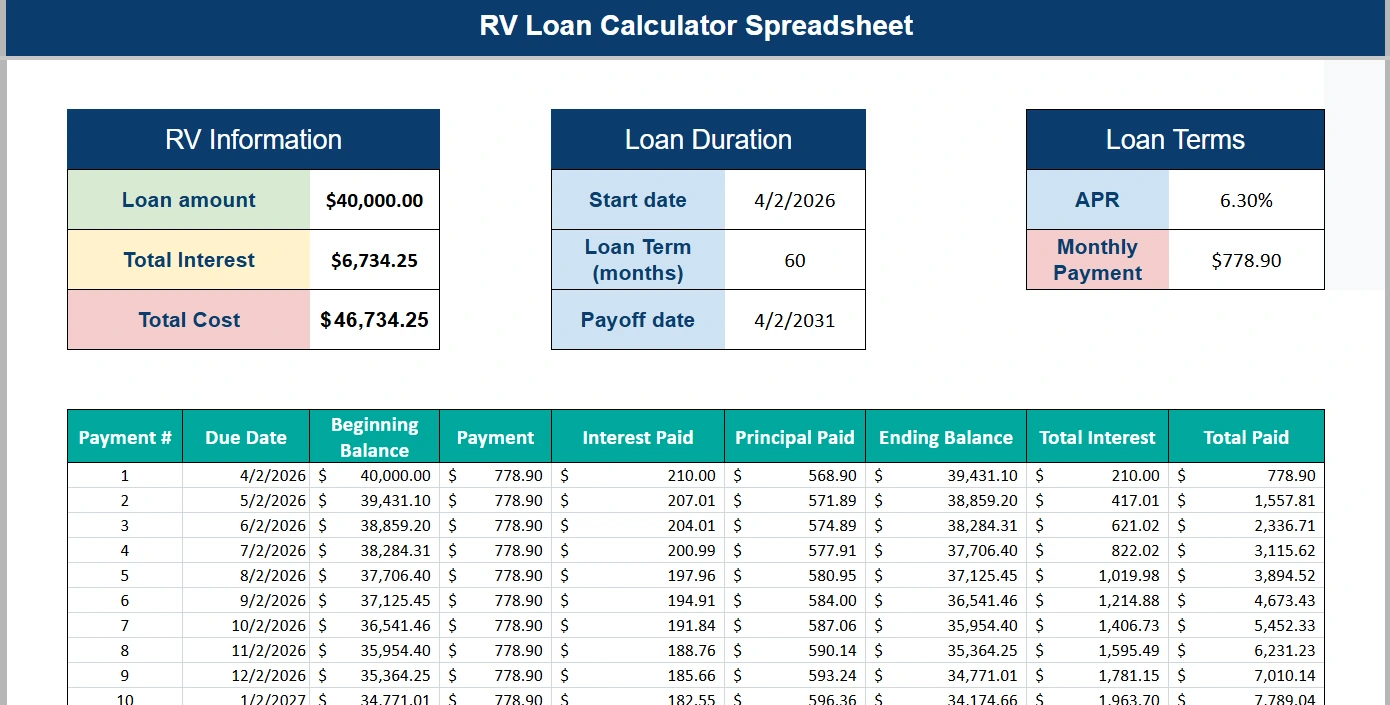
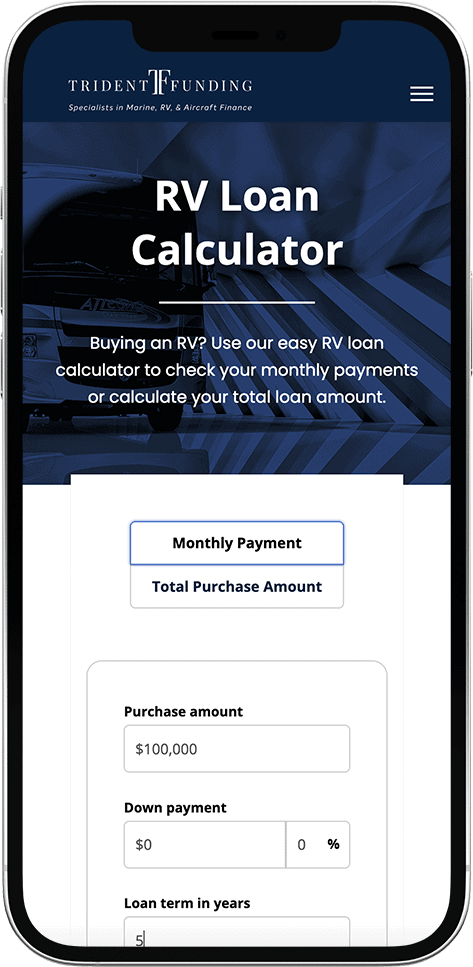
The numbers most people see online are slightly wrong because they ignore a few variables that lenders actually care about. An RV financing calculator will show your monthly payment based on price, down payment, rate, and term. That part is fine. The problem starts when you try to make that output match what you'd actually get approved for. I spent three years working loan files and ran into this constantly. Here is how to use one without getting fooled by the output.
Using a Rv Financing Calculator correctly
Start with the right inputs. The standard fields are purchase price, down payment, interest rate, loan term, and sales tax. Most calculators assume sales tax gets rolled into the financed amount. That changes your monthly number more than people expect. If you pay tax upfront instead of financing it, your payment drops by roughly 8 to 14 dollars per thousand borrowed. Enter your actual credit score range before you enter anything else. The rate you put in matters more than the term length. A bad rate assumption will wreck your budget faster than a longer term ever could. I have seen people pick a 72-month loan at 9 percent and think it was a deal because the payment looked manageable. The total interest paid over that term was nearly as much as the down payment they skipped. Always run the calculator twice. Once with the tax financed and once without. The difference tells you whether rolling tax into the loan is worth it for your situation. In most cases it is not, unless you are short on cash right now and need to preserve liquidity.
What the calculator does not tell you
Lenders do not finance the full sticker price. The loan-to-value ratio is usually capped at 100 to 110 percent for new RVs and 85 to 95 percent for used units. If the calculator says you can finance $60,000, the actual approval might be $52,000 depending on the RV age and mileage. The tool has no way of knowing this unless you build it into your input. Pre-approval rates are almost always lower than dealer-arranged rates. This is not always true, but it happens enough that you should assume it applies until the lender proves otherwise. Online lenders are competitive. Dealerships bundle profit into the rate sometimes. A 0.5 to 1 point difference sounds small but it adds $40 to $90 a month on a typical RV loan. There is also the issue of rate locks. Most calculators do not account for the window between when you find the rate and when the loan closes. Rates move daily. If you get a quote in January and close in March, that number is gone. Budget for a rate shift of up to 0.75 points unless you have a written lock agreement.
Get the Full Details
A specific problem I ran into
There is a common edge case with fifth wheels and travel trailers where the calculator breaks. These rigs often have higher GVWR ratings, which pushes them into commercial loan territory for some lenders. The rates are worse and the terms are shorter. I had a client who found a great deal on a used 35-foot fifth wheel. The online calculator gave him a clean monthly number at 6.5 percent over 120 months. When we actually applied, the lender classified it as a titled commercial vehicle because of the weight rating. The rate jumped to 8.9 percent and the term dropped to 84 months. His payment went up by about $130 a month from what the calculator showed. The workaround was straightforward. I pulled the exact GVWR from the manufacturer specs before any application. We then pre-qualified with a lender who explicitly handled high-GVWR RVs as recreational use. That step alone took 20 minutes but saved him from a painful surprise at closing. Always verify the weight class before you fall in love with a calculated payment.
Counter-intuitive things that will save you money
Longer terms do not always mean higher total cost in the way people think. A 144-month loan at a lower rate can cost less in total interest than a 72-month loan at a higher rate. Lenders sometimes offer better rates on longer terms because they make more money overall on the interest. Check the actual rate before choosing the term length. The shortest term is not automatically the smartest choice. Points matter more than people realize. Paying one discount point upfront can drop your rate by 0.25 to 0.375 percent. On a $50,000 RV loan over 120 months, that point costs $500 but saves roughly $600 to $900 in total interest. The breakeven point is usually around month 18. If you plan to sell or refinance before then, skip the point. If you are keeping the rig for seven years, pay it.
When the calculator fails completely
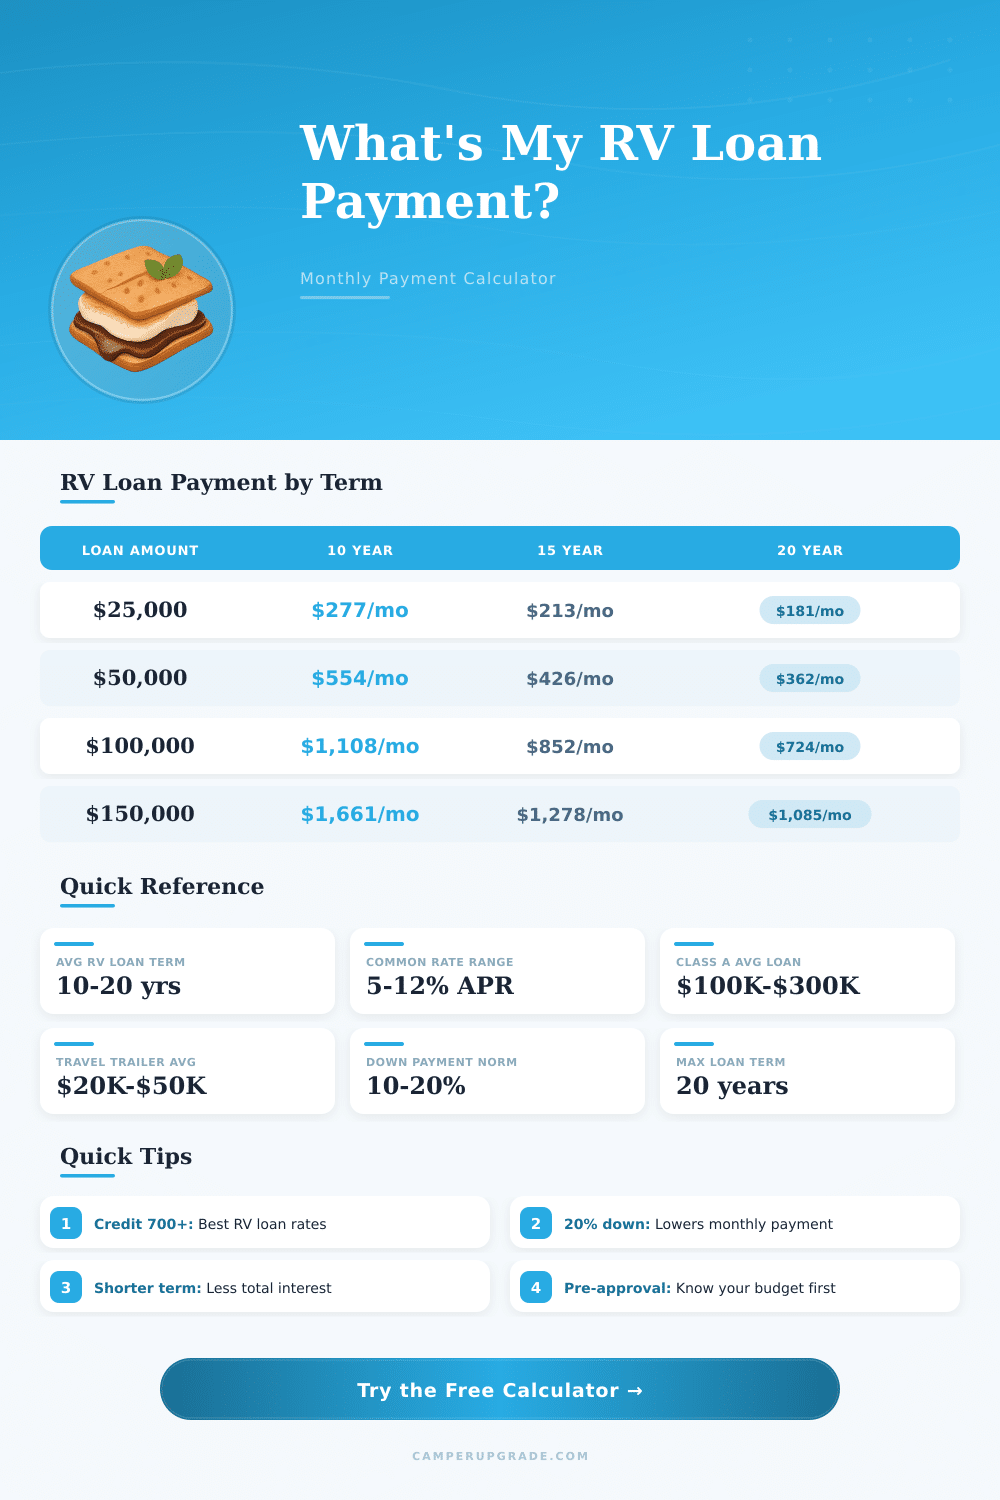
There are three scenarios where any RV financing calculator becomes unreliable. The first is when you are trading in an existing RV. Trade-in value variance can swing your financed amount by $3,000 to $8,000 depending on whether the dealer treats it as a transaction discount or a separate appraisal. The calculator cannot model this accurately. The second scenario is manufactured homes that sit on permanent foundations. Some lenders treat these as real estate rather than recreational vehicles. The financing terms are different, the rates are different, and the calculator you were using is showing you numbers for the wrong product type. The third scenario is loans above $75,000. Not all lenders offer programs for larger RV purchases. The available options narrow significantly and the rates become less predictable. A calculator will still give you an answer, but that answer may not correspond to anything any lender will actually offer you. In that range, talking to a specialist broker is faster than running numbers online.

If you need a reliable way to estimate your payment, pick a calculator that lets you adjust the loan-to-value cap and includes a field for trade-in value. Run the numbers with both the best-case and worst-case rate scenarios. The space between those two payments is your real budget range. Anything outside of it is not actionable.