Figuring out your monthly payment before you walk into a dealership
Most people use an Rv Loan Calculater to get a ballpark number so they don't walk into a dealership completely blind. That's a reasonable starting point, though the output is only as good as what you put into it. The basic formula isn't complicated: you take the loan amount, divide by the number of payments, then add the interest portion that comes from the rate and term. What most online calculators do under the hood is apply the amortization formula, which figures out how much of each payment goes toward principal versus interest at any given month. Early on, you're paying mostly interest. Towards the end, it flips.How to use an Rv Loan Calculater without messing it up
You need five inputs, and getting them right matters more than you'd expect. First, the total purchase price. Not your budget. The actual sticker price or negotiated price. Second, your down payment. Third, the interest rate. Fourth, the loan term in months. Fifth, any trade-in value you're factoring in. Most free calculators let you skip trade-in, but if you're actually doing this for a real purchase, leave that field blank only if you have nothing to trade. I spent years watching people plug in the wrong rate because they saw a advertised "starting at" number on a dealer's website and assumed it applied to them. Those teaser rates are usually for FICO scores above 740 with significant down payments and short terms. If you're bringing a older winnebago with 80,000 miles and you need 120 months, you're not getting that rate. Use the rate the lender actually quotes you after a soft pull, not the glossy number on the ad board.One thing almost nobody accounts for is the gap between the calculator's monthly payment and what you'll actually pay each month. The calculator gives you principal and interest. It doesn't include sales tax, documentation fees, dealer prep charges, or any add-ons like extended warranties or gap insurance that get rolled into the loan. I had a customer last year who calculated a $987 monthly payment and then showed up at the finance office to find his actual payment was $1,142. He'd forgotten that his state adds sales tax to the full purchase price and the dealer rolled it into the loan balance, which increased both the principal and the total interest paid over the life of the loan. That's a $155 per month difference that nobody warned him about. The workaround is simple but nobody does it. After you get your payment estimate from the calculator, add the sales tax for your state, any known fees, and whatever add-ons you're considering. Recalculate with that new loan amount. It takes about two minutes and it saves you from walking into the dealership with a number that's off by a thousand dollars or more.
What the calculators don't tell you
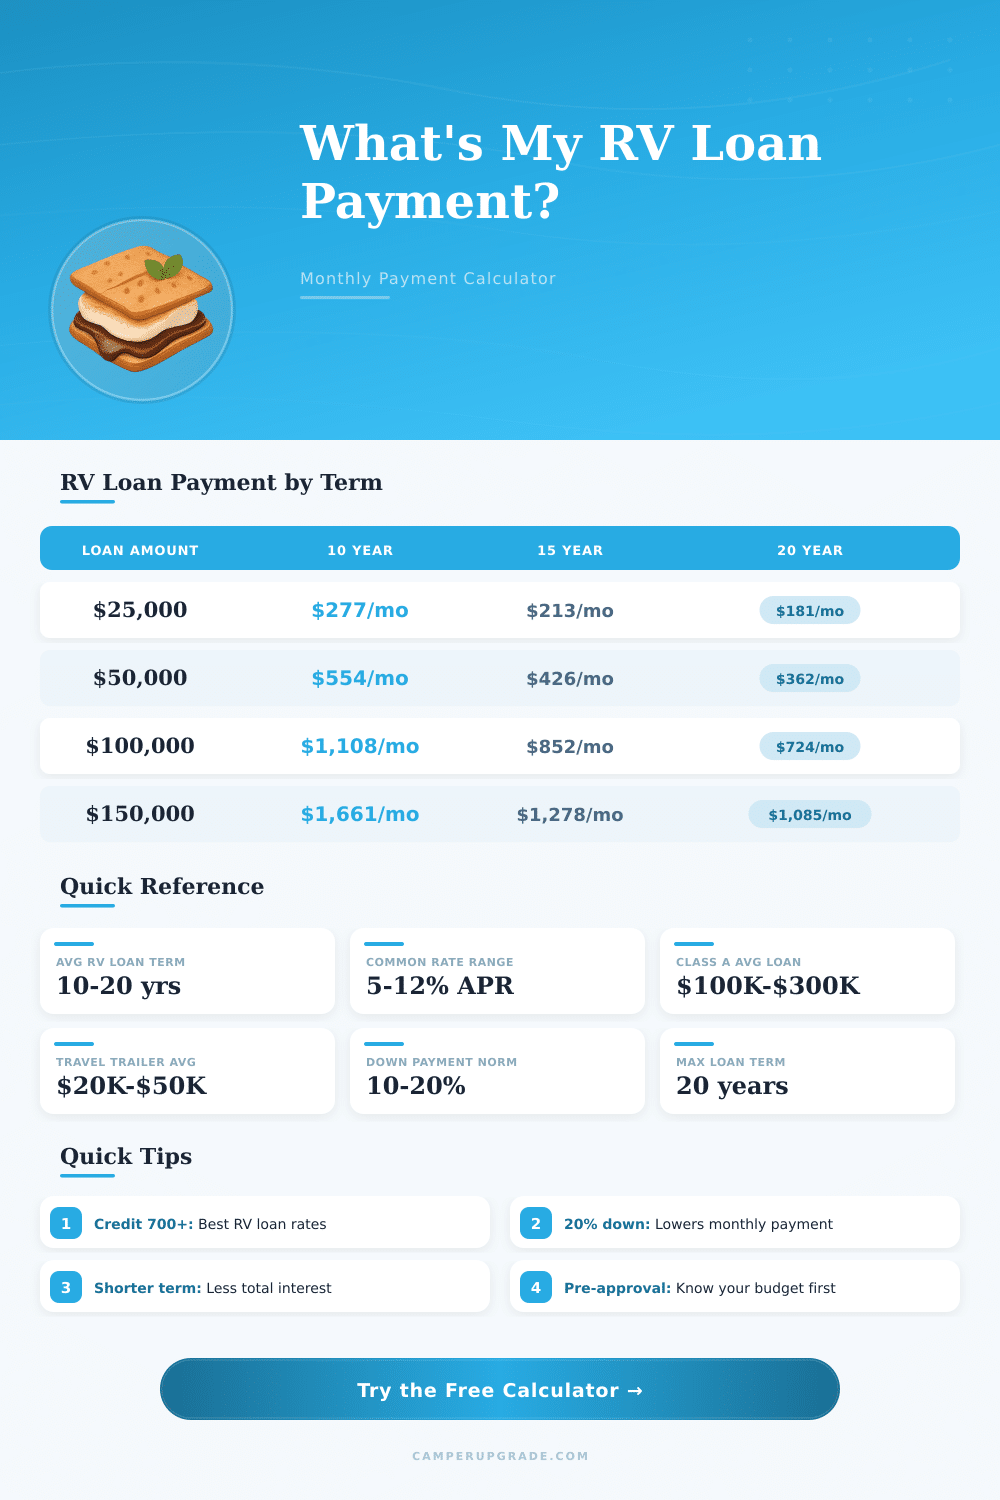
RV loans work differently than auto loans in ways that trip people up. A brand new Class A motorhome can cost anywhere from $150,000 to $400,000. Most lenders won't put you in a standard auto loan for that. You're looking at a recreational vehicle loan, which often means a higher rate, a larger down payment requirement, and a shorter maximum term. You'll rarely find a 72-month auto loan product for an RV. The most common terms are 120, 180, or 240 months, and the rate jumps noticeably the longer the term goes. Here's a counter-intuitive thing most people miss: a longer term doesn't just cost you more in total interest, it also changes how the lender values the collateral. RVs depreciate faster than trucks. A well-maintained Class C loses about 20% of its value in the first year and roughly 10% annually after that. With a 240-month loan, you will be deeply underwater for the first five to seven years. I've seen people try to refinance when their situation changed and get declined because the LTV was over 150%. The calculator will show you a payment, but it won't warn you that you're borrowing against an asset that's losing value faster than you're paying it down. Another thing worth knowing: some lenders treat a fifth wheel or travel trailer differently than a motorhome. If you own the rig outright and plan to park it, some lenders will classify it as personal property rather than a vehicle, which changes the lien process and sometimes the interest rate. If you're financing it, it's definitely collateral, but the classification can matter for insurance requirements and appraisal standards. Don't assume all RV loans are identical products.
Get the Full Details
When a Rv Loan Calculater gives you the wrong answer
Flat-rate loans exist, and they're common in the RV and boat lending space. A flat rate means the interest is calculated on the original loan amount for the entire term, not on the declining balance. If a lender quotes you a 7% flat rate on a $60,000 loan over five years, your total interest is $21,000 and your monthly payment is $1,350. A standard amortizing loan at 7% on the same numbers would cost you about $750 per month and $4,500 in total interest. The flat-rate payment is nearly double. Most online calculators assume amortizing loans, so if you're looking at a quote that uses flat-rate pricing, the calculator output will be wildly optimistic. I ran into this with a customer who was comparing two lenders. One gave him a monthly payment of $680 and the other $1,340. He assumed the cheaper one was the better deal until I pulled the actual loan agreement and found the first one was a flat-rate product disguised as a standard loan. The effective annual percentage rate on that flat-rate loan was closer to 13%. Always ask whether the rate is flat or amortizing before you trust the monthly payment number. It changes everything. Prepayment penalties are another hidden factor. Some RV loans charge a fee if you pay off the loan early or make extra principal payments within the first few years. A standard prepayment penalty might be two months of interest or a percentage of the remaining balance, whichever is greater. If you plan to sell the RV in three years and pay off the loan, that penalty can eat into your equity by several thousand dollars. The calculator won't show this. You have to read the contract.
Building your own vs using an online tool
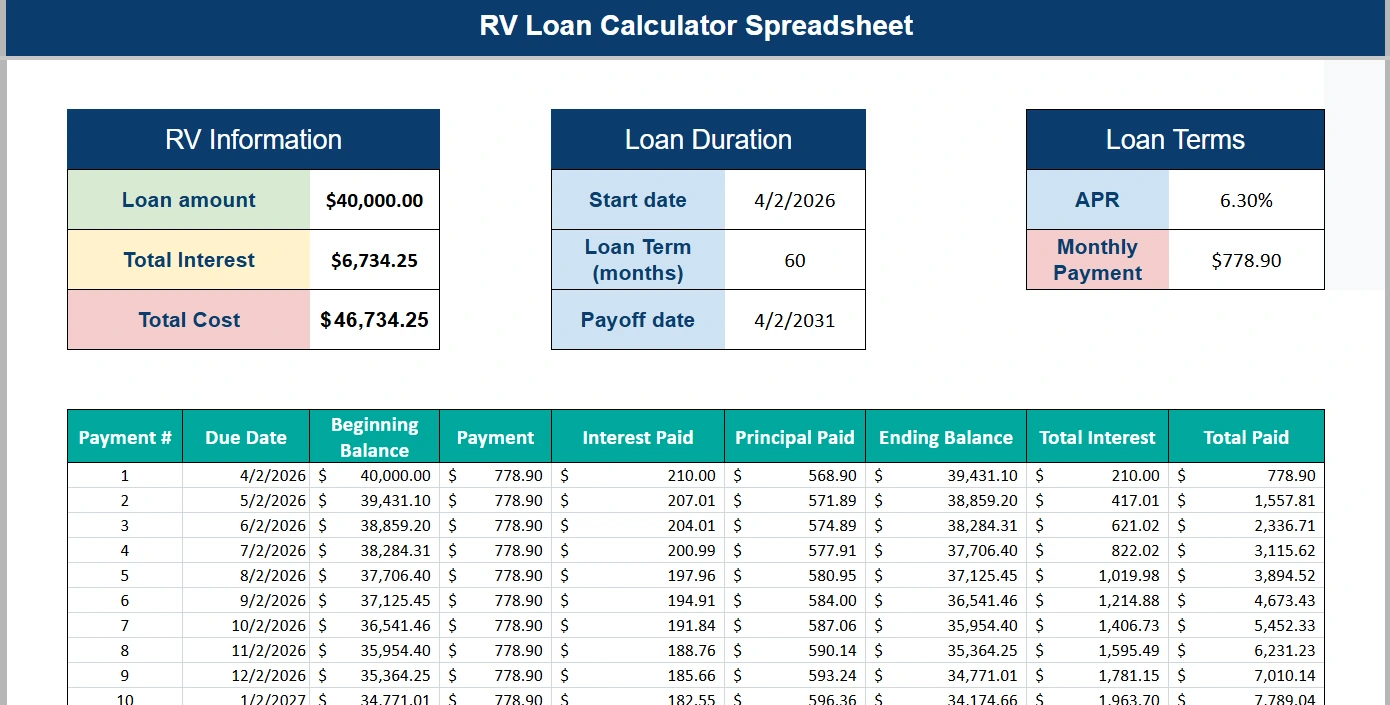
Online calculators are fine for initial planning. They're fast, free, and good enough to give you a general idea of what you're working with. But if you're serious about this purchase, building a simple spreadsheet gives you far more control. You can adjust the rate month by month, factor in extra payments, model different down payment scenarios, and see exactly how much interest you save by paying an additional $50 or $100 each month. The Excel formula for a standard amortizing loan is =PMT(rate/12, total_months, -loan_amount). The rate should be your annual percentage rate divided by 12, and total_months is your loan term multiplied by 12 if you're entering it as years. It produces the exact same number the online calculators show, but your spreadsheet becomes a living document you can update as offers come in. I keep a running tab for clients where I plug in each lender's terms side by side. It takes five minutes to set up and it saves hours of back-and-forth when you're trying to decide between two quotes that look similar on the surface but have very different total costs. If you're looking for a downloadable tool, there aren't many dedicated RV-specific calculators that hold up to scrutiny. Most of what you'll find online is a generic auto loan calculator with an RV skin on it. The IRS Pub 535 worksheet for vehicle loan interest is more accurate than half the free tools I've seen, and it at least accounts for the fact that RVs used partially for business have different depreciation rules. For personal use calculations, a basic spreadsheet is usually better than any third-party calculator you'll find on a dealer's website.
Numbers that actually matter beyond the monthly payment
The monthly payment is the first number people fixate on, and it's the least useful one in isolation. Two loans can have the same monthly payment but wildly different total costs. One might be a 60-month loan at 8% with a $10,000 down payment. The other might be a 180-month loan at 10% with no down payment. Same payment, completely different financial situations. Always compare the total interest paid and the total amount paid over the life of the loan, not just the monthly figure. Your debt-to-income ratio matters more than the payment itself. Lenders look at your total monthly debt obligations divided by your gross monthly income. If your calculated RV payment pushes your DTI above 43%, most conventional lenders will either decline you or require you to jump to an exotic or subprime loan with a significantly higher rate. A good rule of thumb is to keep your total housing and transportation debt under 36% of your gross income. The RV payment alone should ideally be under 15% of your take-home pay. Those aren't hard limits, but they're the thresholds where lenders start getting nervous and adjusting their terms. Here's something people rarely think about: the age of the RV affects your financing options. Many lenders won't finance an RV that's more than 10 to 15 years old, depending on the loan amount and the lender's internal guidelines. If you're looking at a used Class C from 2008, you might be limited to credit union loans or specialized lenders who charge higher rates. The calculator will give you a payment, but it won't tell you that very few lenders will touch the loan in the first place. Check the lender's age restrictions before you do anything else.

Insurance is another post-closing cost that changes the real monthly number. An insured RV with a $2,000 deductible and full coverage typically runs $150 to $400 per month depending on the value, your location, and your driving record. Add that to your loan payment and you get a much clearer picture of the actual monthly cost of owning the thing. A $700 loan payment quickly becomes a $1,000 housing expense when you factor in insurance, storage, and routine maintenance.