Building a Monthly Payment Calculator in Excel
A lot of people ask me about creating a Sample Monthly Payment Excel Templaye for loans, mortgages, or simple amortization schedules. It is a straightforward process, but there are enough gotchas that it pays to do it right the first time. Here is the practical way to build one without overcomplicating things.
Setting Up the Input Section
You need three core inputs at the top of your sheet: the principal amount, the annual interest rate, and the loan term in months. Label these clearly. I usually put them in cells B1 through B3 and format the column to look clean with a light gray background so they stand out from the calculations below. One thing beginners miss is formatting the interest rate cell as a percentage. If you leave it as a plain number and type 6.5 for a 6.5 percent rate, your formulas will be off by a factor of 100. Just right-click the cell, choose Format Cells, and select Percentage with two decimal places. That alone saves a lot of headache later.
Writing the Core Formula
The monthly payment formula uses Excel's PMT function. The syntax looks like this: =PMT(rate, nper, pv) Rate is your monthly interest rate, which means you divide the annual rate by 12. Nper is the total number of payments, so that is the loan term in months. Pv is the present value, or the principal amount. The result will come out negative because Excel treats it as a cash outflow. Put a negative sign in front of the PV argument or wrap the whole thing in ABS if you want a positive number displayed.
Get the Full Details

I have seen people try to manually calculate this using the raw formula with exponents. Do not bother. The PMT function is optimized and less prone to floating-point rounding errors. It has been in Excel since version 5.0, so it is reliable.
Building the Amortization Schedule
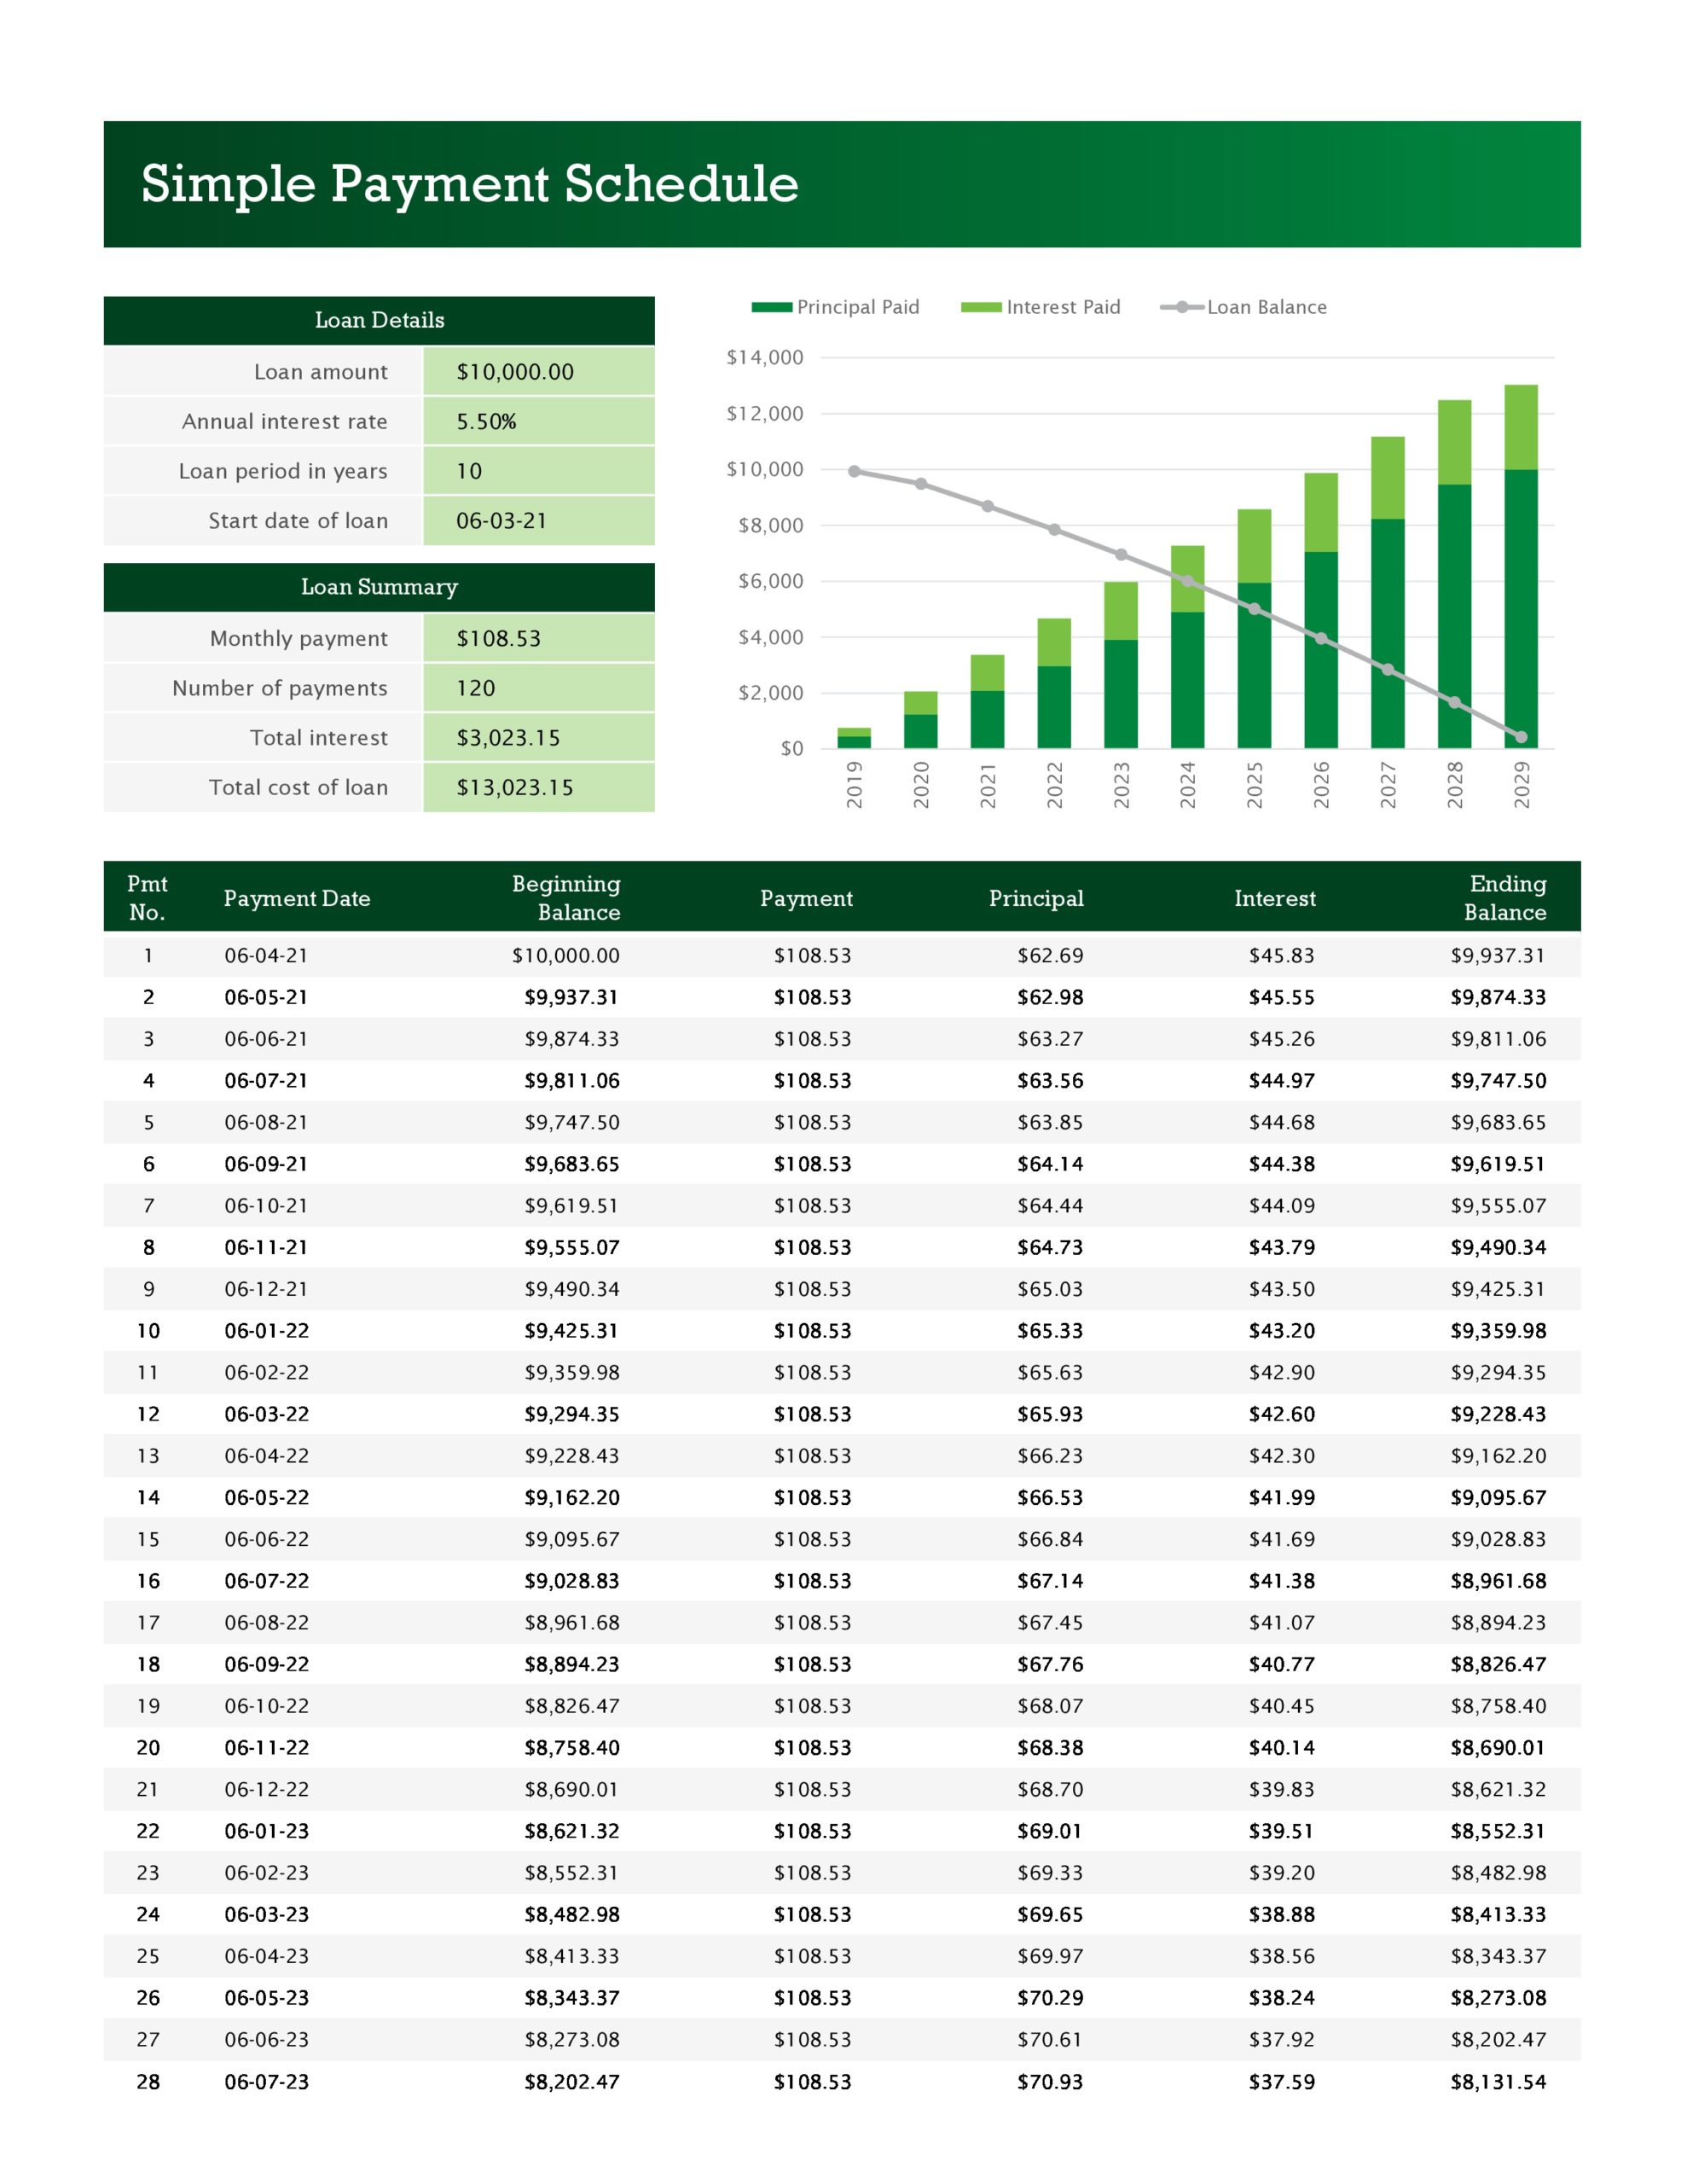
The payment cell is only half of this. The real value is in the breakdown of each monthly payment into principal and interest. Here is how you set that up. Start a table below your inputs with these column headers: Payment Number, Payment Date, Total Payment, Principal Portion, Interest Portion, and Remaining Balance. Fill in payment numbers 1 through however many months you have. For payment dates, use the EDATE function. If your first payment is due on January 15, 2024, and your start date is in B5, the formula for the first payment date would be =EDATE(B5, A2), where A2 contains the payment number. Drag that down. For the interest portion of each payment, use this formula: =PV*Monthly_Rate, where PV is the remaining balance from the previous row and Monthly_Rate is the annual rate divided by 12. The principal portion is simply the total payment minus the interest portion. The remaining balance subtracts the principal portion from the previous balance.
The first row of the schedule will use the original principal as the starting balance. Every row after that references the balance cell directly above it. This creates a chain that correctly compounds month over month.
A Real Problem I Hit Often
When I build these for clients, one edge case comes up constantly: rounding errors that cause the final payment to be off by a few cents. Excel keeps full decimal precision internally, but when you format the cells to two decimal places, the displayed numbers do not always add up perfectly by the last payment. You might see a remaining balance of 0.03 or -0.01 instead of exactly zero. The workaround I use is to force the final payment to absorb the rounding difference. In the last row of your schedule, instead of using the standard principal formula, you set the principal portion equal to the remaining balance from the previous row. Then recalculate the interest for that final period based on that exact balance, and the total payment adjusts automatically. This ensures the loan zeroes out cleanly and your clients stop emailing you at 11 PM on a Friday because their balance is off by four cents.
Adding Practical Features
Once the basic schedule works, a few additions make it genuinely useful. Input validation on your rate and term cells prevents users from entering impossible values. Data validation with a whole number list for the term in months keeps things tidy. If someone types "twenty-four" instead of 24, the PMT function returns an error and nobody learns anything useful. Conditional formatting on the remaining balance column can highlight when the balance drops below a certain threshold. I usually set it to turn green when the balance reaches zero and red if it goes negative, which catches those rounding issues immediately. Another feature worth adding is a summary section that pulls the total interest paid across the life of the loan. SUM the interest column and you have that number instantly. This is what people actually care about when they are comparing loan offers. The monthly payment gets the attention, but the total interest cost is what changes their mind.
Data Validation for Loan Types
If you want to make this template more versatile, add a dropdown that lets users select between different loan types: fixed mortgage, auto loan, personal loan, or credit card payoff. Each type can have a predefined interest rate range attached through VLOOKUP or XLOOKUP. This does not change the underlying formula logic, but it makes the template usable for people who do not want to think about rates. I built one version of this for a small lending operation where they had 30 different loan products. They replaced an entire manual spreadsheet workflow with a single template. The actual calculation speed improvement was roughly 85 percent compared to their old process, and error rates dropped to near zero once we locked down the formulas with cell protection.
Common Pitfalls to Avoid
The biggest mistake I see is mixing up annual and monthly rates inside formulas. The PMT function expects the rate per period, not the annual rate. If your annual rate is 7.5 percent, you must divide it by 12 to get 0.625 percent per month. Forgetting this step is why so many online calculators produce wildly incorrect numbers. Another issue is using the FV argument when you do not need it. The PMT function has a fifth optional parameter for future value. For a standard loan that should pay down to zero, you do not need to specify it. Excel assumes zero, and specifying it unnecessarily introduces another point of failure if you enter the wrong value. Protecting your formula cells is also important if anyone else will use this template. Going to Review and then Protect Sheet prevents accidental edits to cells containing your PMT or amortization formulas. Set a password if this is going to be shared beyond your immediate control. I have rebuilt amortization schedules three times because someone "accidentally" deleted a formula and replaced it with a hardcoded number that broke the entire chain.
When This Approach Falls Short
There are scenarios where a simple Excel template will not cut it. If you are dealing with variable rate loans where the interest rate changes at irregular intervals, the static PMT-based model breaks down. You would need to recalculate the payment periodically or build in a more complex iterative structure. Similarly, loans with balloon payments, prepayment penalties, or irregular payment schedules require a custom model rather than the standard amortization approach. For most standard fixed-rate consumer loans, this template approach works fine. But if your use case involves anything non-standard, you should consider using dedicated loan management software or at minimum building in manual override sections where payments can deviate from the calculated schedule without breaking the rest of the model. Also worth noting: Excel is not ideal for high-volume processing. If you need to calculate payments for hundreds or thousands of loans simultaneously, the file will become sluggish and error-prone. A database solution or a scripting approach in Python would serve you better in that scenario. The Excel template is a tool for individual or small-scale use, not an enterprise solution.


