Understanding SBA Loans Without Losing Your Mind
SBA loans aren't as straightforward as the paperwork makes them look. The Small Business Administration doesn't actually lend you money directly in most cases. They guarantee a portion of the loan through participating lenders, which means a bank still decides whether to approve you. That's the first thing most people get wrong when they're starting out. I went through this process about three years ago for a client who wanted to expand their warehouse operation. The loan program they were looking at was the 7(a) program, which is the most common one. They needed around $250,000 for equipment and leasehold improvements. What they didn't realize was that the SBA has very specific debt service ratios they enforce, and the numbers weren't going to work on paper without some creative documentation from the start.
Sba Loan Questions And Answers
The most frequent question I get is whether an SBA loan is easier to qualify for than a traditional business loan. The answer depends on your situation. If you've been operating for less than two years, SBA programs can actually be more accessible because they consider character and collateral alongside financials. But if you have good credit and solid revenue history, a conventional term loan might cost you less over time since SBA guarantees come with fees that add up. Another common question revolves around what counts as acceptable collateral. The SBA wants a first lien position on most assets, but they'll also look at overall repayment ability. I once had a situation where a borrower had minimal physical assets but strong receivables. We structured the loan using accounts receivable as collateral and got it approved without touching the owner's personal property. Not every lender offers that flexibility though, so shop around if you're in a similar spot.
The Application Process Doesn't Have to Be Painful
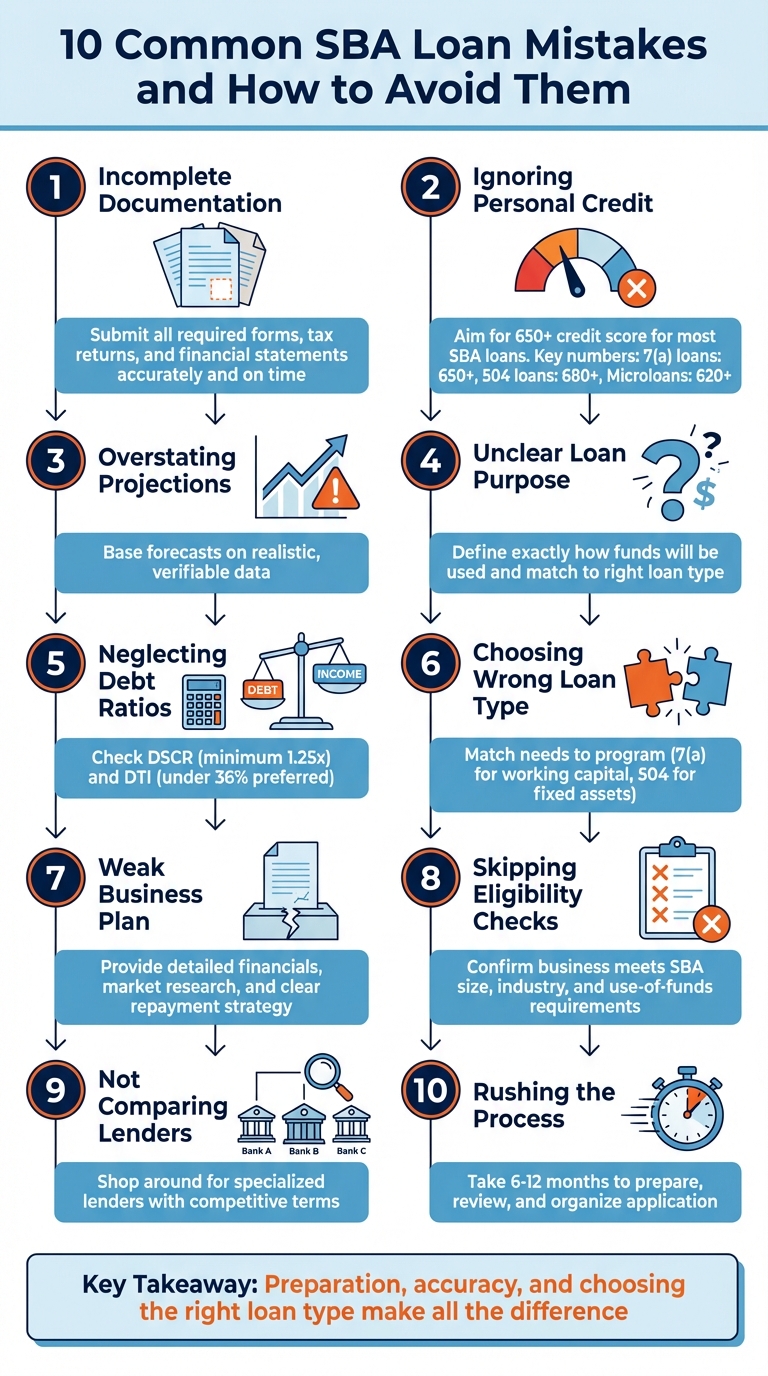
Start with your financial statements. Three years of tax returns, year-to-date P&L, and a balance sheet are the standard requirements. Make sure your profit and loss statement matches what's on your tax filings. I've seen applications rejected because the numbers on the P&L showed significantly higher revenue than what was reported to the IRS. That discrepancy raises red flags faster than anything else. Write a solid business plan section. The SBA reviewers want to understand why you need the money and how you'll pay it back. This doesn't need to be thirty pages. Two or three well-organized pages covering your market, competitive position, and repayment strategy are usually sufficient. Include projections that are realistic, not optimistic to the point of being unbelievable. A projection showing 40% growth year one with no major contract secured in hand will get you questioned heavily. Personal note: One thing that surprised me during my first SBA application was the personal guarantee requirement. Every owner with 20% or more ownership has to sign a personal guarantee. If you have multiple owners, everyone above that threshold signs. I learned this the hard way when a client thought one of his silent partners was exempt because he didn't handle day-to-day operations. He wasn't. The SBA requires signatures from all qualifying owners regardless of their involvement level.
Get the Full Details

Common Pitfalls That Delay or Kill Applications
Lenders often reject SBA applications before they even reach the SBA for guarantee consideration. This happens when the debt service coverage ratio falls below 1.15, which is roughly the minimum most lenders require. DSCR measures whether your cash flow can cover debt payments. Calculate it before you apply. Take your net operating income and divide it by your total debt obligations. If it's under 1.15, you'll need to improve your numbers or reduce the loan amount before approaching a lender. Another issue is incomplete or inconsistent documentation. I've seen applications delayed by weeks because a borrower submitted bank statements that didn't match their revenue on the tax returns. This usually comes down to commingling personal and business accounts or underreporting income. Fix it by reconciling your accounts properly before you start the application process. It'll save you significant time down the line. Credit scores matter more than some people expect. While the SBA doesn't set a hard minimum, most lenders want a personal credit score of at least 680. If you're below that, you'll face stiffer scrutiny and potentially higher interest rates. I worked with a borrower who had a 640 score and strong business fundamentals. We spent extra time preparing a letter explaining the credit issues and demonstrating how the business could still comfortably service the debt. It worked, but it required more effort upfront.
Timing and Expectations
An SBA 7(a) loan typically takes between 30 to 90 days from application to funding, depending on the lender and the complexity of the deal. Express loans, which go up to $350,000, can close faster, sometimes in under two weeks. If you're in a time crunch, ask about the express or preferred lender streamlining option at your bank. Not all lenders participate in these expedited tracks, so find one that does before you invest time in the full application. Interest rates on SBA loans vary based on the prime rate plus a risk premium. As of recent years, rates have ranged from around 8% to 13% depending on loan size and term. Larger loans over $250,000 tend to have lower rates because the risk is spread differently. Don't assume the first rate offer is the best you'll get. Negotiate, especially if you have strong credit and solid business metrics. The SBA also charges guarantee fees, which vary by loan amount and term. For a 7(a) loan under $150,000, the fee is roughly 2% to 3% of the guaranteed amount. For larger loans, it decreases on a sliding scale. Factor these fees into your total cost of borrowing. They're not insignificant and can add thousands to the overall expense.
When SBA Loans Aren't the Right Fit
SBA loans aren't ideal for everyone. If you need funds quickly, within two weeks, a traditional line of credit or invoice factoring might serve you better. SBA processing times make them unsuitable for urgent working capital needs unless you use the express program and your documentation is already organized. If you have excellent credit and strong revenue, a conventional bank loan might offer lower total costs. SBA fees and slightly higher rates can make them more expensive over the life of the loan compared to a well-negotiated conventional term loan. Run the numbers both ways before committing. Also consider that SBA loans have certain restrictions on use of proceeds. You can't use SBA funds for speculative purposes, paying off existing debt without clear justification, or certain types of real estate investment. Review the allowed uses carefully to avoid complications later. Some lenders will pull the loan if they discover misuse of funds, and that creates problems for everyone involved.

The key is going in with realistic expectations and well-organized financials. The SBA program is valuable but it requires patience and preparation. Most rejections happen because of poor documentation, not because the business is fundamentally unsound. Fix the paperwork first, then worry about the rest.