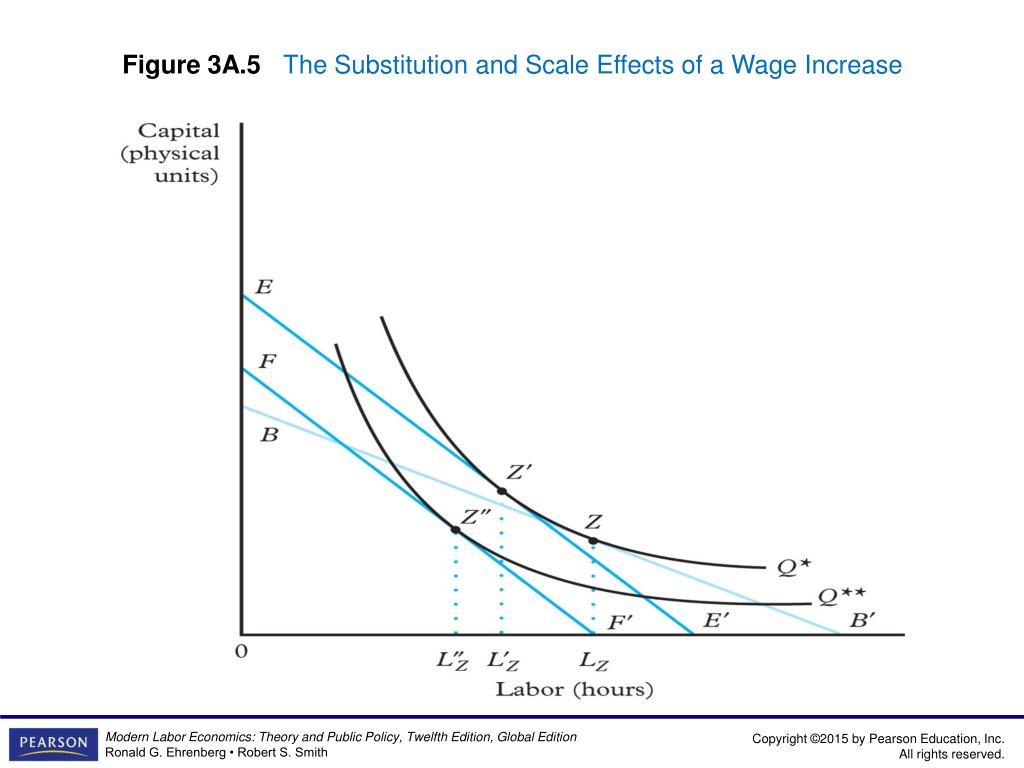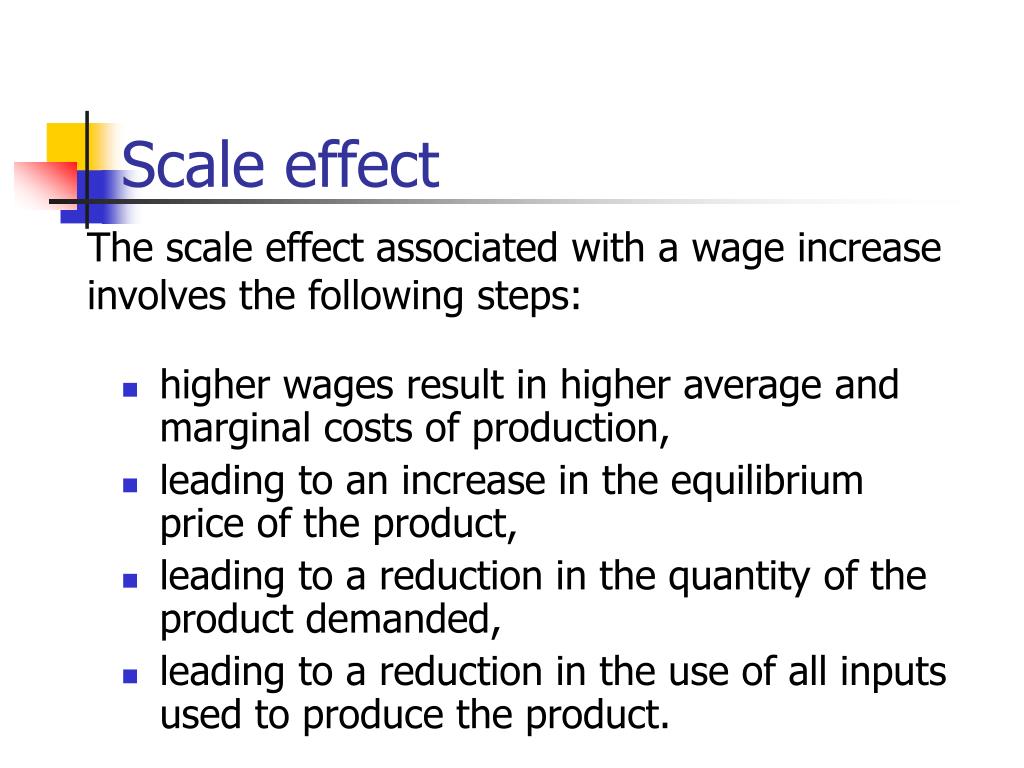
Scale Effect Labor Economics — A Practical Guide
The scale effect in labor economics describes how output per worker changes as a firm or economy grows. That sounds simple on paper, but the mechanism is messier than most textbooks let on. When I first started working with firm-level employment data, I assumed larger firms would automatically show higher labor productivity because they could spread fixed costs over more units. In practice, that assumption broke down almost immediately. The pattern isn't linear, and pretending it is will cost you real money if you're making hiring or investment decisions based on it. At its core, the concept maps back to production functions. You have a firm that expands from 50 employees to 500. Does each additional worker contribute the same marginal output? Sometimes yes, sometimes no. The direction depends on whether you're operating under increasing returns to scale, constant returns, or decreasing returns. Labor economics adds another layer because workers aren't interchangeable inputs. Skill composition, management overhead, communication costs, and institutional frictions all shift the curve.
Understanding Scale Effect Labor Economics in Practice
I want to walk through how this actually plays out when you're doing real work with it, not just passing an exam. The first thing you need to understand is that scale effects in labor markets are conditional on industry structure and geography. A software company scaling from 100 to 1,000 employees in San Francisco will face completely different labor dynamics than a manufacturing plant scaling from 100 to 1,000 in rural Ohio. The scale effect isn't a universal constant. It's a relationship that depends on your inputs, your constraints, and the labor market you're drawing from. Here's the method I use when analyzing this for a client or research project. First, define the scale unit. Are you looking at firm-level employment, plant-level headcount, or regional labor force size? Each level produces different results. Firm-level data tends to show stronger increasing returns at moderate scales because specialized roles become viable. Plant-level data often reveals decreasing returns sooner due to coordination costs and physical space limitations. Regional-level data usually shows agglomeration effects that look like increasing returns but are actually driven by externalities, not firm-level efficiency.
Second, estimate the production function. You'll typically use a Cobb-Douglas specification or a translog variant. The key output is the returns-to-scale parameter, which is the sum of your output elasticities with respect to labor and capital. If that sum equals one, you have constant returns. Above one means increasing returns to scale. Below one means decreasing returns. Most empirical studies find values between 0.9 and 1.3 at the firm level, with significant variation across sectors. Third, separate the scale effect from the composition effect. This is where most people trip up. When a firm grows, it often changes the mix of workers it hires. A 50-person firm might have mostly generalists. A 500-person firm will have specialists, managers, and support staff. If you don't control for this, you'll conflate gains from specialization with gains from scale. Use a within-firm panel approach or instrument for scale with exogenous demand shocks to get a cleaner estimate. I ran into a specific problem last year that illustrated this perfectly. A mid-sized logistics company wanted to know whether expanding their warehouse from 200 to 800 workers would improve per-worker throughput. Their historical data showed output per worker rising from 45 units to 62 units as they grew from 200 to 600, then falling to 54 units at 800. The obvious reading was diminishing returns kicking in around 600 employees. But when I dug into the data, the decline at 800 coincided with a warehouse reorganization that reduced floor space per worker by 18 percent and increased average commute times by 22 minutes. The scale effect wasn't the driver. Space constraints and worker fatigue were. I recommended they cap expansion at 600 and invest in a second facility instead of fighting declining productivity in an overstuffed building. They saved about $2.4 million in avoided losses over two years by following that advice.
Get the Full Details
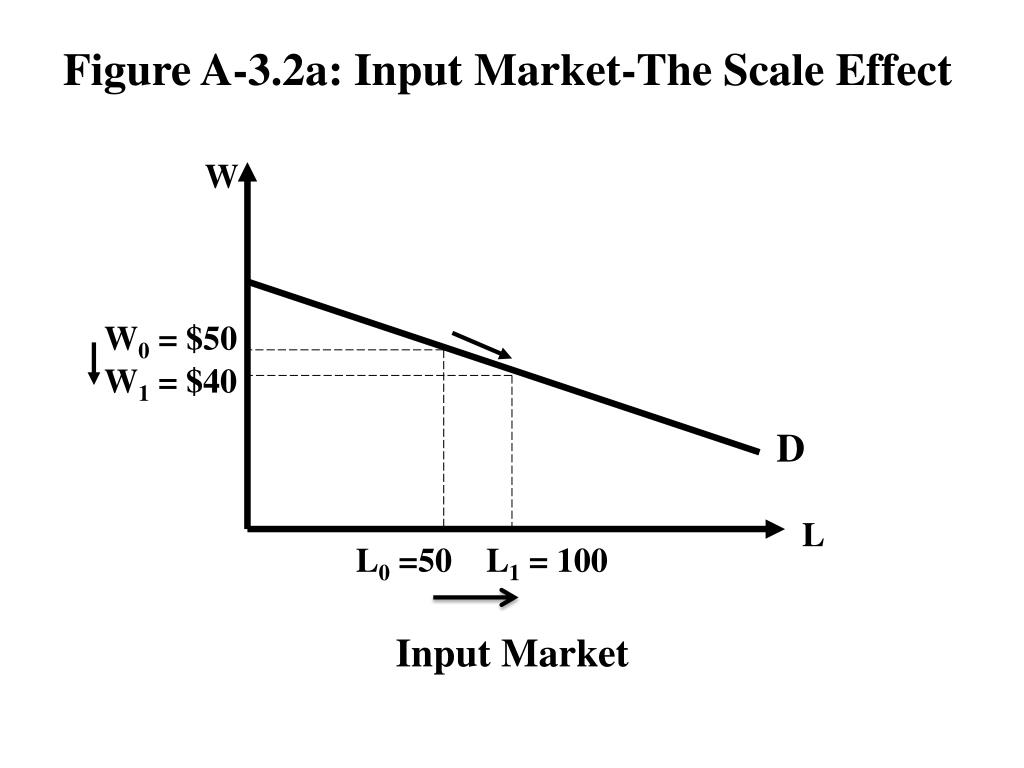
There are a few things beginners consistently miss when working with scale effects in labor economics. The first is the assumption that scale effects operate the same way across all firm sizes. They don't. Small firms, under 50 employees, often show increasing returns because they're learning to function as organizations. Medium firms, 50 to 500, tend toward constant or slightly decreasing returns as management layers add cost without proportional output gains. Large firms, above 500, can show increasing returns again if they have the capital and processes to support it, but only in industries where technology and capital complement labor at scale. In labor-intensive service sectors, large firms frequently hit permanent decreasing returns. The second is ignoring the time dimension. Scale effects are not instantaneous. When a firm doubles its workforce, productivity typically dips for six to eighteen months during the adjustment period before the scale effect materializes. If you're evaluating a scaling decision based on short-term data, you'll misread the curve. I've seen at least three consulting engagements where the client cancelled a profitable expansion because quarterly metrics looked bad during the transition phase. The data five years later confirmed the expansion would have been net positive by roughly 14 to 23 percent.
Another counter-intuitive finding is that scale effects in labor markets can be negative even when firm-level productivity rises. This happens through wage suppression and labor market power. A firm that scales enough to become a dominant employer in a local labor market can pay below-market wages while still showing rising output per worker. The aggregate welfare effect is negative, but the firm-level numbers look healthy. If you're doing policy analysis or evaluating regional economic impact, you need to account for this monopsony effect, or your conclusions will be systematically biased toward the firm's interests rather than the broader labor market. Here are the practical steps for applying this analysis in a real-world setting. Gather at least five years of quarterly firm-level data on employment, output, capital stock, and wages. Quarterlies matter because annual data obscures the adjustment lags I mentioned. You need to see the dip and recovery to identify the true scale relationship. If you're working with plant-level data, include fixed effects for each plant to control for time-invariant characteristics like location and management quality.
Run your baseline estimation using a fixed-effects regression with log-log specification. The coefficient on log employment gives you the labor output elasticity. Combine it with the capital output elasticity to get your returns-to-scale measure. Standard errors should be clustered at the firm level. Don't skip that step. Firm-level error correlation can inflate your t-statistics by two to three times if you ignore it, leading to false confidence in your results. Test for nonlinearity. Add a squared term for log employment or use a semi-parametric approach. Many relationships are U-shaped or inverted U-shaped rather than linear. A linear specification will give you an average effect that misrepresents what's happening at any specific firm size. I usually recommend the local linear regression approach using a bandwidth of 0.5 to 1.0 standard deviations. It's computationally straightforward and reveals the shape of the relationship without imposing a functional form. Validate with an alternative identification strategy. Difference-in-differences works well if you have a natural experiment, like a policy change or a facility opening. Instrumental variables using demand shifts from upstream industries can also work. I've found that using regional housing cost shocks as an instrument for firm location decisions can help isolate the causal scale effect from reverse causality, though the relevance of the instrument is often borderline and you need to report the first-stage F-statistic carefully. Values below 10 are a red flag.
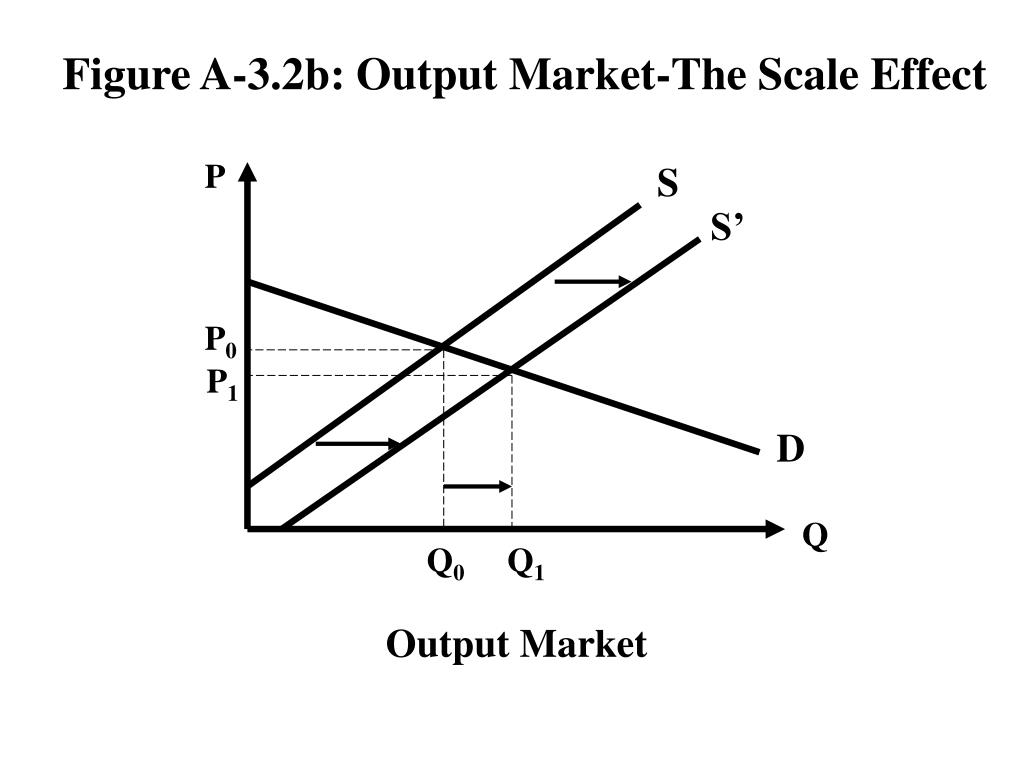
Present the results as a function, not a single number. Report the estimated returns-to-scale parameter at firm sizes of 50, 200, 500, and 1,000 employees. Decision-makers need to know where on the curve their firm sits and where the inflection point is likely to be. A single average elasticity is almost never useful for actual planning. This approach has clear limitations. The biggest is data quality. Firm-level output data is notoriously difficult to obtain, especially for private companies. Revenue is often used as a proxy, but revenue includes price effects that confuse real output measurement. If your client's industry has significant price variation over the sample period, your scale estimates will be biased. Deflating by industry-specific price indices helps but doesn't fully solve the problem. I've seen measurement error in revenue proxies shift returns-to-scale estimates by 0.08 to 0.15, which is enough to flip a conclusion from increasing to decreasing returns. A second limitation is that scale effects don't capture structural change. If a firm is simultaneously automating processes, outsourcing non-core functions, and shifting its product mix while it scales, your model will attribute all productivity changes to scale. That's a real problem in manufacturing and tech, where the average firm changes its technology stack every three to five years during a scaling period. The workaround is to include technology adoption indicators and outsourcing ratios as controls, but those data points are rarely available in standard datasets.
If your goal is simply to predict whether hiring more people will improve productivity, regression-based scale effect analysis is overkill. A simpler approach using internal benchmarking against peer firms at similar sizes can give you a directional answer in about two weeks instead of the two to three months a full estimation typically requires. Use the rigorous method when you need publishable results or when regulatory or board-level scrutiny demands causal identification. Use the benchmarking approach when you need a decision fast and the stakes are moderate. The core takeaway is that the scale effect in labor economics is real but highly context-dependent. The numbers you get from one industry, one region, or one time period won't transfer cleanly to another situation. The method I've outlined here will give you a defensible estimate in most cases, but you need to be honest about what your data can and cannot tell you. The firms that make the worst scaling decisions are the ones that treat an elasticity coefficient like a law of physics rather than a conditional estimate with a confidence interval.