What You Actually Need to Know About a Second Mortgage
A second mortgage is just a loan taken out against a property that already has a primary mortgage on it. The debt sits in second lien position. If you default, the first mortgage holder gets paid first from the foreclosure sale, and whatever is left goes to you. That positioning matters more than people usually realize because it changes the risk calculation for the lender and therefore the rate you're offered. I've handled enough of these to know the paperwork looks straightforward until it isn't. Most people come in thinking they just need to prove income and equity. The real friction happens elsewhere.
How Second Morgage Actually Works in Practice
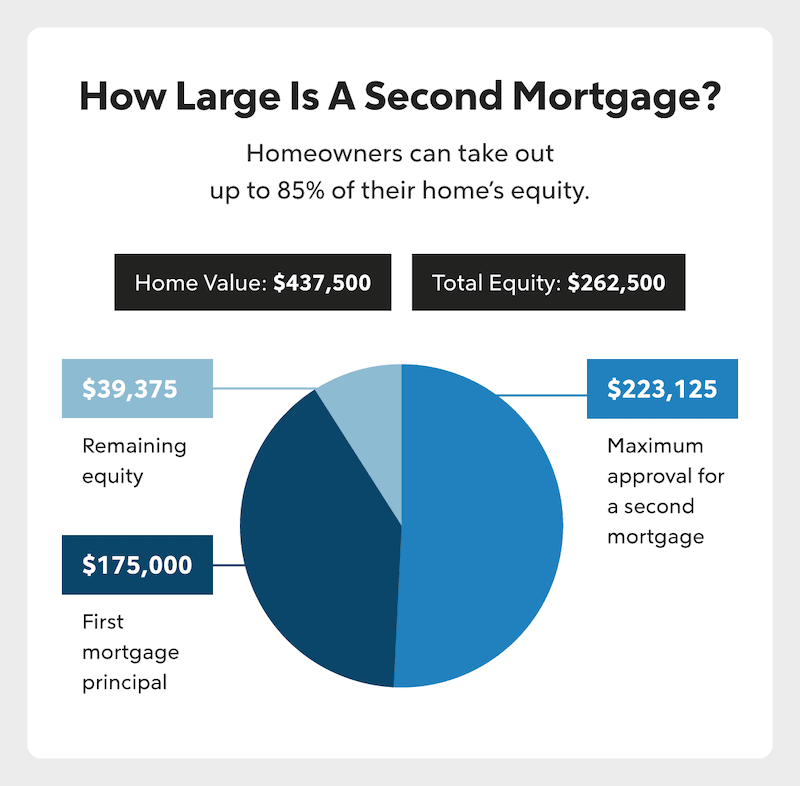
Here's the sequence that rarely gets explained clearly. You apply through a lender, they order an appraisal, and then they run the numbers based on your combined loan-to-value ratio. That's CLTV. It includes both the first mortgage balance and the second mortgage amount combined against the appraised value. Some lenders also factor in a monthly debt-to-income ratio using your total housing payment plus all other recurring debts. Anything above 43% triggers additional scrutiny at most institutions. The appraisal step is where things get slow. Not because appraisals are complicated, but because the secondary market is backed up. During 2022 and into 2023, appraisal turn times stretched from three days to over two weeks in some metro areas. I had a client who needed bridge financing for a property flip and the appraisal delay cost him $400 a day in hold costs. We worked around it by using a desktop appraisal through Appraisals247 for the preliminary number, which came back in 48 hours, and then proceeded with the full drive-by appraisal once the timeline was clearer. The lender accepted both reports side by side. Most second mortgages come in one of three forms. A home equity loan gives you a lump sum with a fixed rate and fixed monthly payments. A home equity line of credit works more like a credit card with a variable rate and a draw period. A cash-out refinance replaces your entire first mortgage with a larger one and pulls out the difference in cash. Each has different tax implications and different rate structures.
The tax angle is something borrowers regularly misunderstand. Under current IRS rules, interest on a second mortgage is only deductible if the funds are used to buy, build, or substantially improve the taxpayer's home that secures the loan. Using it for debt consolidation, medical bills, or a vacation doesn't qualify for the deduction. You can deduct up to $750,000 in total mortgage debt across both loans combined for acquisition indebtedness acquired after December 15, 2017. This limit drops to $1 million for loans taken out before that date. Keep receipts on how you spent the proceeds. The IRS doesn't ask for them at filing time, but they will if you get audited. One counter-intuitive thing about second mortgages: a good credit score matters less than you'd expect once you have substantial equity. Lenders weight equity heavily because it's their primary protection. I've seen borrowers with 680 credit scores approved for second mortgages at competitive rates when they had 40% or more in equity. Conversely, someone with 750 credit and only 15% equity got pushed toward a higher rate and stricter terms. The risk profile is fundamentally different in each case.
Get the Full Details

The Hidden Complication With Piggyback Structures
Sometimes a second mortgage gets paired with the first to avoid private mortgage insurance. This is called an 80-10-10 structure. You put 10% down, take a first mortgage for 80%, and a second mortgage for the remaining 10%. The first mortgage stays below 80% LTV, so no PMI is required. The second mortgage covers the gap. This used to be popular for getting around PMI on jumbo loans or investment properties. There's a catch that barely gets mentioned. Many second mortgages in this configuration come with due-on-sale clauses or prepayment penalties that stack with the first mortgage's terms. If you sell within five years, you could face double penalties. I had a borrower who did an 80-10-10 on a investment property and sold it in year three. The combined prepayment penalties from both loans ate into his profit by nearly $8,000. He hadn't read the fine print on either note. Always check the prepayment penalty schedule on both instruments before closing. Another structural issue involves rate locks. Second mortgage rates move independently of first mortgage rates, though they generally track the same benchmark. If you lock the first mortgage rate for 45 days and the second mortgage rate only for 30 days, you might find yourself in a situation where the first is locked and the second has floated up by the time you close. Always lock both at the same time, and verify that the lock periods align or overlap sufficiently.
Second Morgage Options and When to Avoid Them
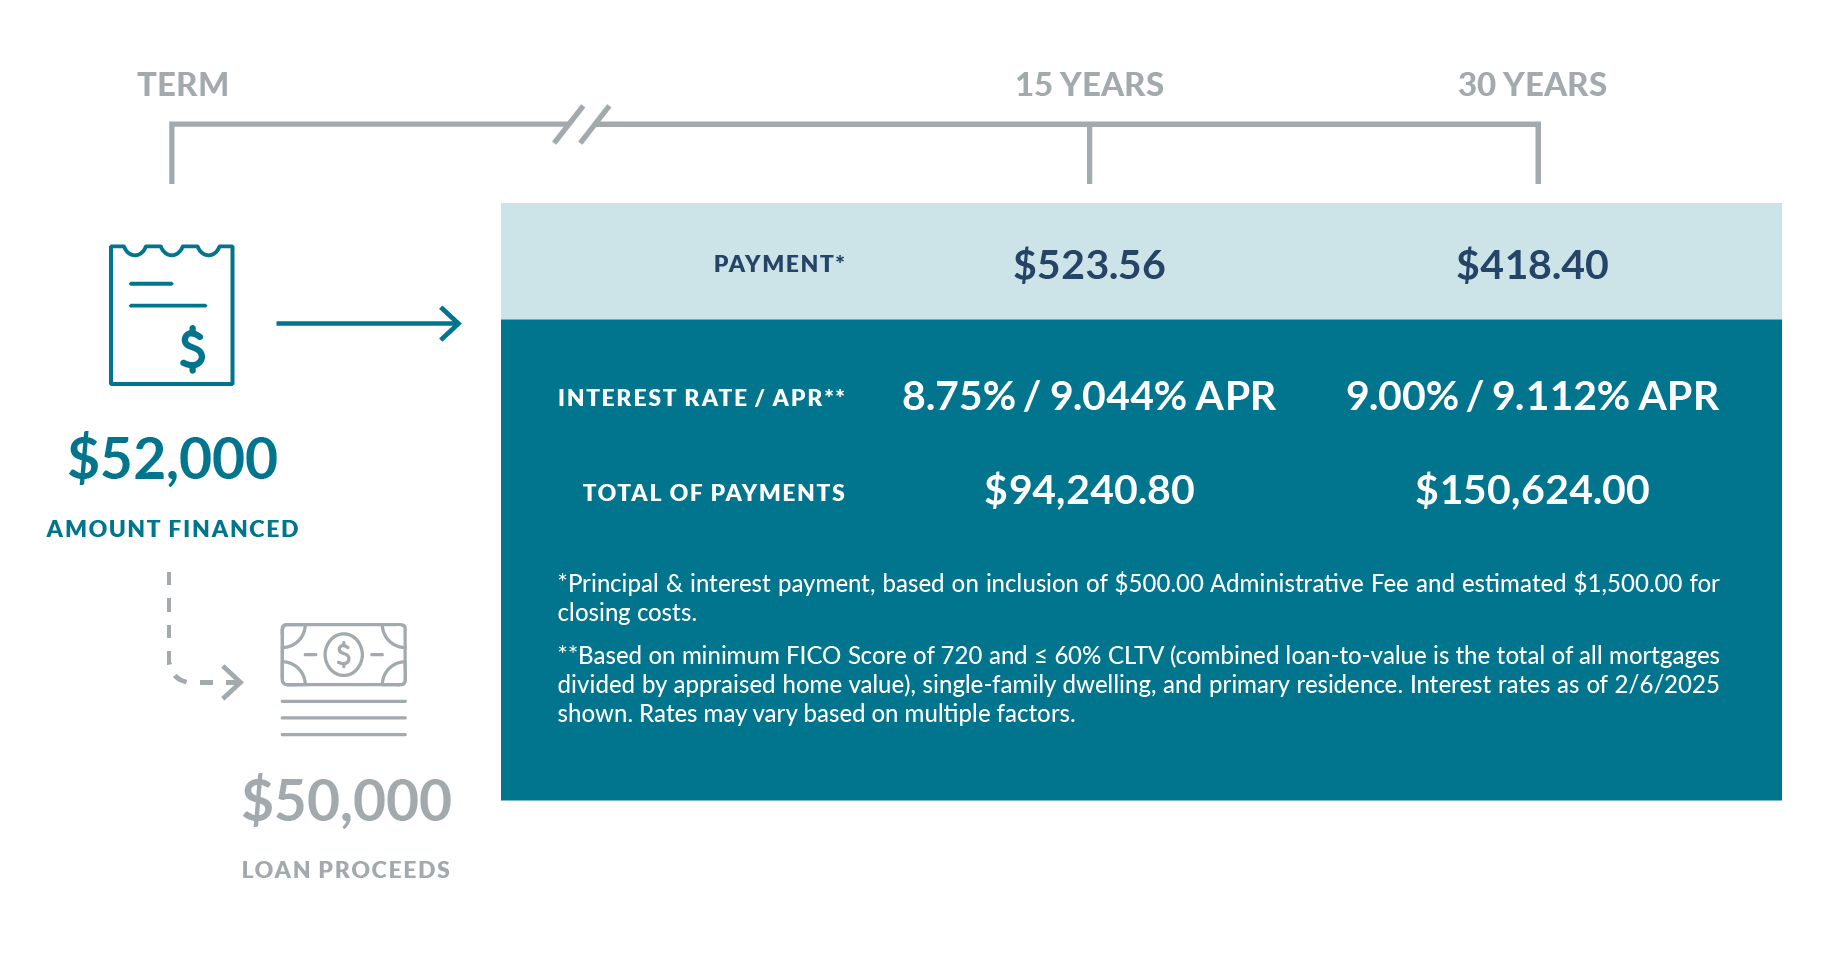
Downloadable comparison sheets exist on lender websites, but they're usually designed to make their own product look better. The ones I've seen are often incomplete. A more reliable approach is to pull rate estimates from at least three sources: a local credit union, a regional bank, and an online lender. Credit unions typically offer slightly lower rates but have slower processing. Online lenders move fast but may charge higher origination fees. Regional banks fall somewhere in between. The biggest limitation of second mortgages is that they're unsecured in effect, even though they're technically secured by your home. Because they sit behind the first mortgage in priority, lenders price them as higher risk. Expect rates to run 1.5 to 3 percentage points above what you'd get on a first mortgage of similar term. For a $200,000 second mortgage at 8.5% instead of 6.5%, that's roughly $4,000 in additional annual interest. Over a 10-year term, that compounds to over $40,000 in extra cost. Second mortgages don't work well in every scenario. If you're underwater on your first mortgage or close to it, you won't have enough equity to qualify. Most lenders require at least 15% equity remaining after the second mortgage closes. If you're using the funds for consumption purposes rather than home improvement, the math almost never favors a second mortgage over a personal loan or HELOC with a lower rate elsewhere. And if your employment is commission-based or contract work, the documentation requirements can add two to four weeks to processing time.
There's also the issue of title complexity. A second mortgage adds a lien to the title, which means any future refinance or sale becomes more complicated. Title companies need to verify the priority order, and settlement attorneys need to calculate payoff amounts for both liens. This adds roughly $300 to $600 in closing costs at sale time. If you're planning to move within five years, that friction adds up. I recently worked with someone who took a second mortgage to pay off high-interest credit card debt. The cards carried 22% APR. The second mortgage ran 8%. On paper it was a clear win. But the second mortgage had a 5-year prepayment penalty that doubled the effective cost if paid off early. She ended up keeping the second mortgage for exactly five years and then refinanced it. The total interest savings over seven years was about $12,000, but she had to monitor the payoff window carefully and set a reminder six months before the penalty expired. Without that discipline, she would have paid the full penalty anyway. The bottom line is that second mortgages are a tool, not a solution. They work best when you have stable income, significant equity, and a clear purpose for the funds that improves the property or consolidates higher-cost debt. They work poorly when you're stretching your equity too thin, when the purpose doesn't generate any return, or when you're counting on future income that might not materialize.

If you're considering one, pull your credit report first. Check for errors. Dispute anything incorrect. A 20-point increase in your score from correcting a simple reporting mistake can save you thousands over the life of the loan. Then get pre-approved with at least two lenders and compare the total cost, not just the rate. Origination fees, appraisal costs, title insurance, and recording fees can vary by several thousand dollars between lenders even when the quoted interest rate is identical.