Understanding What This Tool Actually Does
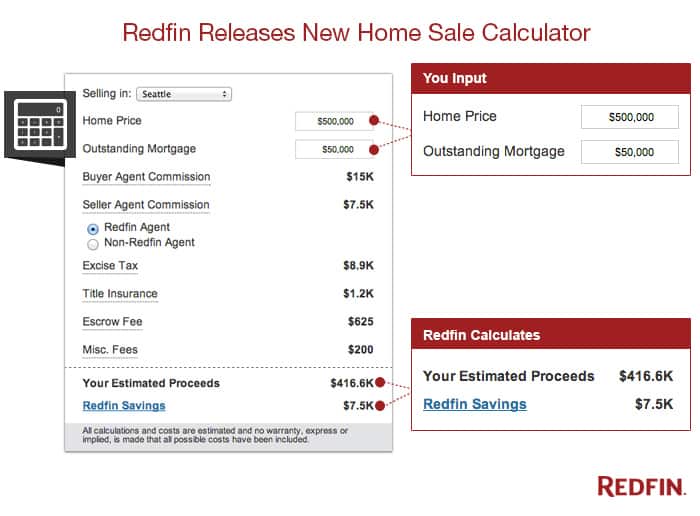
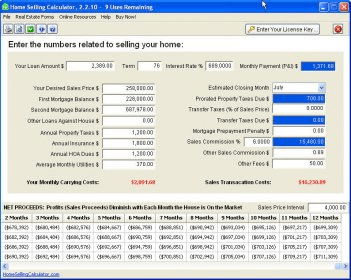
A Selling Home Calculator takes your asking price and subtracts the costs you'll actually face when closing. Most people think selling is just listing price minus mortgage balance. It's nowhere near that simple. There are commissions, transfer taxes, title fees, prorated property taxes, possible capital gains considerations, and a dozen other line items that vary by state and county. The calculator lines all that up so you're not guessing. You start by entering your expected sale price, remaining mortgage balance, and the state where the property is located. From there, the tool pulls standard commission rates and closing cost estimates. But here's the thing nobody warns you about: the default assumptions in most free calculators are rough averages, not local realities. I found this out the hard way with a client in Illinois who was quoted $285,000 in net proceeds by an online calculator, then showed up at closing to an actual $261,000. The missing piece was a local municipal transfer tax that the generic tool simply didn't account for. My workaround was running the same numbers through a second calculator specific to Cook County, then cross-referencing with the county recorder's fee schedule. The gap between the two outputs told us exactly where the first one was lying to her. The fields you should pay attention to are the commission split and the seller concession percentage. Those two numbers move more than anything else on the sheet. A standard 5.5 percent commission breaks down to roughly 2.5 to the listing agent and 2.5 to the buyer's agent, but in some markets negotiating down to 4.5 percent total is common. That's a difference of thousands. Seller concessions on the other hand can range from zero in a hot market to 3 or 4 percent in a slower one, and they directly eat into your net.
What the Numbers Don't Tell You
Most Selling Home Calculator tools output a single net proceeds number and leave it at that. That number assumes the house sells at exactly your asking price. It does not factor in price reductions, inspection credits, or repair negotiations that happen after listing. If you reduce the price by $10,000 partway through, every downstream cost shifts with it. Commissions go down slightly, but you've also lost $10,000 in equity that the calculator never accounted for in its baseline scenario. There's also the matter of capital gains tax exclusion. If you've owned and lived in the home for at least two of the last five years, you can exclude up to $250,000 in gains if you're single or $500,000 if married filing jointly. The calculator won't tell you whether you qualify because it doesn't know your purchase price, your improvement history, or your filing status. I always run a separate gain calculation after the main tool gives me its number. Purchase price plus closing costs from the original purchase plus documented improvements equals your adjusted basis. Sale price minus selling expenses minus your basis gives you the actual gain. Then you apply the exclusion if you're eligible. Another blind spot is the prorated property tax adjustment. In many states, property taxes are paid in advance and then prorated at closing based on the closing date. If your seller's taxes are prepaid through the end of the fiscal year and the buyer closes in March, the seller gets a credit for the unspent portion. Some calculators include this automatically. Others ignore it entirely. The direction matters less than the fact that it exists and can shift your net by a few hundred dollars depending on your local tax cycle.
When a Selling Home Calculator Falls Apart
There are situations where these tools become almost useless. Fixer-uppers priced below market value often have appraisal gaps that complicate the math. Reverse mortgages carry payoff formulas that change quarterly and most calculators don't update for those. Properties with HOA special assessments pending will have fees that never appear in any standard output. And inherited homes thrown into the mix introduce basis calculations that require the date-of-death valuation, which a generic tool cannot possibly know. If your situation involves any of those, I'd recommend running the calculator as a first-pass estimate and then taking the output to a title company or real estate attorney in your area. They can fill in the local variables that no web tool covers. The time savings from doing the initial calculation yourself are still real, but treating the result as final is where people get burned. A good selling home calculator output should give you a range, not a single figure. If the tool you're using only provides one number with no sensitivity analysis, it's probably too basic for anything beyond a straightforward sale in a standard market. Look for one that lets you adjust the commission rate, add custom closing costs, and toggle state-specific taxes on or off. That level of control is what separates a decent estimate from a false sense of security.
Get the Full Details