Understanding Semiannual Calculations in Practice
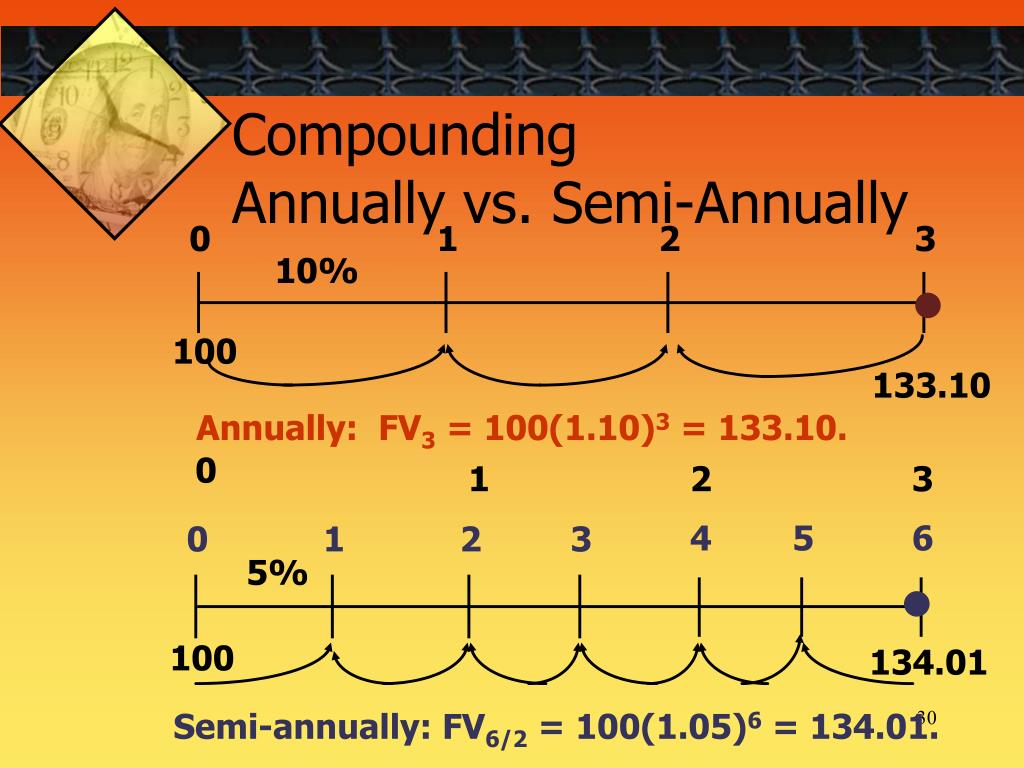
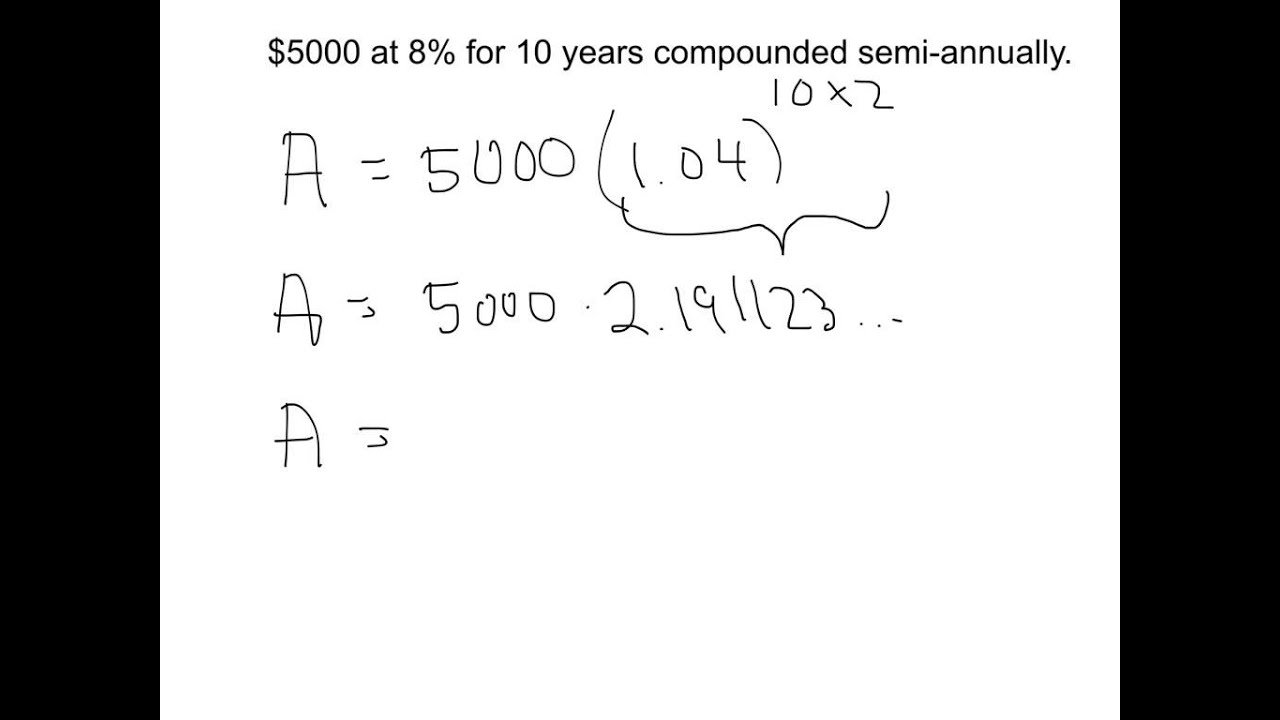
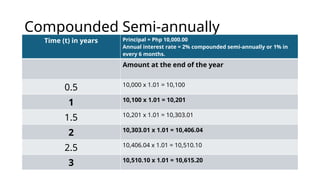
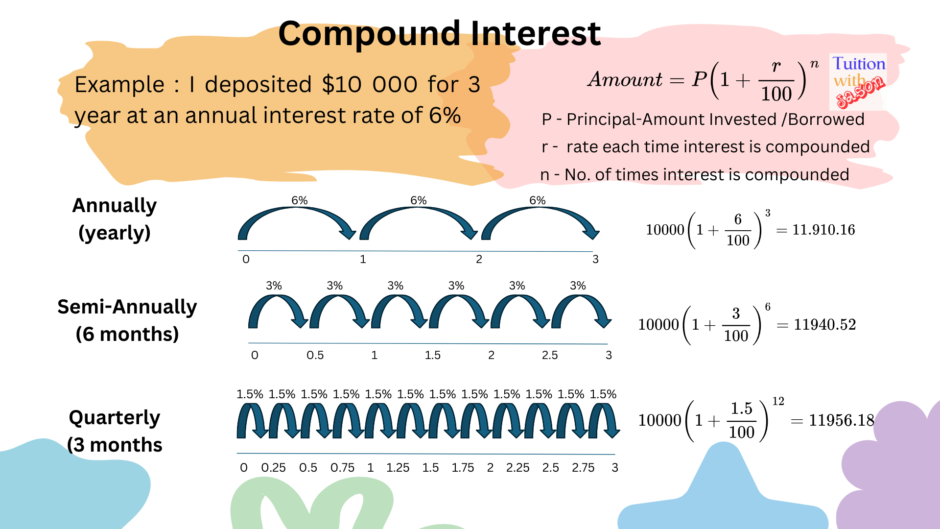
Semiannually just means twice a year, or every six months. In math and finance, this shows up constantly because the calendar splits neatly into two halves. Most people know this on some level but get tripped up when they actually have to calculate something using it. The real problem isn't the definition; it is knowing how to apply the right formula without second-guessing yourself. In mathematical language, semiannual translates to a period of six months or exactly half of a year. When you see semiannual compounding, for instance, it means the interest rate is divided by two and applied twice per year rather than once. The same logic applies to depreciation schedules, loan payments, and tax calculations. I have seen too many people plug the annual rate directly into an annual formula and wonder why the numbers are wrong. Here is the conversion you need to remember without looking it up every time. If the annual rate is r and the compounding is semiannual, the effective periodic rate becomes r divided by 2. The number of periods over n years becomes 2 times n. That is it. The formula for compound interest with semiannual compounding looks like this: A equals P times 1 plus r over 2, raised to the power of 2 times n. You do not need anything more complicated than that.
I spent a few years working with loan amortization tables before this ever felt automatic. My first real headache came from a commercial lease agreement where the rent escalation was stated as 3 percent semiannually, but the lessor had written it in a way that implied an annual rate split in half. The difference between a flat 3 percent every six months and 1.5 percent every six months is massive over time. I ended up having to build a quick spreadsheet to trace both scenarios side by side and show the total discrepancy. It turned out to be about 4.5 percent more in total payments over five years, which made a real difference on the deal.
How to Calculate Semiannual Values Step by Step
Let us walk through an actual calculation. Say you have a principal of $10,000 at an annual interest rate of 8 percent compounded semiannually for three years. First, divide the annual rate by 2. That gives you 4 percent per period, or 0.04 in decimal form. Next, multiply the number of years by 2. Three years becomes six compounding periods. Now apply the compound interest formula. You get 10,000 times 1.04 raised to the sixth power, which comes out to roughly $12,653.19. If you had mistakenly used annual compounding, you would have gotten about $12,597. Less than $60 difference in this case, but the gap widens significantly with larger principals and longer timeframes. For simple interest, the math is even more straightforward. Semiannual simple interest just means you apply half the annual rate for each six-month period. So if you need the interest for one period, you take the principal times the annual rate divided by 2. For multiple periods, multiply again by the number of periods. This is the kind of thing that shows up in basic accounting courses and then gets forgotten until someone asks you to verify a payment schedule at 11 PM before a deadline. One detail that people regularly miss involves day count conventions. In practice, not every six-month period contains exactly the same number of days. A semiannual period from January to June has 181 days in a common year and 182 in a leap year. From July to December is usually 184 days. Bond markets and some loan agreements account for this using actual over 360 or actual over 365 conventions. If you are working with precise financial instruments, ignoring the day count can introduce small but real errors. For most textbook problems and general business use, it does not matter. But when I was reconciling bond coupon payments for a small portfolio once, I caught a discrepancy caused by exactly this issue. The fix was just switching from a naive semiannual split to the actual day count method, and the numbers aligned perfectly.
Get the Full Details
Common Pitfalls and What to Watch For
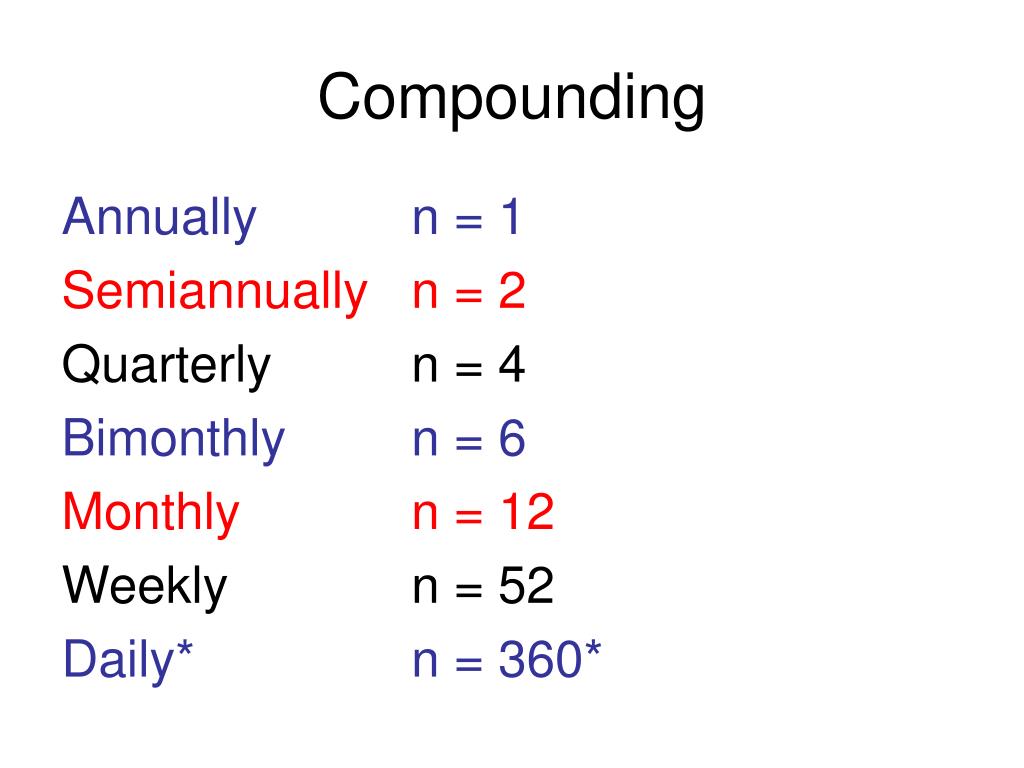
The most frequent error is confusing semiannual with bimonthly. These are not the same thing. Semiannual means twice a year. Bimonthly can mean either twice a month or every two months depending on context. In financial documents, bimonthly almost always means every two months, which creates six periods per year, not two. Mixing these up will throw off your calculations immediately and you might not realize it until the final total looks wrong. Another trap is failing to convert percentages to decimals before dividing. Writing 8 divided by 2 gives you 4, but you need 0.04 for the formula. People who skip this step end up with astronomically large numbers and then assume the formula itself is broken. It is never the formula. Semiannual calculations also break down in situations where payments do not align with exact six-month intervals. If a loan starts on the 15th of the month, the second payment lands six months later, but the day of the month might shift. Some lenders round to the nearest business day, which introduces a fractional day of interest. This is a minor issue in most consumer loans but it becomes significant in commercial lending where the principal is large enough that even a fraction of a percent matters. I learned to flag these edge cases early in any agreement review rather than pretending they would resolve themselves.
There is also a limitation worth noting. Semiannual compounding sounds like it should be more accurate than annual compounding, and it is, but it is not the most common method in modern retail finance. Most consumer loans use monthly compounding, and many bonds use semiannual coupons precisely because of tradition rather than mathematical superiority. If you are modeling a real-world financial product, check the actual terms before assuming semiannual applies. The nominal rate and the compounding frequency are separate pieces of information, and conflating them is a reliable way to produce incorrect results. For situations where semiannual methods are insufficient, moving to monthly or continuous compounding usually provides better accuracy. The formula changes slightly, but the logic remains the same. Continuous compounding uses the natural exponential function instead, and monthly compounding divides the annual rate by 12 rather than by 2. Knowing when to switch between these approaches is what separates someone who can plug numbers into a formula from someone who actually understands what the numbers represent.