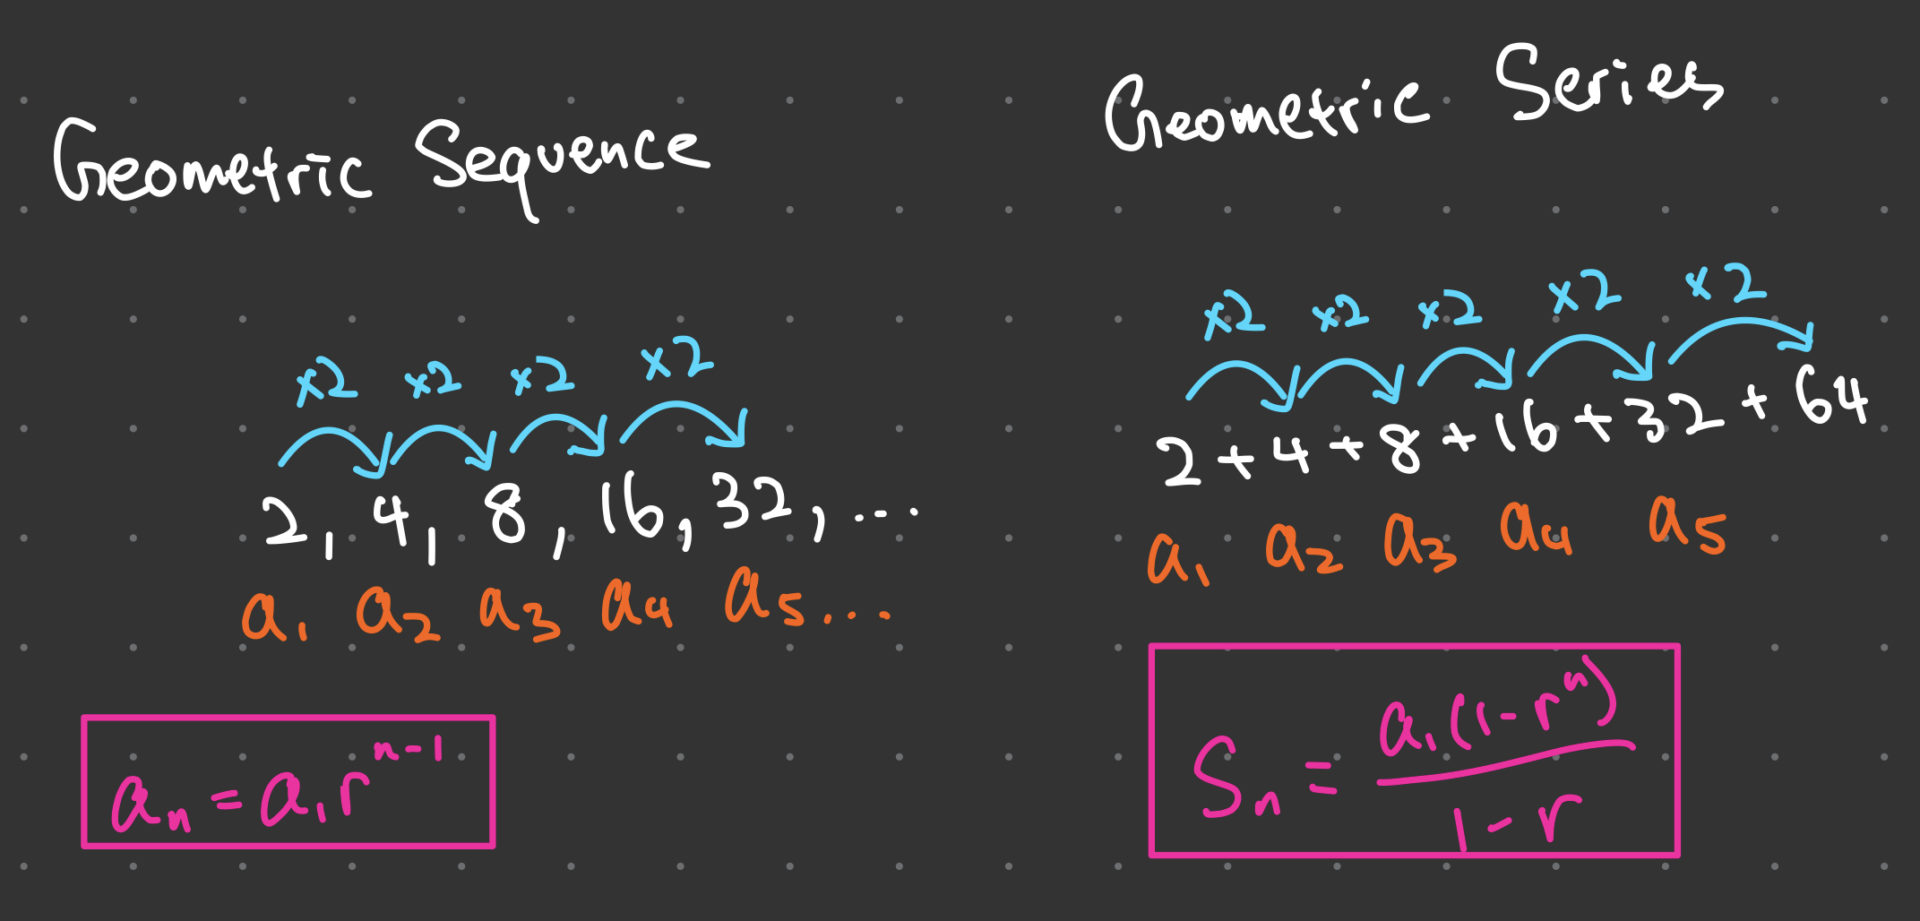
Understanding Sequence And Series Mathematics
I have been working with sequences and series for about twelve years now, mostly in financial modeling and signal processing. The math itself is straightforward until you start applying it to real problems, which is where things get messy. Let me walk through how this actually works in practice rather than reciting textbook definitions. A sequence is simply an ordered list of numbers. That's it. A series is the sum of those numbers. The distinction matters more than people realize because convergence behavior can be completely different between the two even when they come from the same source. I once spent three days debugging a financial model only to discover the infinite series diverged while the underlying sequence converged perfectly fine. That kind of mismatch does not show up in unit tests unless you specifically check for it.
Common Pitfalls When Working With Sequence And Series Mathematics
The ratio test is your first stop for checking convergence, but it has blind spots. When the limit equals exactly one, the test tells you nothing. I had a colleague who wasted weeks on a differential equations problem because he assumed divergence from a failed ratio test when the series actually converged conditionally. The root test works better for factorials and exponentials. The Raabe-Duhamel test handles that edge case where ratio and root tests both return one. Another thing nobody warns you about is alternating series. The alternating harmonic series converges to ln(2), but reordering its terms changes the sum entirely. Riemann rearrangement theorem proves this formally. In practice, this means your numerical implementations can produce different results depending on the order you process terms. I learned this the hard way when a Monte Carlo simulation gave different convergence rates based on term ordering. Sorting terms by magnitude before summing usually fixes this, though it adds computational overhead.
Practical Applications and Methods
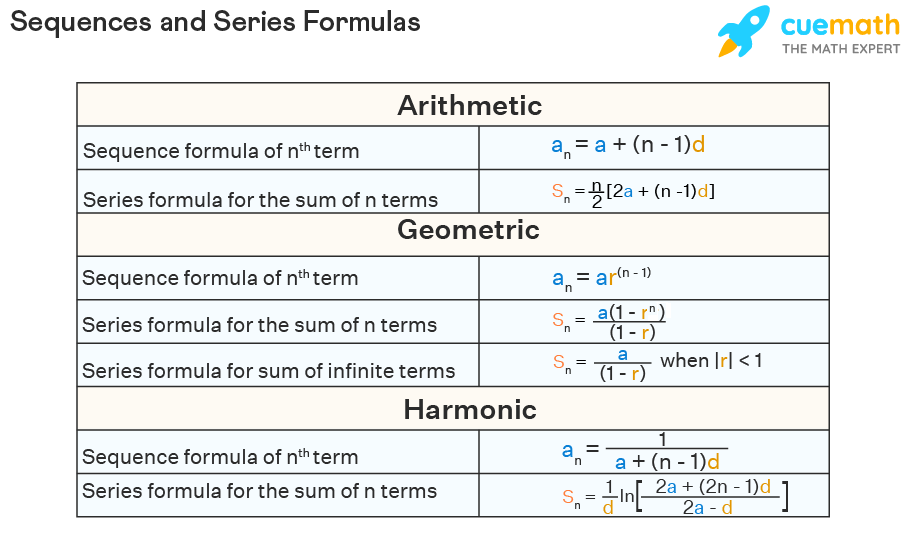
Taylor series expansions are probably the most commonly used application outside pure mathematics. Approximating sine, cosine, and exponential functions this way lets computers compute these values without special hardware. Modern processors use polynomial approximations through minimax algorithms rather than raw Taylor series because the error distribution is more uniform across the interval. Taylor series work well near the expansion point but diverge quickly elsewhere unless you use techniques like Taylor-Sarrus remainder estimation. Fourier series convert periodic functions into infinite sums of sines and cosines. This is the backbone of signal processing, image compression, and partial differential equation solving. The convergence properties depend heavily on function continuity. Discontinuous functions create Gibbs phenomenon, those oscillations near jump discontinuities that never fully disappear regardless of how many terms you include. In practice, windowing functions reduce these artifacts but introduce frequency domain tradeoffs you need to manage. For geometric series, the sum formula S equals a divided by one minus r only applies when absolute value of r is strictly less than one. I see this mistake constantly in homework solutions and casual explanations. When |r| equals one, the series diverges. When |r| exceeds one, it diverges to infinity. The special case r equals negative one creates oscillation between positive and negative values without converging.
Get the Full Details

Tools and Resources
Symbolab, Wolfram Alpha, and Desmos handle sequence and series computations well for standard problems. Python libraries like SymPy provide symbolic computation for formal proofs. For numerical work, NumPy and SciPy handle large-scale series evaluations efficiently. I use a combination: SymPy for symbolic manipulation during derivation, then hand-optimized NumPy code for production implementations. The transition from symbolic to numerical typically takes me about twenty minutes for moderate complexity problems. When dealing with Sequence And Series Mathematics problems involving special functions, the Digital Library of Mathematical Functions provides comprehensive tables and identities. in DLMF Chapter 3 covers ratio test, root test, integral test, comparison test, limit comparison test, alternating series test, absolute convergence, and conditional convergence. Each test has specific applicability conditions that matter more than the test itself.
Advanced Edge Cases
Double series convergence requires careful handling. Fubini theorem allows swapping summation order only for absolutely convergent series. Conditionally convergent double series can produce different sums based on summation order. I encountered this when implementing a Green's function calculation where term ordering affected numerical stability. Diagonal summation usually provides better convergence properties than row-by-row approaches for these cases. Cesaro summation handles divergent series by taking the limit of average partial sums. Grandi series one minus one plus one minus one equals one half under Cesaro summation, though it diverges in the traditional sense. This technique appears in string theory and quantum field theory regularization. The method does not change the series itself but provides useful values in contexts where standard convergence fails. Power series radius of convergence calculations sometimes require combining multiple tests. When coefficients involve both factorials and exponentials, the ratio test might simplify while leaving ambiguous terms that need root test supplementation. I developed a workflow where I apply ratio test first, check for limit equals one, then switch to root test or Raabe test as needed. This reduces computation time significantly compared to trying single tests on complex coefficient expressions.
Asymptotic analysis of series partial sums reveals behavior that convergence tests cannot. Stirling approximation for factorial terms helps determine growth rates in series with combinatorial coefficients. The approximation becomes accurate quickly enough that using it directly in series evaluations often produces acceptable results for engineering applications, though formal proofs require additional justification.

When Standard Methods Fail
Some series resist all standard convergence tests. The series with terms one over n times sine of n lacks simple closed forms and exhibits complicated behavior. Numerical evaluation with increasing partial sums shows apparent convergence, but proving it rigorously requires advanced techniques like Dirichlet test or exponential sum estimates. In practice, I rely on numerical evidence combined with partial summation methods for these pathological cases. Euler-Maclaurin formula connects series to integrals and provides asymptotic expansions for partial sums. This approach works well when direct summation becomes computationally expensive. The formula introduces Bernoulli numbers and derivative terms that can be computed efficiently. I use this method when evaluating series with millions of terms where direct computation exceeds available memory. Contour integration and residue calculus provide exact values for certain infinite series. The series one over n squared equals pi squared over six emerges from calculating residues of cotangent functions. This technique extends to many series involving reciprocal powers and rational functions. The method requires complex analysis background but produces closed forms that numerical methods cannot match in precision.
For practical implementation, I maintain a reference collection of standard series expansions and convergence results. Common Taylor series for elementary functions, Fourier series for periodic waveforms, and zeta function values provide quick lookup during problem solving. Having these organized reduces time spent deriving from first principles while maintaining accuracy through verification against known results.