Writing a business plan for a small grocery store
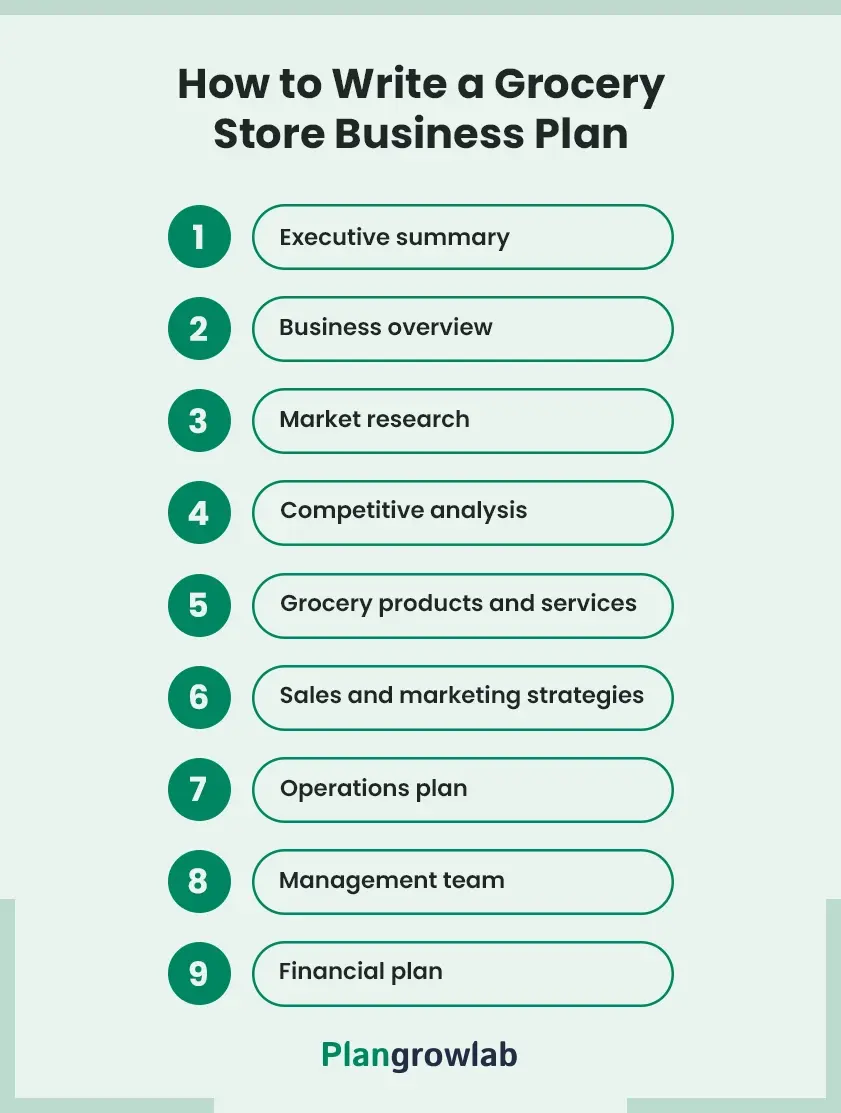
A Small Grocery Store Business Plan is mostly about convincing yourself that the math works before you hand it to a lender. Most people treat it like a school project. It isn't. It is a living document that should get ugly fast, because the moment you finish a clean draft, the numbers are already lies. I wrote my first one in 2009 for a 1,200-square-foot corner market in Cleveland. The banker liked it. The bank account did not. Forget the executive summary. Start with inventory turnover and gross margin by category. That single piece of data will rewrite everything else you planned. If you do not know how fast milk moves compared to organic rice crackers, you are flying blind. I learned this the hard way when a supplier offered me a 14 percent discount on a case lot of canned goods that sat on my shelf for eleven months. The discount cost me $3,200 in carrying cost and missed revenue from the floor space it occupied. Your plan needs real content in three areas: market analysis, operations, and financial projections. Everything else is decoration. Lenders skim past the mission statement and the management team bio. They stop at your break-even analysis and your cash flow forecast. That is where you need to be precise.
For market analysis, do not write about the "growing demand for healthy foods." Write about the three competing stores within a half-mile radius, their square footage, their pricing strategies, and why your location has a foot traffic advantage they do not. I pulled count data from a portable counter I rented for two weekdays and one weekend day. Six hours of work. It was more useful than any demographic report from the Census Bureau.
Operations section realities
Most first-time grocery operators underestimate staffing. A 2,000-square-foot store with a deli counter needs at minimum three part-time workers and one full-time shift lead. That is before you account for breaks, sick days, and turnover. Turnover in grocery retail runs around 60 percent annually. Build that into your labor budget or your plan will fail within the first fiscal year. My deli counter experiment taught me something nobody tells you. Keeping a hot food case running adds roughly $800 a month in utility costs alone, not counting labor, waste, and licensing. I calculated that at a 35 percent margin on prepared foods, I needed $2,286 in monthly sales just to cover the utilities. That meant moving about 45 prepared meals a week, every week, rain or shine. It never happened. I removed the deli case after month four and the store became profitable.
Get the Full Details
Financial projections that will not embarrass you
Start your revenue model from the ground up using a formula most beginners skip. Take your available square footage, subtract shelving and fixtures, and calculate sellable floor space. Multiply that by average sales per square foot for your trade area. Independent grocery stores in the Midwest typically generate between $400 and $600 per square foot annually. A 2,000-square-foot store with 1,400 square feet of sellable space should expect between $560,000 and $840,000 in annual revenue in year one if it is in a decent location. That is the ceiling, not the floor. Your first-year reality will probably land closer to 60 percent of that number. Budget accordingly. Cost of goods sold for a small grocery store typically runs between 28 and 33 percent. Convenience items and prepared foods push that lower. Bulk dry goods push it higher. Keep a spreadsheet that tracks COGS by category each week. When you see the snack aisle climbing toward 38 percent, that is your warning light. I once missed a spike in produce spoilage because I was looking at aggregate numbers. The overall COGS stayed at 31 percent, but the produce category had hit 44 percent and was dragging the rest down. Wasting three cases of basil a week adds up to $1,200 a year. Nobody notices until they review the category P&L.
Common pitfalls in the pro forma
Two mistakes kill most small grocery store plans. The first is assuming you will achieve 100 percent shelf availability immediately. New stores run at about 72 to 78 percent capacity for the first sixty days as supply relationships stabilize. Your launch quarter revenue should reflect that gap. The second mistake is ignoring the equipment replacement reserve. Refrigeration compressors fail. Ice machines break. Conveyer belts in the produce section wear out. Set aside 3 to 5 percent of gross revenue annually for capital replacement. For a store doing $600,000 in sales, that is $18,000 to $30,000 a year sitting in a separate account. When your walk-in cooler compressor goes in month fourteen, you will either have the money or you will not.
How to structure the document itself
Keep it between fifteen and twenty-five pages. Anything longer gets ignored. Use clear headings. Include a one-page summary at the front that states your location, square footage, estimated opening date, total startup capital required, and projected year-one revenue and net profit. Lenders read that page first and sometimes stop there. Attachments should include your lease agreement, any letters of intent from suppliers, equipment quotes, and a site plan showing the store layout with measured sections. A floor plan with measurements signals that you have actually thought about how customers move through your space. I sketched mine in a notebook and then measured the actual store twice. The measurements were off by eight inches on the original sketch. The error did not change the plan materially but fixing it early prevented a costly mistake with refrigeration placement.
A note on lenders and grants
If you are applying for an SBA microloan, the lender will want to see personal financial statements for every owner with 20 percent or more stake. Prepare those documents before you submit the plan. Having them ready separately cuts your application time by about a week. Community development financial institutions and some state agriculture departments offer grants specifically for independent grocery stores in food desert areas. Those programs often require a slightly different format focused on community impact rather than pure financial return. Check the program guidelines before you invest time in one version over the other. A business plan does not fix a bad location. I have seen three stores in the same strip mall where two failed within eighteen months and the third survived only because it had exclusive parking. The plan was identical across all three. The location was the variable. Do not assume a well-written document will compensate for low visibility, poor access, or a neighborhood undergoing rapid commercial displacement. The plan also does not replace a working relationship with a wholesaler. I spent six weeks negotiating with a regional food distributor before securing terms that allowed me to order in pallet quantities instead of case quantities. That one conversation improved my margins by roughly 2.1 percent across fifteen product categories. It was worth more than any section I wrote in the financial projections.
Keep the plan updated monthly for the first year. The numbers you wrote in October are wrong by December. That is normal. The value is in tracking the variance and adjusting your assumptions, not in preserving a document that looks good on paper.