What Actually Happens When You Use This
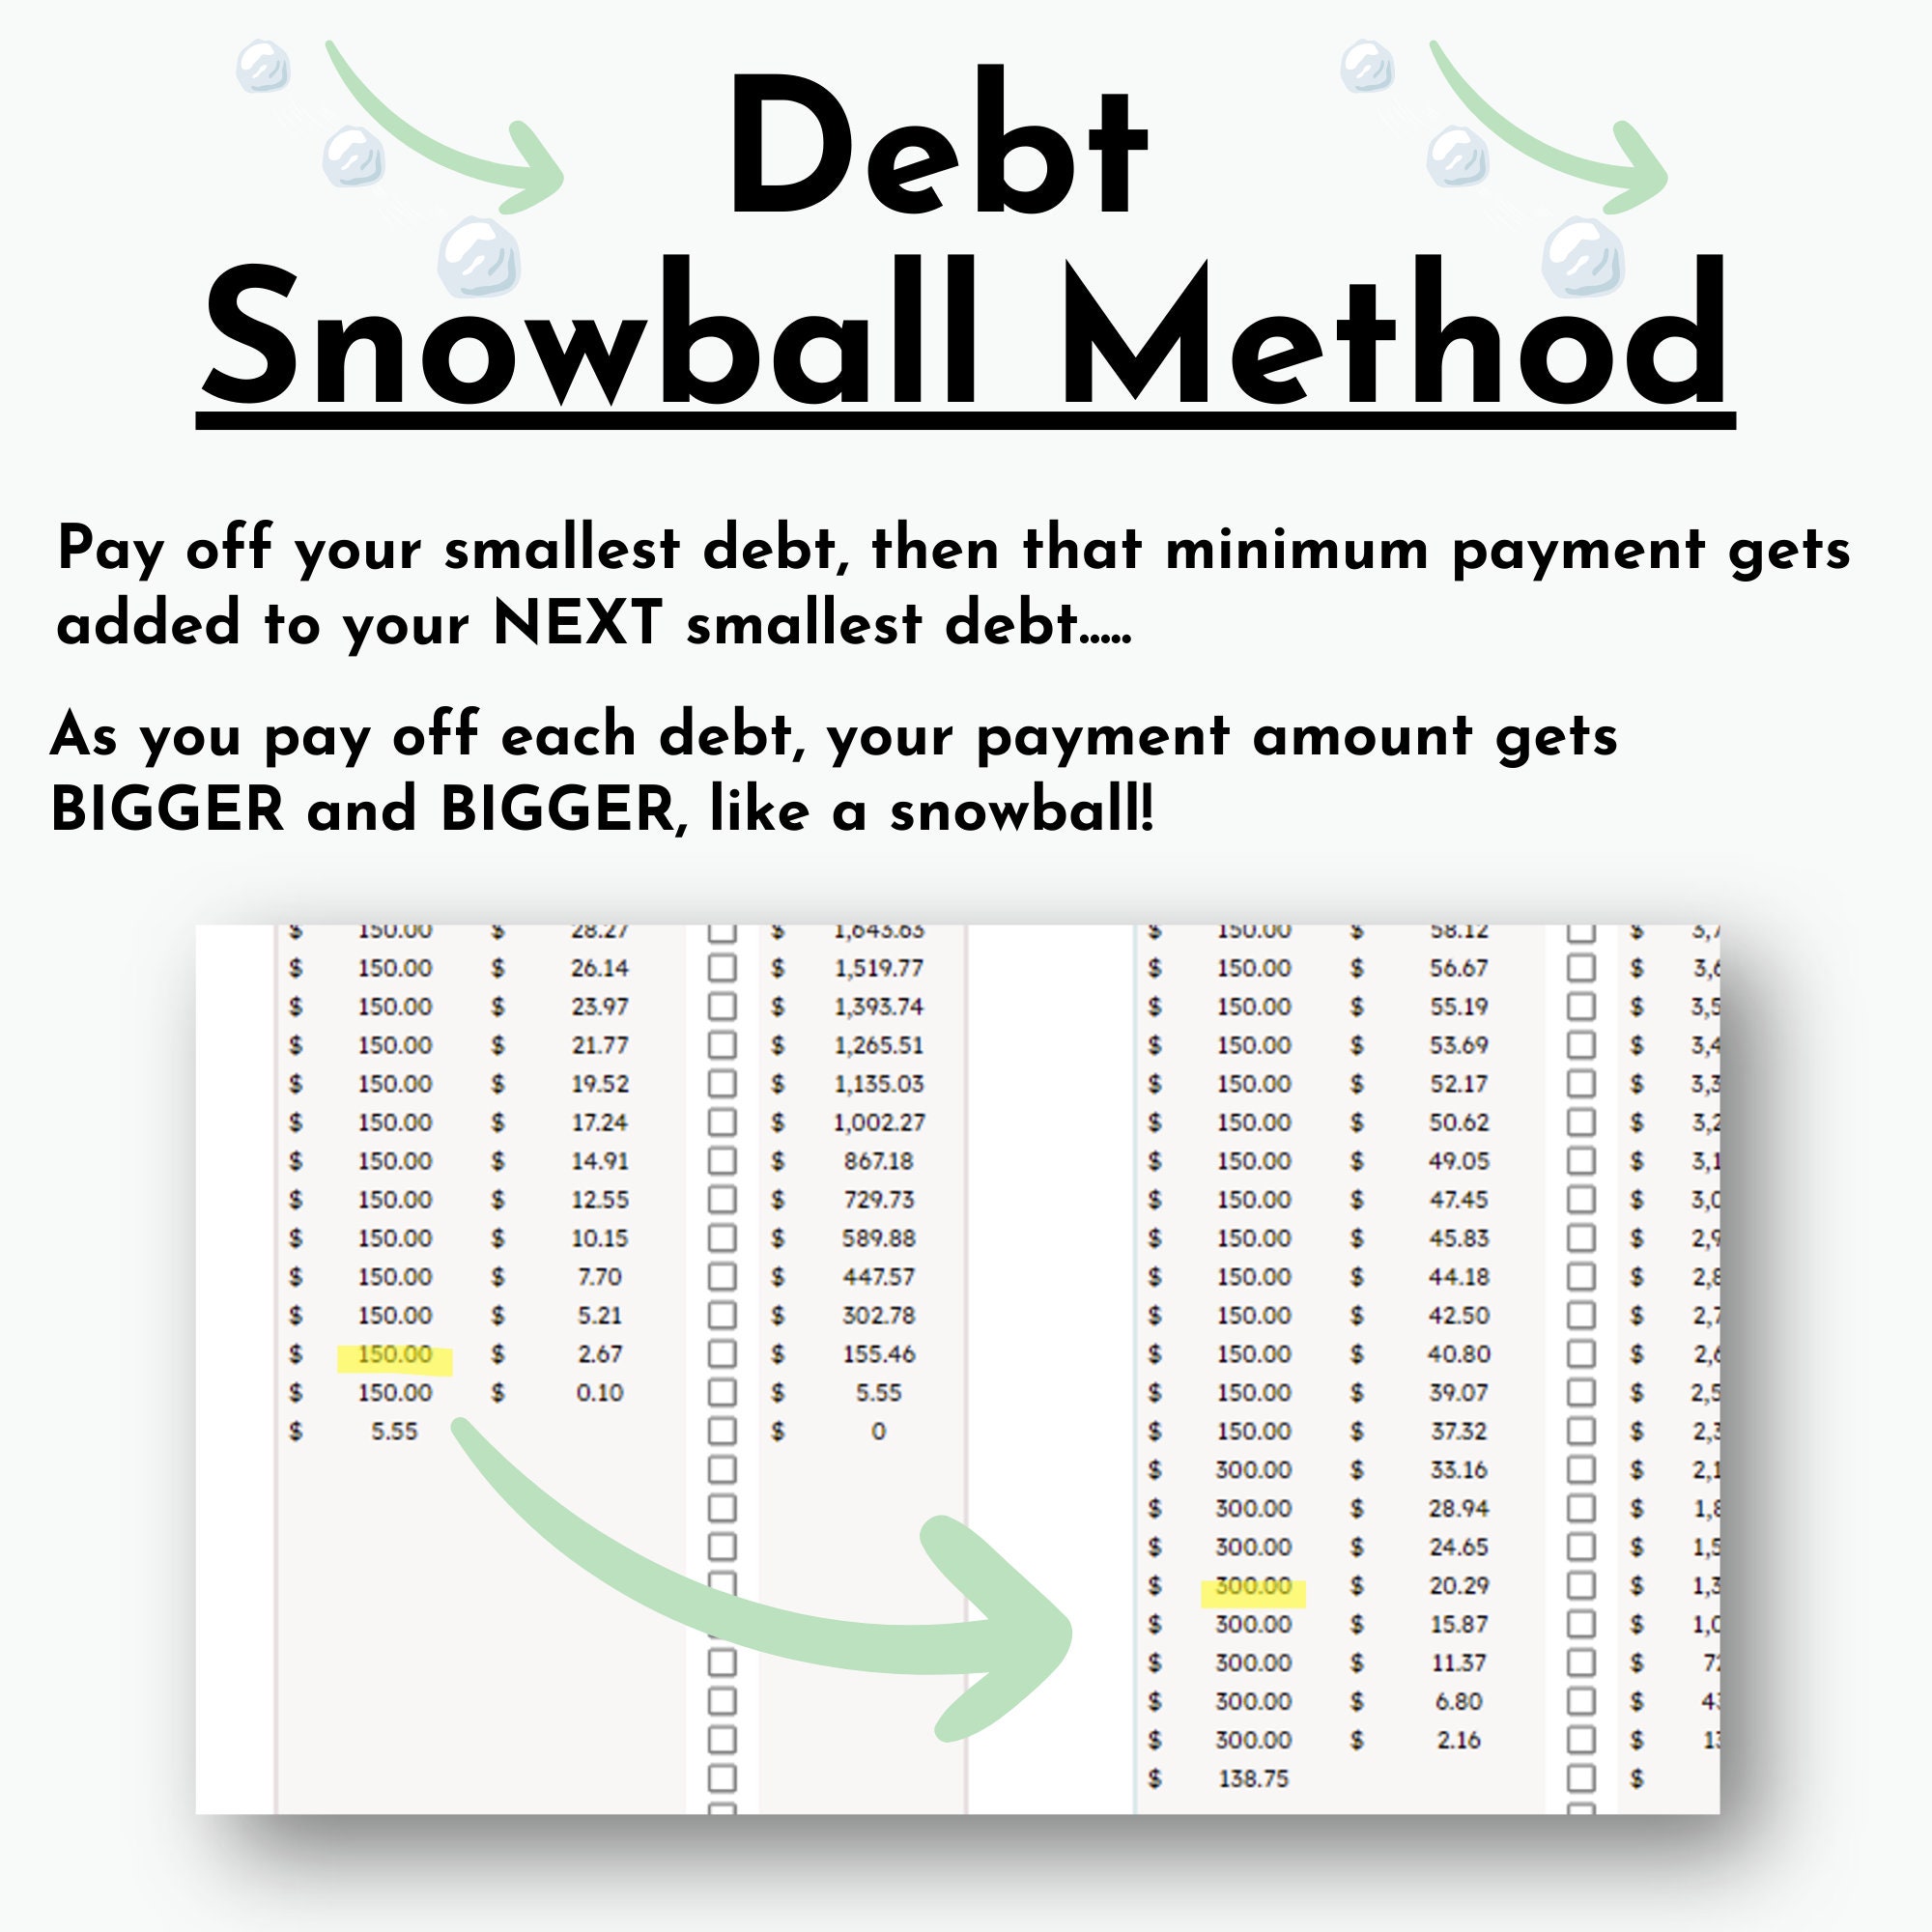
The snowball method is a debt payoff strategy where you list your debts from smallest balance to largest, make minimum payments on everything, and throw every extra dollar at the smallest one. Once that one is gone, you take the money you were paying on it and add it to the next smallest. It creates momentum. The psychological piece is real — people actually stick with it more often than the avalanche method (which targets highest interest first) because they see wins quickly. But here's what nobody tells you: the math and the motivation are two different things. A Snowball Method Calculator is just a tool that does the arithmetic so you stop fumbling with spreadsheets. You input your debts, your minimum payments, your extra monthly amount, and it spits out a payoff timeline. Done. That's it. The hard part is deciding which debts to include and whether your assumptions are realistic.
Using a Snowball Method Calculator
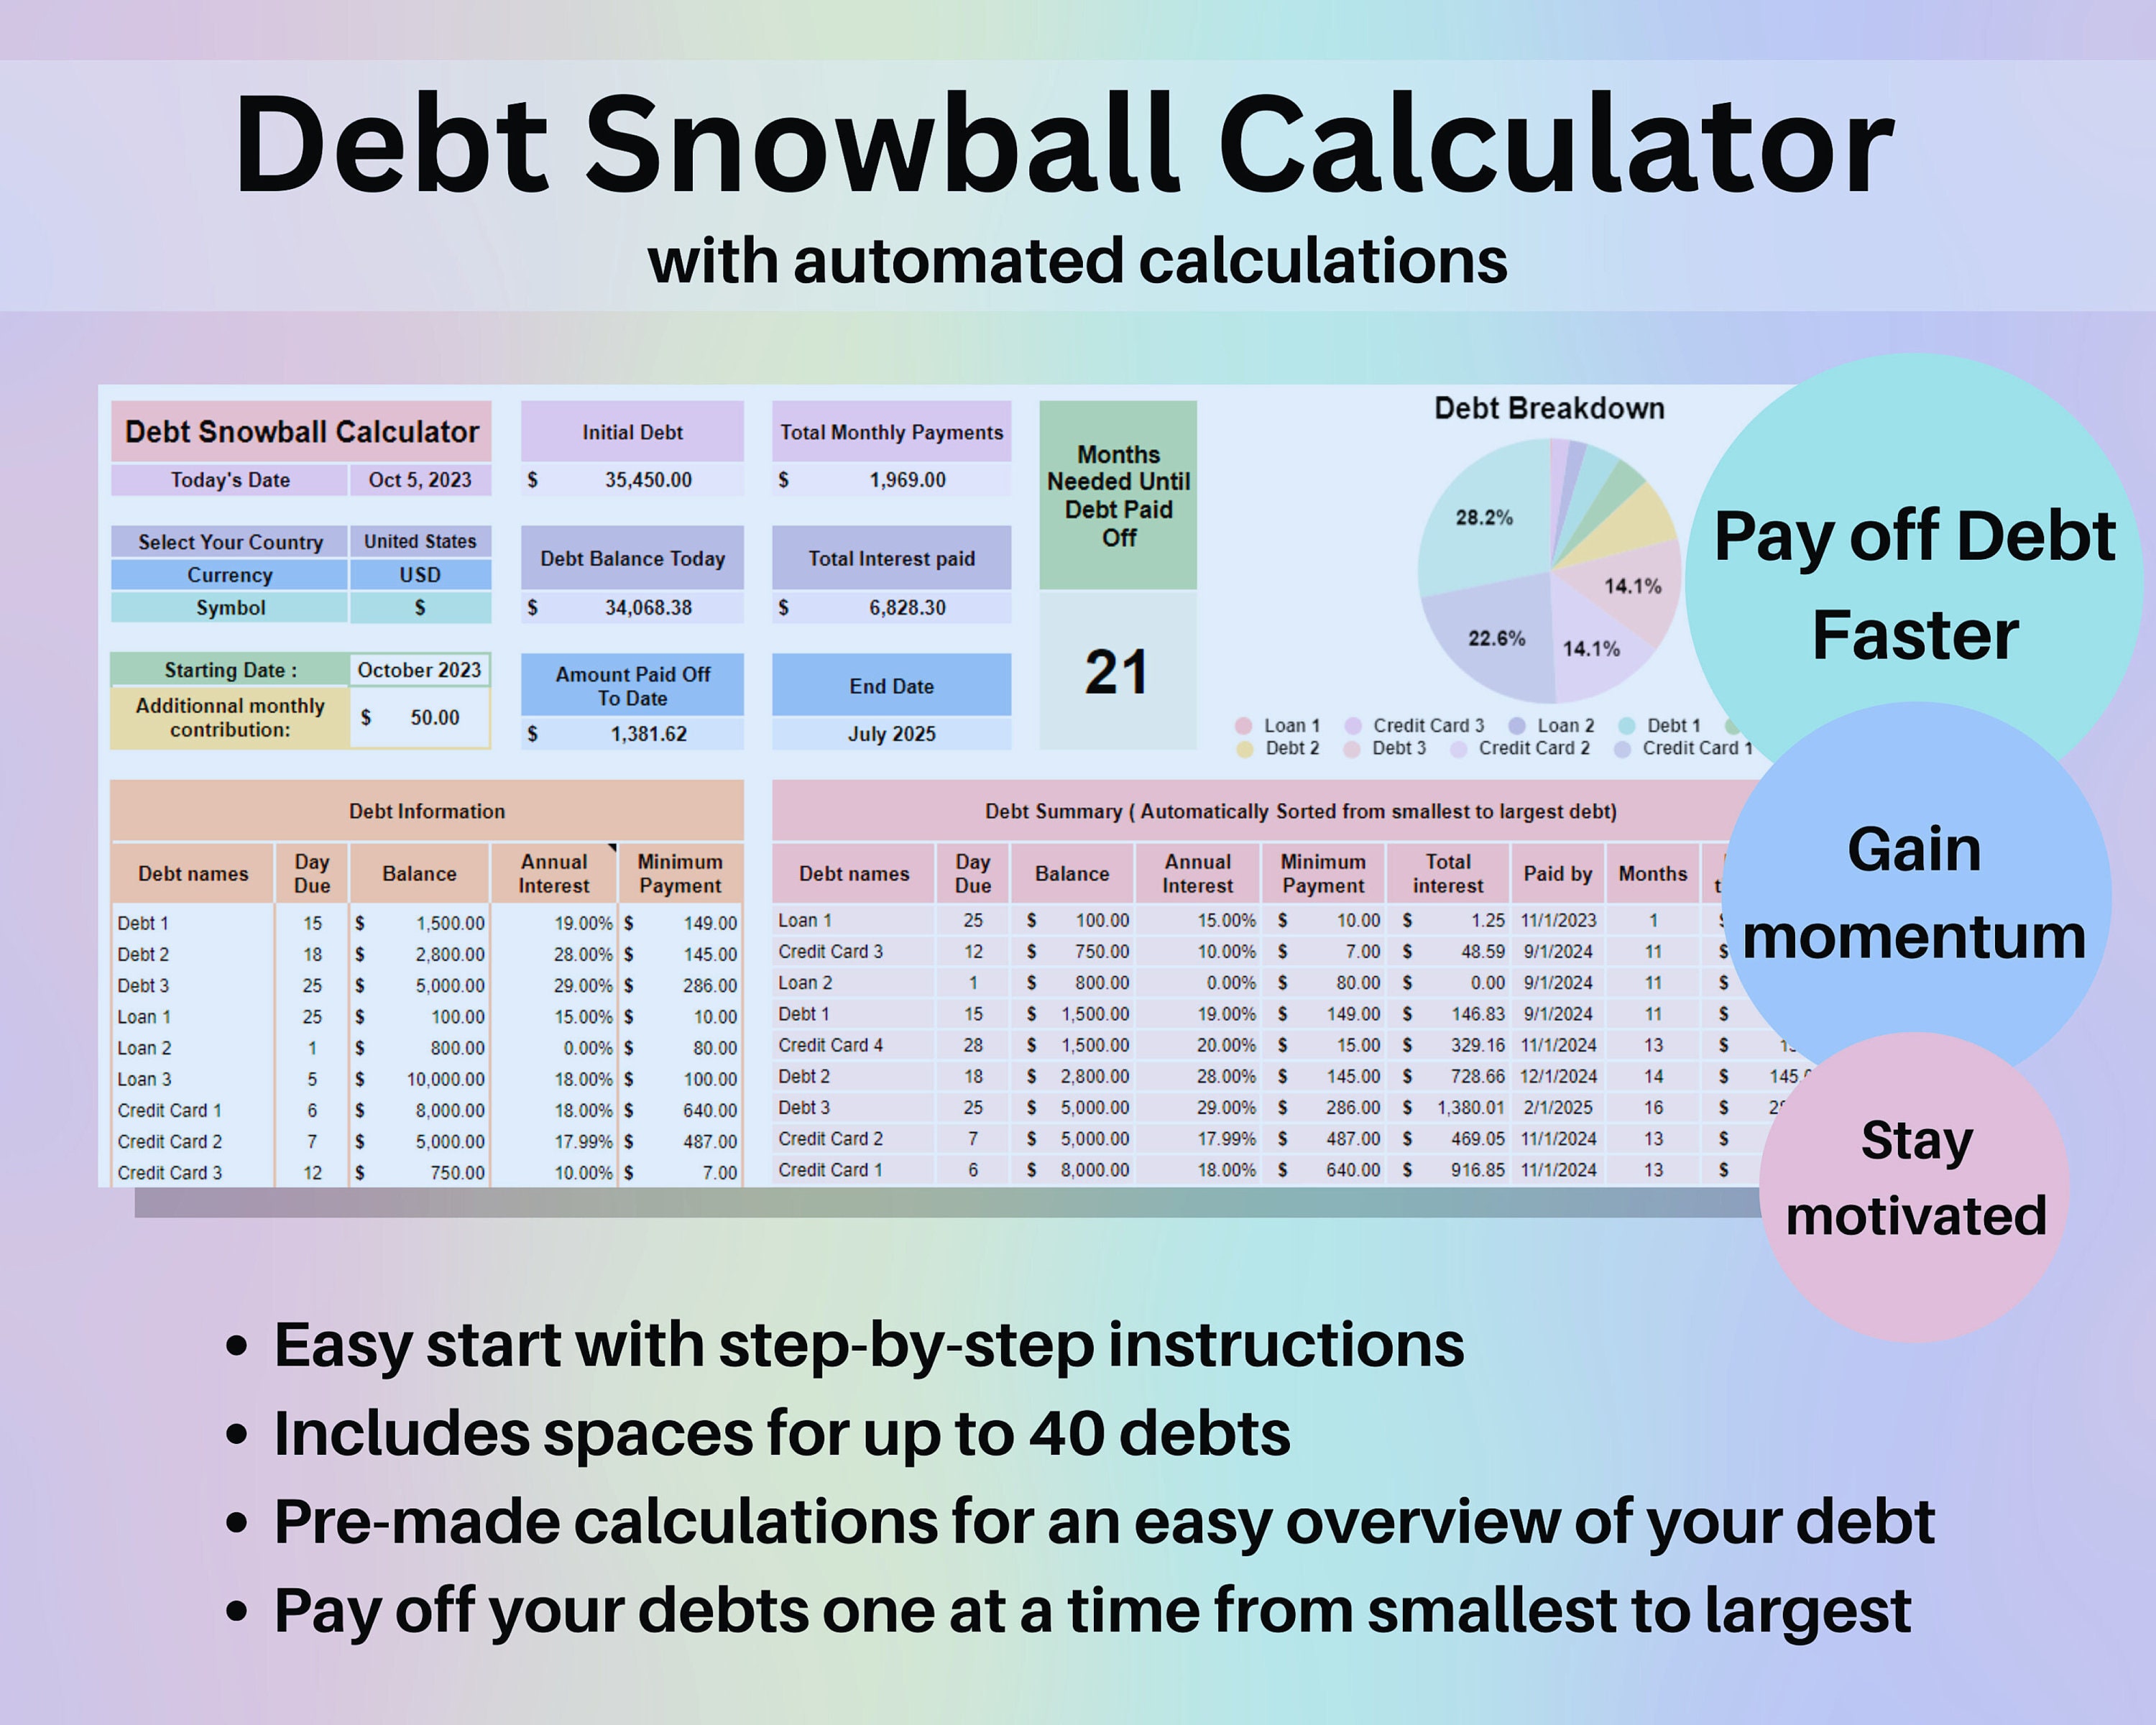
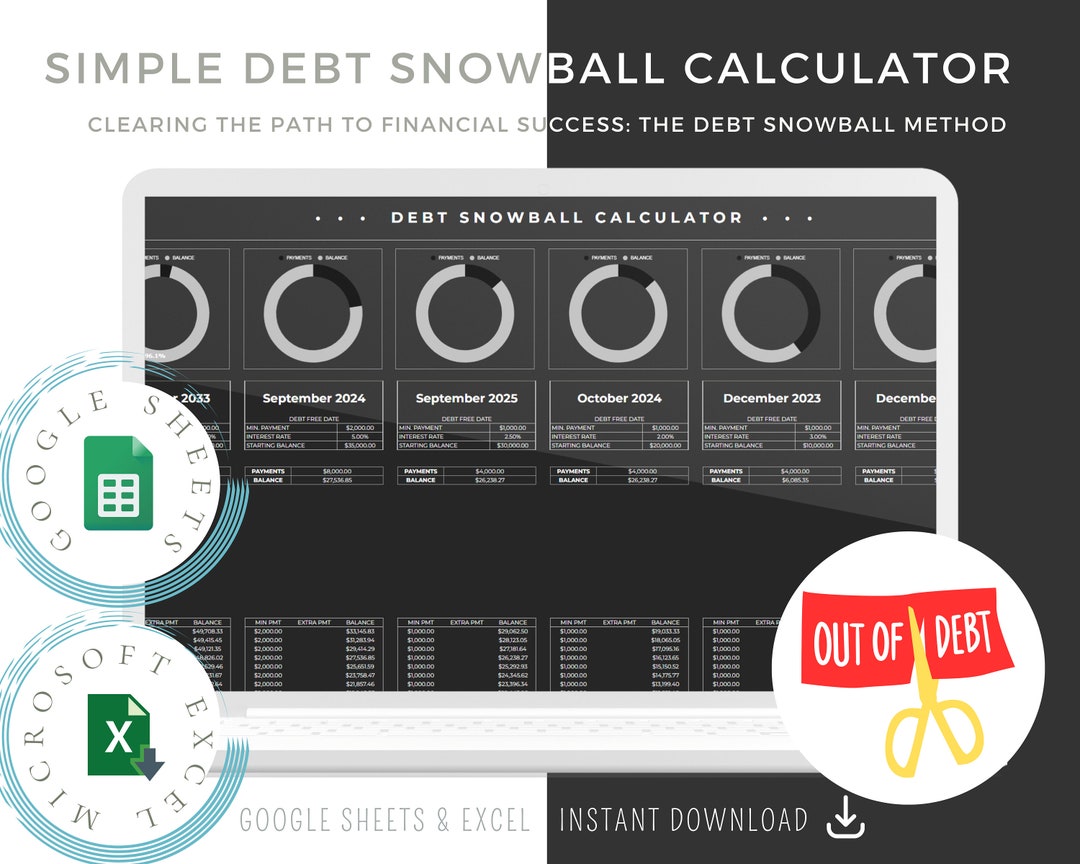
I built my own calculator years ago because the free ones online had terrible edge-case handling. Most of them just assume a flat monthly extra payment and ignore things like credit card rewards rebates or balance transfer windows. When I started using one seriously for my own debts, I found that the generic calculators would give you a payoff date that was 3 to 8 months off from reality depending on how aggressively they assumed compounding. So I wrote something that lets you enter each debt individually with its own APR, minimum payment, and current balance, then applies your extra payment in the right order. Here's the basic workflow if you're just starting out: First, list every debt you have. Not the ones you "might" pay off — the ones that actually exist right now. Credit cards, personal loans, student loans, that medical bill you've been ignoring. For each one, write down three numbers: the current balance, the interest rate (APR), and the minimum monthly payment. Don't round. If your balance is $1,847.32, write $1,847.32. The calculator will handle the decimals; you don't need to.
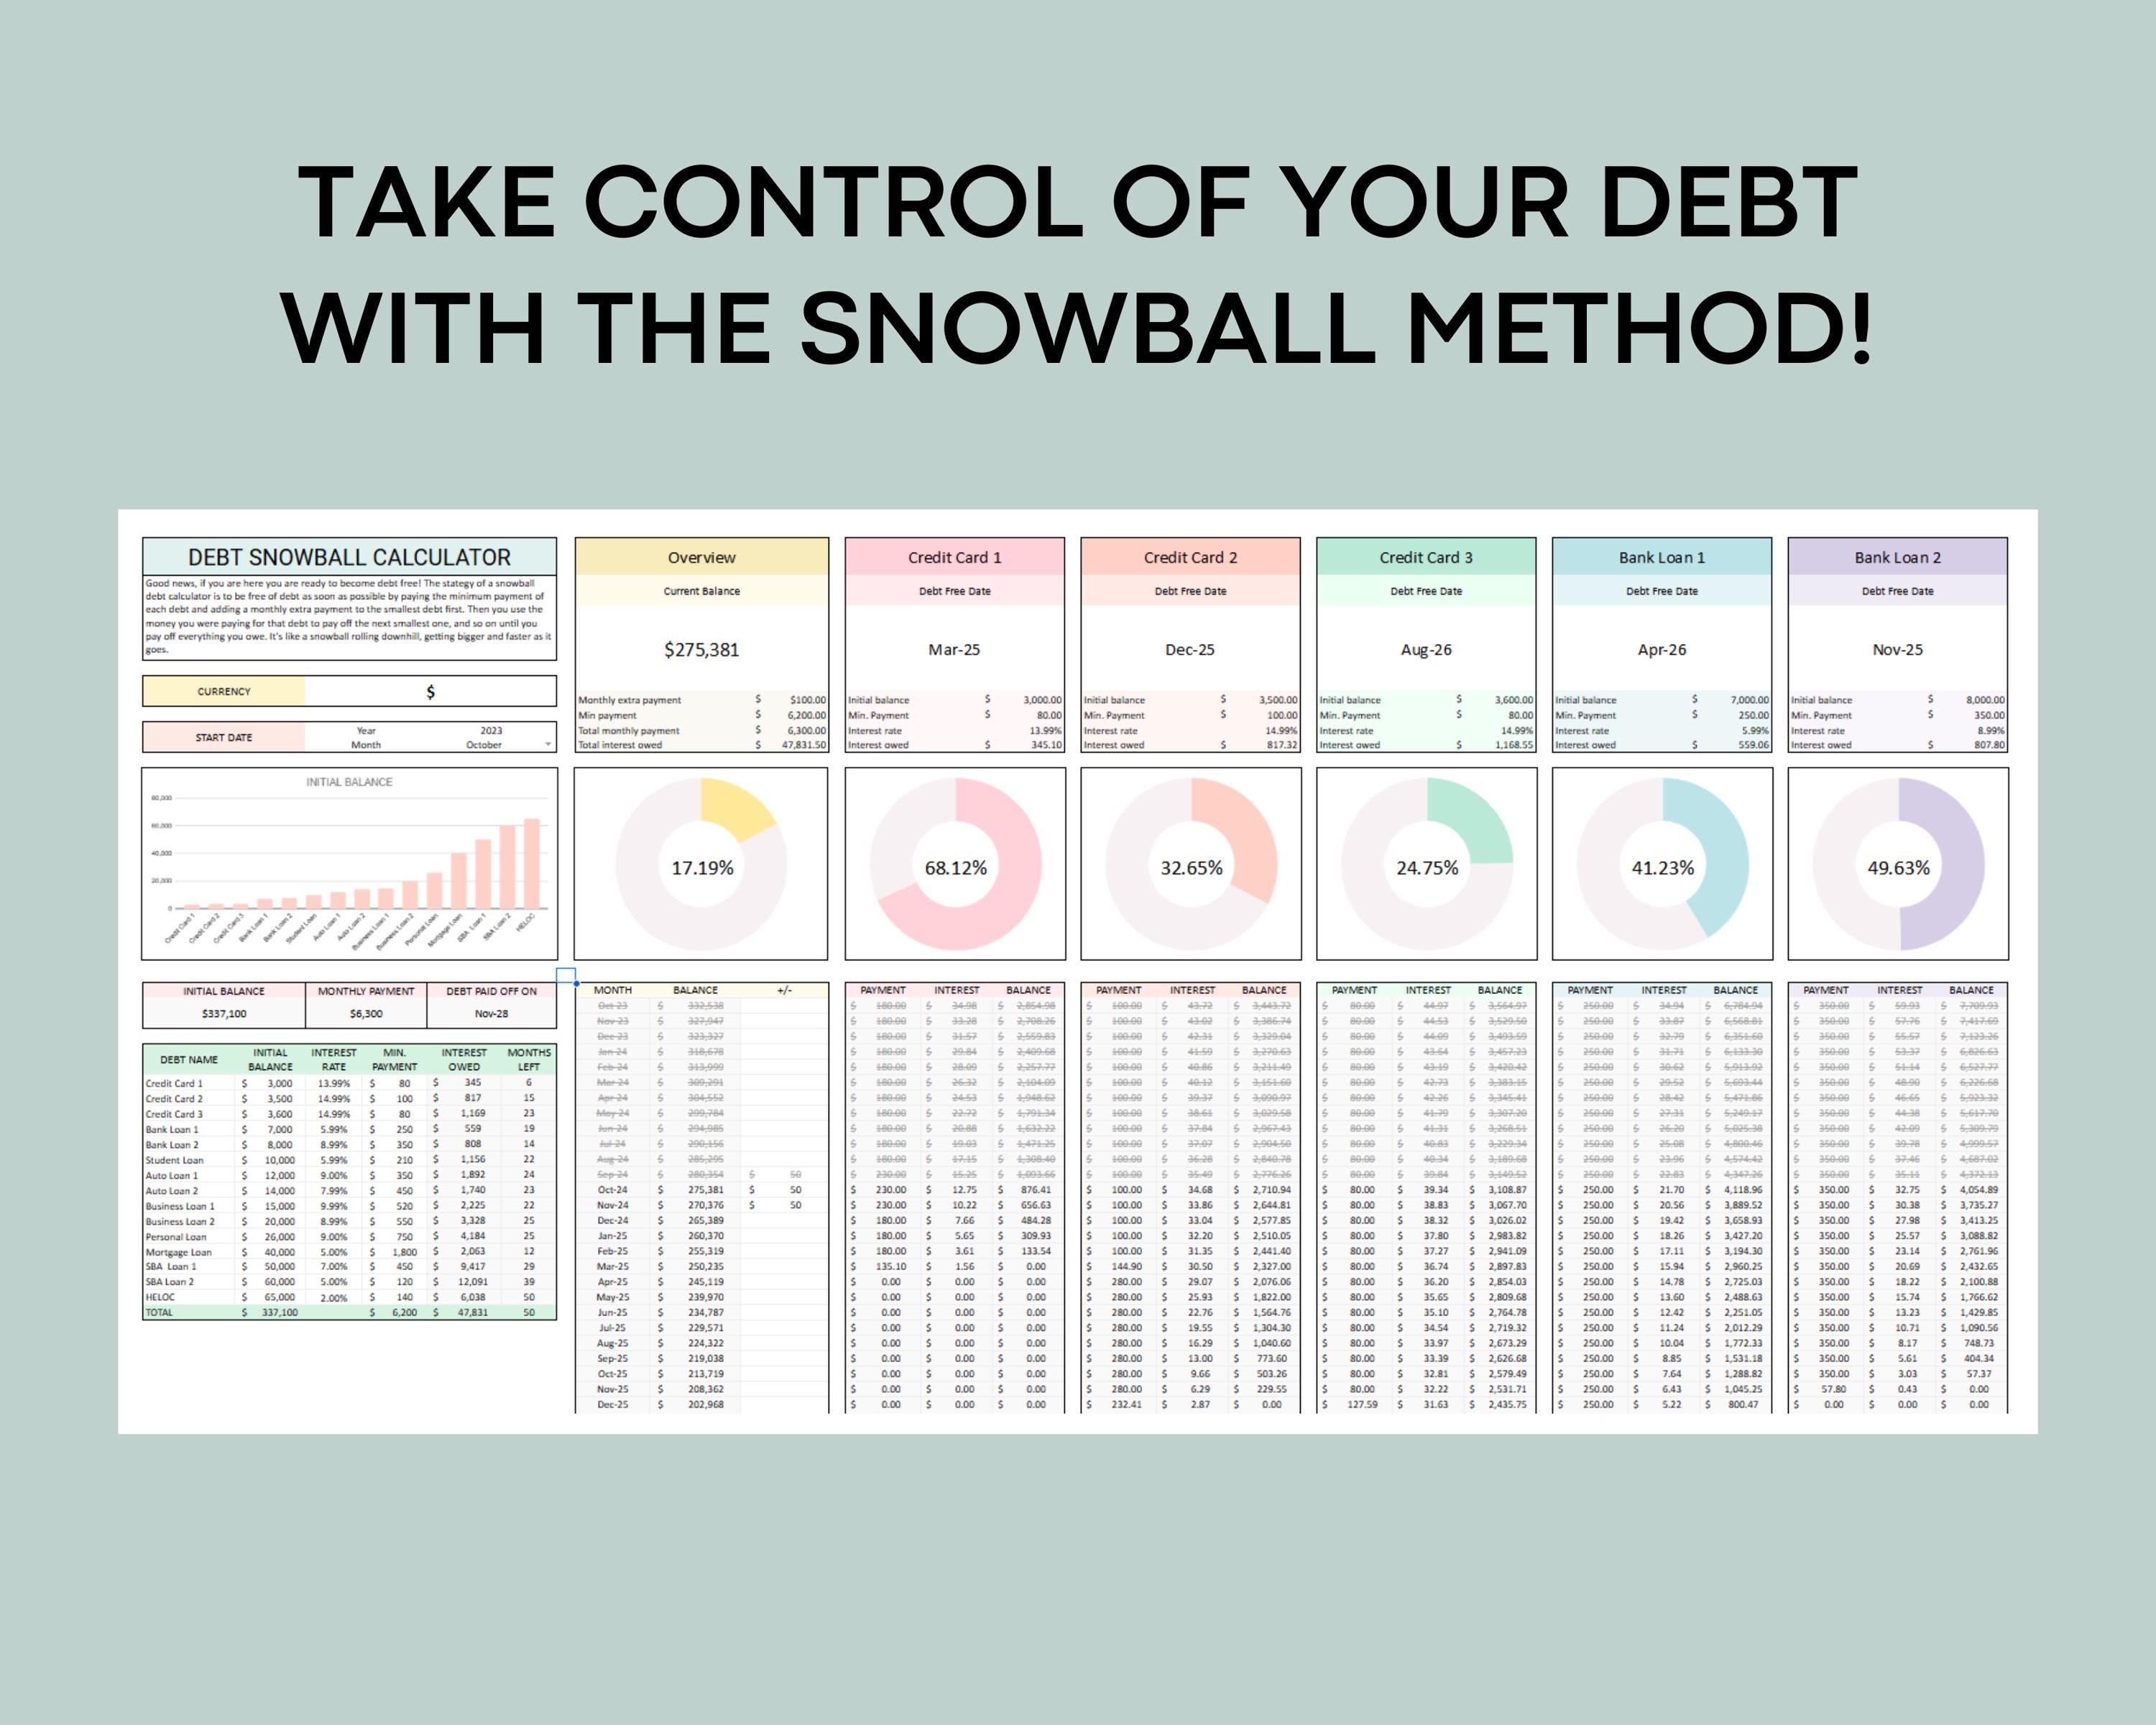
Next, decide how much extra you can throw at debt each month. Be honest. If you say $500 but your actual surplus is $220 after rent and groceries, you're just building false confidence. I learned this the hard way. One of my clients once told me she was putting $800 extra per month toward debt. When I pulled her bank statements, she was putting in about $190. The calculator said she'd be debt-free in 22 months. Reality put it at 41. That gap isn't a calculator problem — it's a planning problem. Once you have your list and your extra payment number, plug everything into the calculator. It should sort your debts by balance, smallest first, apply the snowball payment cascade month by month, and show you when each debt hits zero. The output should include a total payoff date and total interest paid. If it doesn't show total interest, that's a bad calculator. Use a different one.
Get the Full Details
The Hidden Problems With These Calculators
Most calculators online treat minimum payments as fixed forever. They don't account for the fact that as a balance drops, your minimum payment usually drops too. Some do model this correctly by recalculating the minimum each month based on the remaining balance and the amortization schedule of that specific debt. The difference can be significant over a multi-year payoff window. I ran a comparison once on a $12,000 combined debt portfolio — the simplified calculator said 38 months and $2,140 in interest. The proper one said 44 months and $2,680. That's a five hundred and forty dollar difference from a single modeling choice. Another issue is the treatment of interest compounding. Credit cards compound daily but are reported monthly. A well-built calculator should use daily periodic rates (APR divided by 365, applied to the average daily balance). Lazy ones use simple monthly compounding and it adds up over time. If you're comparing two calculators and they give you different payoff dates, check which compounding method each one uses. There's also the question of whether the calculator handles the "zero-balance pivot" correctly. When your smallest debt gets paid off, your extra payment amount jumps by the amount of that debt's minimum payment plus whatever you were throwing at it. Some calculators add only the minimum. Others add the full old payment. The correct approach is to add everything you were paying toward the closed debt — both the minimum and the extra. Otherwise you're underestimating your snowball.
I ran into a specific edge case that I still think about. A client had a medical debt at 0% that was about to enter collections. The original calculator I'd been using didn't let her mark any debts as paused or excluded, so it kept including that balance in the snowball order even though paying it down wasn't the priority. I modified the tool to allow a "deferred" status on individual debts, which removes them from the snowball sequence entirely while still letting you see what your timeline would look like with and without them. That feature alone made the difference between her choosing the right move and making a suboptimal one based on bad data.
When the Snowball Method Isn't the Right Call
The snowball method saves lives psychologically but it can cost you money mathematically. If you have a high-interest credit card at 24.9% and a student loan at 5.5%, the snowball method will have you paying off the student loan first if its balance is smaller. That's fine if you need the motivational wins. But you're paying roughly 20 percentage points more in interest than you would if you targeted the card first. On a $5,000 card balance and a $2,000 student loan with $600 in total monthly payment capacity, the avalanche method saves about $340 in interest and finishes 4 months sooner. The snowball finishes sooner only if the $2,000 loan clears fast enough to redirect that payment before the interest difference matters. So the real question isn't which method is better. It's which one you'll actually follow for eighteen to thirty-six months. If you know you'll quit when you don't see quick results, the snowball is the right choice even if it costs more. If you can stay disciplined regardless of the order, the avalanche is objectively cheaper. No can tell you that part. That's on you. I also run into people who try to use a Snowball Method Calculator for debts that shouldn't be in it at all. Things like a mortgage on a primary residence, or a cosigned loan where you have no control over the payment. Include those only if you're actually responsible for paying them. Otherwise you're just polluting your own data and making the output less useful. And don't include debts you're actively negotiating or in dispute — pause them until the terms are settled, then re-run the calculator with the new numbers.

What to Look for in a Tool
If you're going to use a calculator for this, here's what matters. It needs to accept individual debt entries with balance, APR, and minimum payment. It needs to recalculate minimums as balances drop. It needs to handle the payment pivot correctly when a debt closes. It should show you a month-by-month or at least year-by-year breakdown, not just a final date. And it should let you adjust your extra payment amount and immediately see how the timeline changes. Anything less than that is just a fancy interest calculator with a snowball skin on it. There are free versions scattered across personal finance sites. Some of them are decent. Most aren't. I've seen ones that cap the number of debts at five, ones that don't let you enter APRs above 20%, and ones that silently assume 30-day months for every single calculation. If you're doing this seriously, spend ten minutes validating the output against a manual calculation for one month. If the numbers don't match, walk away from the tool. The core insight is this: the calculator doesn't solve your debt. It just shows you what happens if you follow the strategy. The strategy is what matters. Pick the one that matches your behavior, not just your math. Then run the numbers, print the output, and get to work.