Figuring Out Your Dependent's Standard Deduction Doesn't Have to Be a Headache
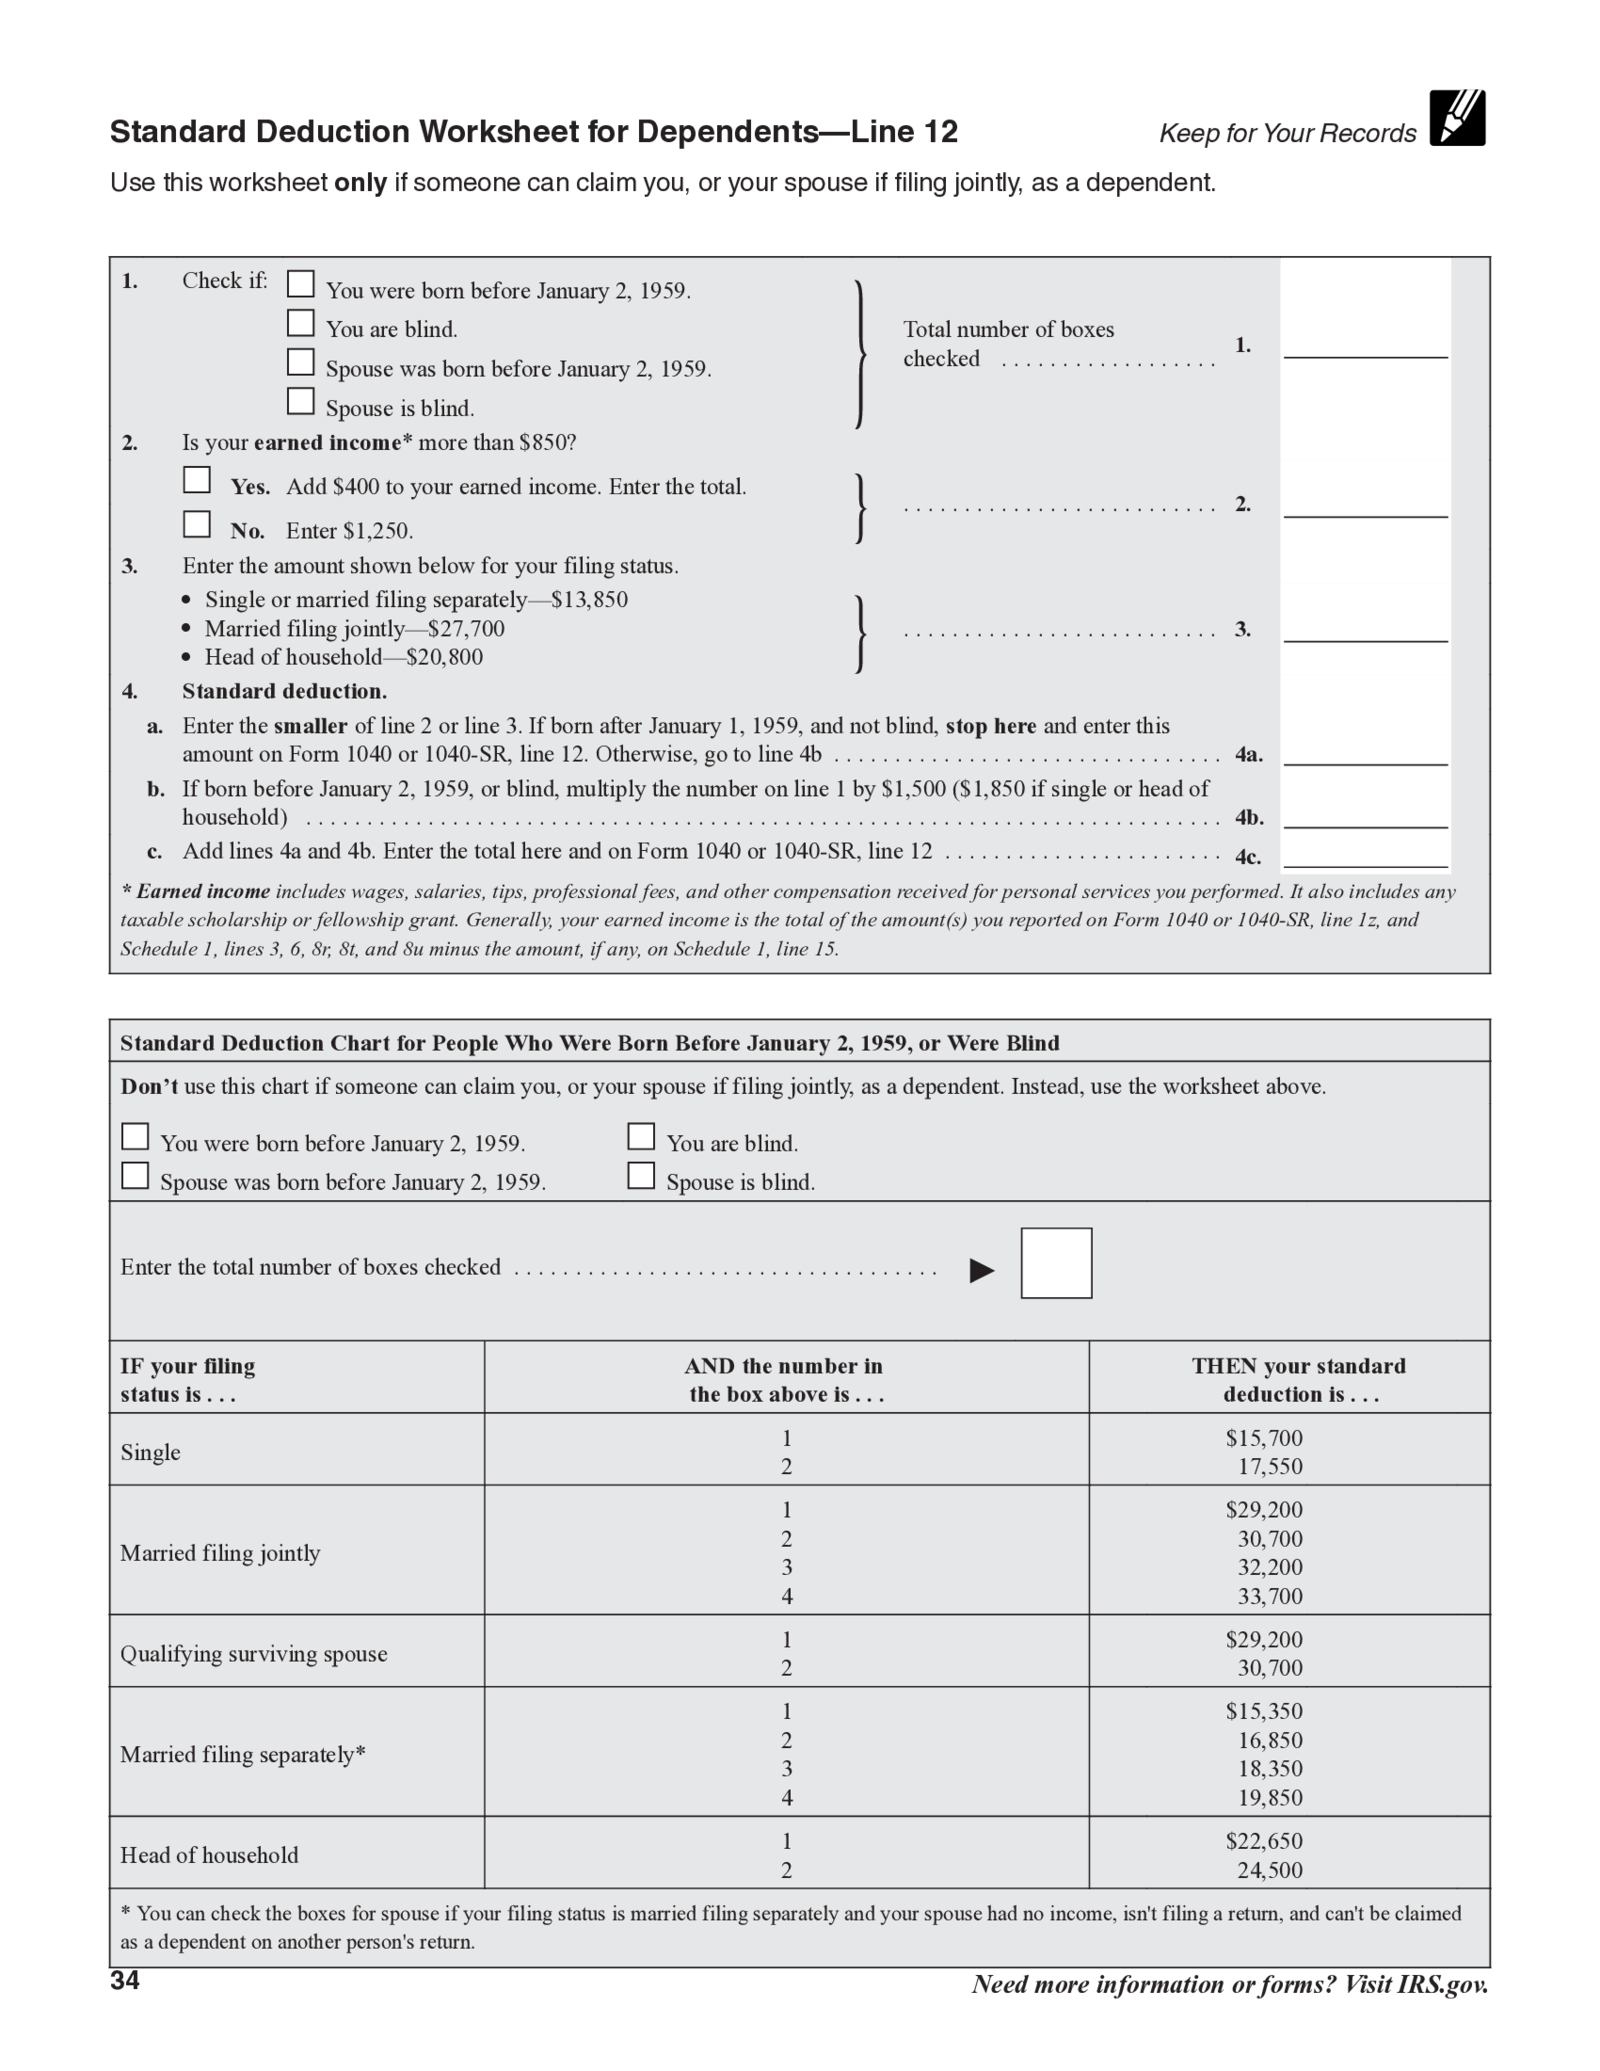
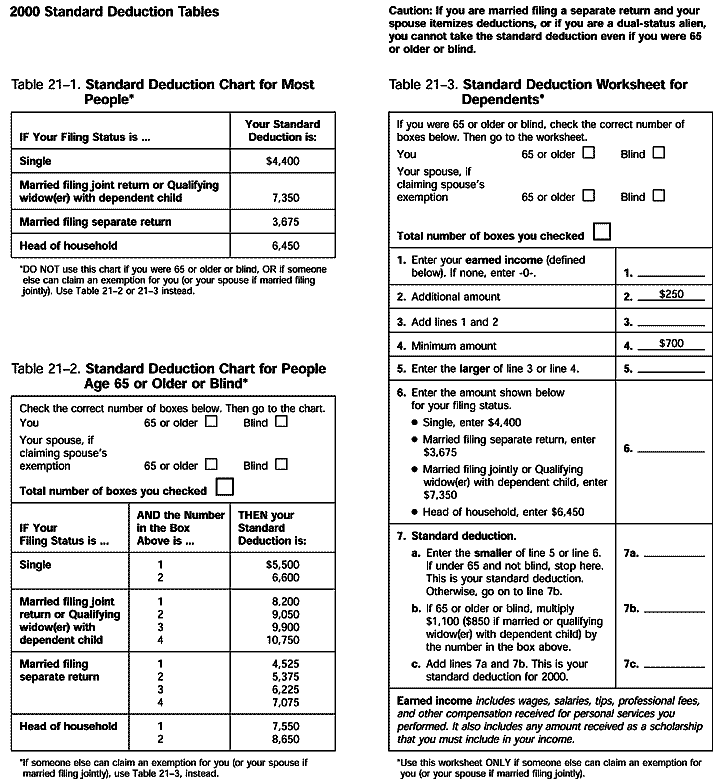
The standard deduction for dependents on a 2024 tax return is one of those things that sounds simple until you actually try to calculate it and realize there are a few moving parts. The basic rule is this: a dependent's standard deduction is the greater of $1,300 or their earned income plus $500, capped at the full standard deduction amount for their filing status. For 2024, that ceiling is $14,600 for single filers. That's it. But the worksheet exists because people keep messing it up, usually by forgetting which income counts and which doesn't. Here's how I run through it when I'm helping someone sort this out, or when I'm dealing with my own returns: Step 1: Determine the dependent's total earned income for the year. This means wages, salaries, tips, professional fees, and other compensation received for personal services. It does not include investment income, rental income, or passive activity income. If they had a W-2, just pull the Figure 1 total from it. If they were a contractor, it's the net from Schedule C.
Step 2: Add $500 to that earned income figure. Step 3: Compare that result to $1,300. Take the greater of the two. That's their standard deduction. Step 4: Make sure it doesn't exceed the regular standard deduction for their filing status. In 2024, a single dependent can't deduct more than $14,600 no matter how much they earned.
Let me give you a concrete example because numbers help. Say your kid turned 19 last year, worked part-time during the summer, and had $4,200 in W-2 wages. Add $500 and you get $4,700. That's their standard deduction. They'd file Schedule 1 and Form 1040, claim the standard deduction, and the math is straightforward. Now say they had zero earned income but did receive $800 in interest from a savings account. Their standard deduction is still $1,300 because that's the floor. But here's where it gets messy. I ran into a situation last spring with a client's son who was a college student. He had $6,000 in wages from a campus job, plus $2,300 in qualified tuition assistance that his university reported on his W-2 in Box 1 as taxable wages. He also had $400 in stock dividends. At first glance, you might think his earned income was $8,300 and just add $500 to get $8,800. But the tuition assistance, while reported as wages, isn't really earned income in the way the IRS means it for this calculation. The dividends aren't earned income either. So his actual earned income for the worksheet purpose was just the $6,000 from his job. The $500 gives you $6,500, which becomes his standard deduction. If you'd blindly added everything together, you'd have overstated it by $1,800 and that creates a mismatch with what shows up on the actual tax return. It cost me about forty minutes of back-and-forth with the client to untangle that one because he'd already tried doing it himself and got confused by the Box 1 total on his W-2. Another thing that trips people up is the interaction between earned and unearned income when it comes to the kiddie tax. If a dependent under age 19 (or a full-time student under 24) has more than $1,600 in unearned income for 2024, that excess is potentially subject to the kiddie tax at their parent's rate. This doesn't change the standard deduction calculation itself, but it changes the overall tax picture significantly. The standard deduction only shelters earned income. Unearned income above the $1,600 threshold is taxable separately. So a dependent with $3,000 in wages and $2,500 in investment income would have a $3,500 standard deduction from the wages, but the $900 of unearned income above the threshold gets taxed at the parent's marginal rate if the parent's rate is higher.
Get the Full Details
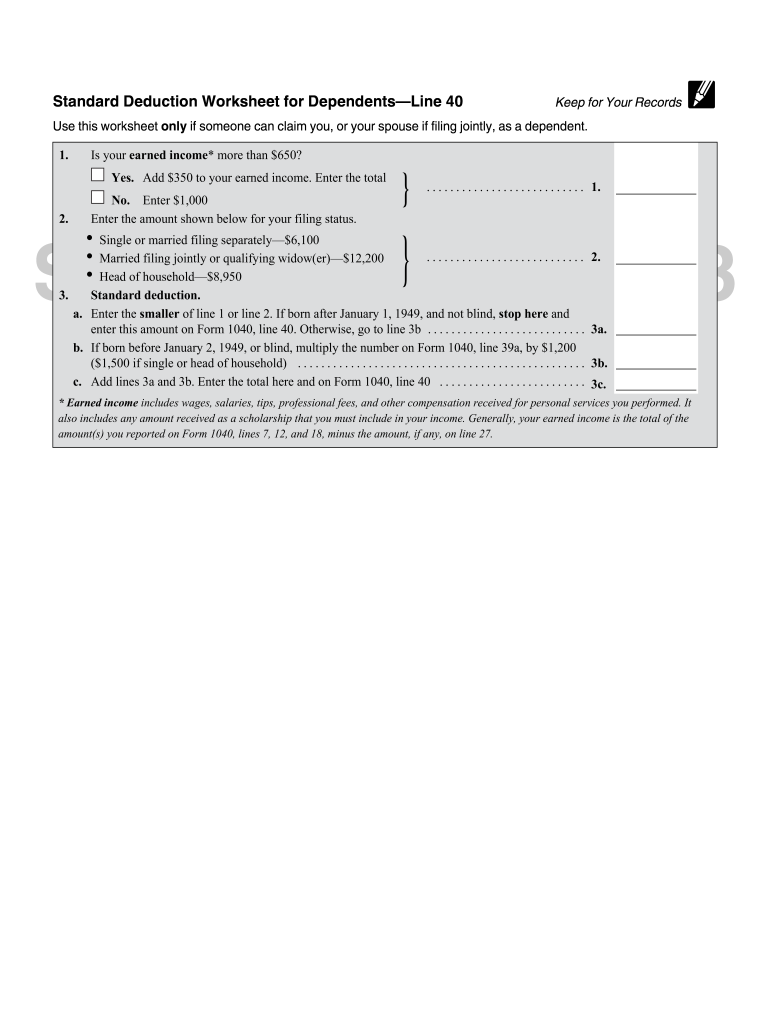
Here's a counter-intuitive point most people miss: if the dependent is blind or over 65, they don't get an additional standard deduction themselves. The additional amount for age or blindness only applies to the taxpayer filing the return, not to dependents claimed by someone else. I see this come up every year when a parent is filing for an older child who happens to be blind. The parent claims the dependency exemption breakdown correctly, but then tries to layer on the extra standard deduction for the dependent. It doesn't work that way. The dependent's standard deduction is locked to the formula I described above, period. There's also a scenario where the worksheet approach completely falls apart and you need a different strategy. If the dependent is married and filing separately, and their spouse itemizes, the dependent's standard deduction drops to zero. They can't take any standard deduction at all. This is one of those hidden penalties in the tax code that nobody warns about. If you're dealing with a dependent who is married and their spouse is itemizing, the standard deduction worksheet gives you nothing. You'd file with a standard deduction of zero and report all income. It sounds harsh, but it's the law. If you need the actual worksheet from the IRS, it's Schedule 1 of Form 1040, line 11, and the instructions walk you through the same calculation I laid out. You don't need a separate piece of paper. The tax software handles it automatically if you enter the dependent's income correctly, which brings me to the real bottleneck: getting the income categories right in the first place. Most errors happen because people dump all income into one bucket instead of separating earned from unearned. Spend five minutes sorting that before you touch the worksheet and you'll save yourself a lot of trouble later.
The 2025 numbers shift slightly with inflation adjustments. The floor goes up to $1,350, the additional amount for earned income stays at $450, and the ceiling for single filers moves to $14,600 still. The worksheet mechanics don't change, just the dollar amounts. If you're preparing returns for next year, you'll want to recalculate with the updated figures, but the process is identical. One last practical note: if the dependent had federal tax withheld from their wages, even if their income is entirely below the standard deduction amount, they should still file a return to get that money back. A standard deduction of $4,700 doesn't mean you don't file if you made $4,000. It means you owe no tax, but you might still need to file to claim a refund of withheld taxes. The worksheet tells you your deduction, not whether you have a filing requirement. Those are two separate questions and confusing them is probably the most common mistake I see.