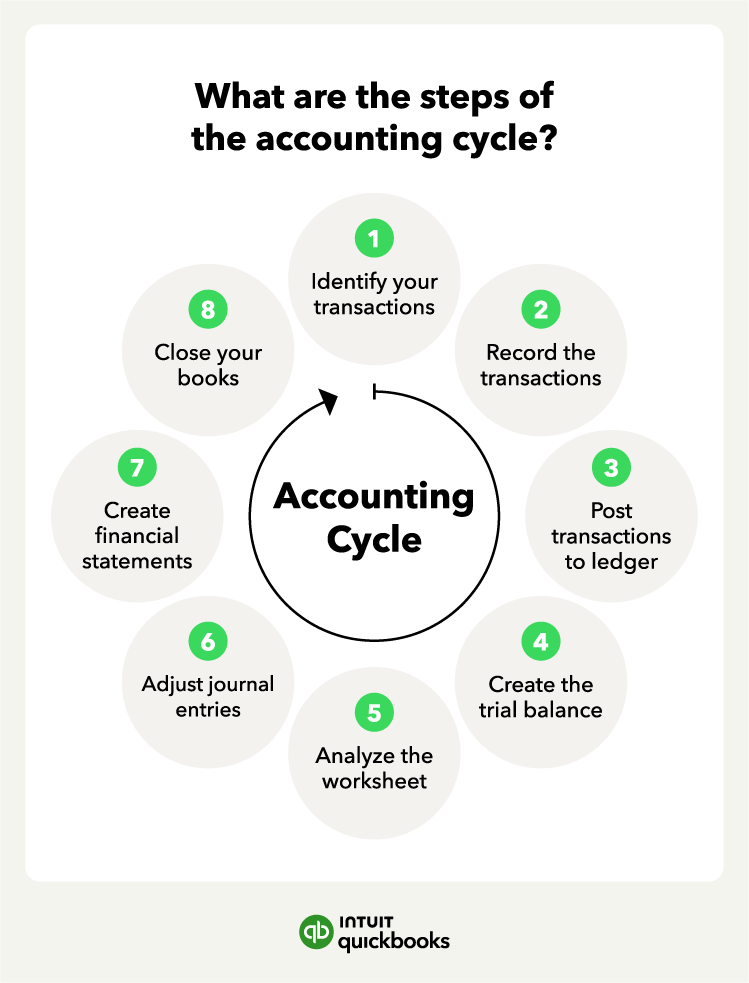
The Workflow Nobody Talks About
Most people learn accounting by staring at a chart of accounts and memorizing the difference between a debit and a credit. That approach rarely works in practice because real transactions never line up neatly with textbook examples. I spent the first three years of my career trying to force every receipt into the right category before touching a journal entry, and it made the books late every single month. The better approach is to treat accounting as a sequential documentation process rather than a theoretical exercise. The reality is that anyone doing Step By Step For Accounting Simple bookkeeping for a small business eventually hits the same friction points: receipts scattered across email, bank feeds that lag by two days, and customers who pay via checks that clear weeks after invoicing. You don't need a finance degree to manage this. You need a repeatable system that reduces the chance of misposting every time you close out a transaction.
Step By Step For Accounting Simple: The Core Method
Start by setting up a clean chart of accounts before you process a single transaction. I learned this the hard way after spending an entire Friday reclassifying twenty-three miscategorized expenses because I had lumped software subscriptions under Office Supplies instead of keeping them separate. The exact categories depend on your industry, but a standard small business setup should include at minimum an Accounts Receivable account, an Accounts Payable account, a Sales Revenue account, a Cost of Goods Sold account, and a General Expense account. Each one needs a specific purpose so that reporting actually means something when the quarter ends. Once the skeleton exists, the daily workflow breaks into four stages. The first stage is capture, where you record every inflow and outflow on the day it happens. This usually means importing bank feeds into your accounting software and matching each line item to an invoice, a vendor statement, or a receipt. A common mistake here is letting transactions sit in the feed for a week or two before touching them. The delay creates a gap between what your bank says you have and what your books say you have, and closing that gap later takes longer than doing it immediately. The second stage is categorization. Every uncategorized transaction gets assigned to the appropriate account in your chart. I used to overthink this step and spend extra time trying to find the perfect sub-account for minor purchases. A $4.50 charge for a coffee during a client lunch still belongs in Meals and Entertainment regardless of which specific restaurant it was at. The extra categorization does not change your tax outcome. It only makes your reports harder to read.
The third stage is reconciliation. This is where you compare your internal records against the actual bank and credit card statements line by line. Most people treat reconciliation as a month-end chore. It works better when done weekly because the errors are smaller and easier to find. A single duplicate entry in your books will show up as a mismatch of exactly one transaction amount. If you wait until the end of the month, you might have accumulated dozens of mismatches and no clear idea which ones are duplicates and which ones are missing entirely. The fourth stage is reporting. You generate a profit and loss statement and a balance sheet from the reconciled data. If your balance sheet shows a cash account that does not match your actual bank balance after reconciliation, something is wrong upstream. Do not ignore it. The mismatch is usually a direct deposit recorded twice, a voided check still sitting in the register, or a bank fee that was never manually entered. These are the tiny leaks that turn into serious problems by tax season.
Get the Full Details

A Real Edge Case That Breaks the Routine
Here is a specific scenario that the basic method does not handle well. I was working with a contractor who received advance payments from clients before any work was performed. The money hit the bank account and looked like revenue at first glance. Recording it as income immediately inflated the profit and loss by the full advance amount, even though the work was not done and the taxes on that income had not technically been earned yet. The fix was to set up a liability account called Customer Deposits or Deferred Revenue and route every advance payment there instead of the revenue account. When the work was completed and the invoice was satisfied, you then moved the amount from the liability account to the revenue account. Without this step, your tax liability would be based on cash you had not actually earned, and your net profit would look artificially high every quarter. Another edge case involves inventory. If you sell physical goods, the moment you purchase stock is not the moment you record an expense. It is the moment you sell the stock that the cost moves to Cost of Goods Sold. Getting this timing wrong will make your expenses look huge in the month you buy materials and tiny in the month you sell them, which produces a profit and loss statement that looks completely erratic even though the business is stable. The workaround is to use an inventory asset account and a perpetual inventory method if your software supports it. If it does not, you manually track the cost of each item and record the COGS entry at the point of sale.
Counter-Intuitive Things Beginners Miss
The first counter-intuitive point is that accrual accounting is not always the better choice for a small business. Cash basis accounting is simpler and easier to maintain. For most companies with under a million dollars in annual revenue, the tax code allows cash basis treatment, and the financial statements are often clearer because they reflect actual cash movement rather than theoretical recognition. The only time you should switch to accrual is if you carry significant inventory or your business model requires matching revenue to the period in which expenses were incurred to show a realistic picture. Otherwise, cash basis saves hours of work per month with no meaningful downside for decision-making. The second counter-intuitive point is that deleting transactions is almost always the wrong move. When you discover an error, the proper correction is to reverse or adjust it, not erase it. Auditors and tax preparers expect to see a complete transaction history. If a $500 expense was accidentally recorded against the wrong vendor, you create a journal entry that debits the correct vendor account and credits the incorrect one for the same amount. Both entries remain visible. The net effect is zero, but the trail explains exactly what happened. Deleting the original entry removes evidence that something went wrong in the first place.
What This Method Actually Fails At
The biggest limitation of a simple step-by-step accounting workflow is that it breaks down quickly when you have multiple revenue streams, multiple bank accounts, and employees. Each additional complexity layer multiplies the reconciliation work. A freelance graphic designer with one business checking account can run this system in about thirty minutes per week. A small construction company with three job cost accounts, two trucks financed separately, payroll, and subcontractor payments will need at least two to three hours per week even with good software. The workflow itself is not the bottleneck. The volume of distinct transaction types is. Another failure scenario involves sales tax collection. If you sell across multiple states or even multiple counties, the tax rates change based on where the customer receives the product or service. A simple accounting method will record the total sale amount as revenue and the tax portion as a liability, but it will not automatically calculate the correct rate for every jurisdiction unless your software has built-in tax automation. Without that, you are manually computing tax on every invoice, which is slow and error-prone. The practical workaround is to use a tool like Avalara or TaxJar integrated with your accounting software to handle the rate calculations automatically. Do not try to manage multi-jurisdictional sales tax by hand unless your transaction volume is extremely low. If your business grows past the point where manual reconciliation and simple categorization become a weekly burden, the next step is usually hiring a part-time bookkeeper or switching to a managed bookkeeping service. The workflow stays the same, but someone else handles the execution. The transition itself is the hard part because you will need to hand over your chart of accounts, your bank feed credentials, and your historical documents. Doing this cleanly means organizing your files first, which takes a day of work but prevents months of confusion later.