Working the deduction without losing your mind
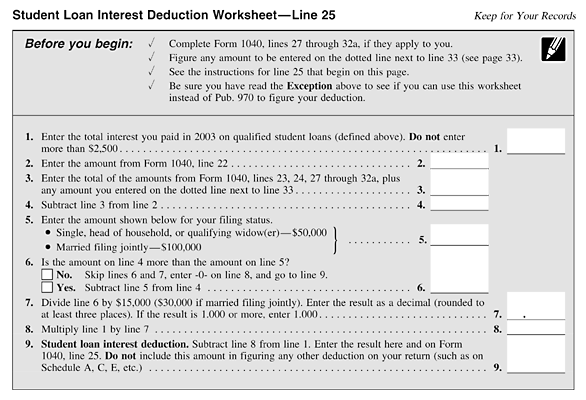
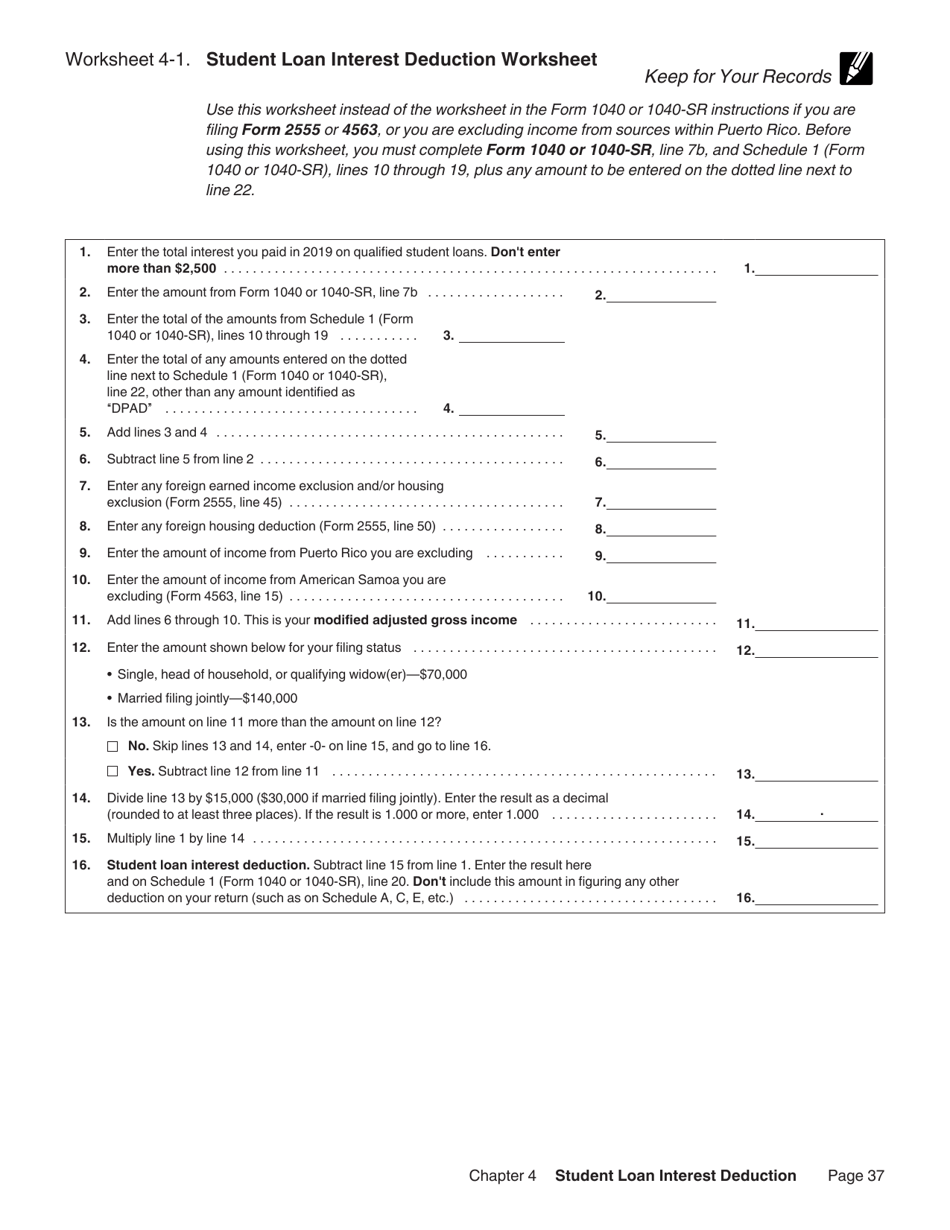
The Student Loan Interest Deduction Worksheet is mostly used by people who actually itemize or who have adjusted gross income that puts them in a position to claim the deduction on Schedule 1 of Form 1040. Most tax software just calculates it automatically now, which is convenient until your situation has a wrinkle. Then you need the worksheet to figure out whether the deduction applies, what the phaseout looks like, and exactly how much interest you can write off. I spent several years doing this manually for clients with unusual filing situations before the software companies mostly covered the logic. The worksheet itself is straightforward once you know which lines interact with each other. Let me walk through it from a practical angle rather than starting with definitions. Start with the actual interest you paid during the year. Your lender sends you Form 1098-E, which shows the total student loan interest you paid. That is your starting number. It is not always the full amount you intended because some people pay interest monthly and some do it in lump sums, and the form captures payments received by the lender during the calendar year, not necessarily payments you made with your own money.
Next, check the phaseout. For 2024, the deduction phases out for single filers with modified adjusted gross income above 75,000 dollars and is completely phased out at 90,000 dollars. For married filing jointly, it phases out between 150,000 and 180,000 dollars. The worksheet tells you to calculate a reduction percentage using the formula: MAGI minus the phaseout threshold, divided by the phaseout range. So if you are single with a MAGI of 82,500 dollars, that is 82,500 minus 75,000 equals 7,500, divided by 15,000, giving you a 50 percent reduction. You multiply your interest by that percentage and subtract it from the original amount. The trick most people miss is that you cannot just use your reported AGI. You have to use modified adjusted gross income, which means starting with AGI and then adding back certain items that the IRS requires you to include for this calculation. The most common additions are foreign earned income exclusion, foreign housing exclusion, and the deduction for student loan interest you already claimed if you are amending something. If you have employer-paid student loan contributions reported on your W-2, those also count into MAGI for this purpose.
Using the Student Loan Interest Deduction Worksheet step by step
The official worksheet appears in the Form 1040 instructions. Here is how I actually work through it line by line with clients. Line one is the interest from Form 1098-E. If you have multiple loans, add them all together. There is a 2,500 dollar maximum deduction regardless of how much you actually paid, so cap it there even before any phaseout. Line two asks whether you are married filing separately. If yes, you generally cannot claim the deduction. This catches a surprising number of people who file separately due to divorce or other complications and then assume they get nothing. They do.
Get the Full Details

Line three is where you check your filing status and income against the phaseout table. If your MAGI is below the threshold, you are done. The deduction is your capped interest amount. If it is in the phaseout range, calculate the reduction percentage. If it is above the top of the range, the deduction is zero. Line four is the reduction calculation. Multiply your line three amount by the phaseout percentage. Subtract that from your capped interest to get the final deductible amount. Here is a concrete example. Sarah paid 3,200 dollars in student loan interest during 2024. She files as head of household with a MAGI of 88,000 dollars. The phaseout range for head of household is the same as single: 75,000 to 90,000 dollars. Her reduction percentage is 88,000 minus 75,000 equals 13,000, divided by 15,000, which is about 86.7 percent. She multiplies her 2,500 dollar cap by 86.7 percent to get a reduction of approximately 2,167 dollars. Her deductible interest is 2,500 minus 2,167, or about 333 dollars. She enters that on Schedule 1, line 21.
I ran into a particularly annoying case last year with a client who had refinanced his parent PLUS loan and was paying it back while his mother was still alive. The lender issued Form 1098-E to him, but the loan was originally in his mother's name. He asked whether he could claim the deduction. Under current rules, you can only deduct interest on a qualifying student loan that you are legally obligated to pay. A refinanced parent PLUS loan counts if you are the borrower. The form matched. The deduction was allowed. But the client had originally been told by his accountant years earlier that parent PLUS loans were never deductible, which is simply wrong. Parent PLUS loans are deductible for the borrower, not the parent, once the borrower refinances and assumes the obligation. Another counter-intuitive thing about this deduction: it is an above-the-line deduction. That means you do not need to itemize to claim it. This is important because many people think they have to forgo it if they take the standard deduction. You do not. The 2,500 dollar deduction reduces your AGI directly on Form 1040, which can also help you stay under phaseout thresholds for other credits and deductions. Lowering your AGI by even a few hundred dollars can sometimes unlock a larger credit elsewhere on the return. Here is the downside I rarely see mentioned. The deduction does not help much if your interest is below 600 dollars. Below that amount, lenders are not required to issue a Form 1098-E, though they must give you the information if you request it. The benefit of the deduction is also capped at 2,500 dollars, so a taxpayer in the 24 percent bracket saves at most 600 dollars a year. At that point, the effort of tracking and calculating the worksheet is marginal compared to the tax savings. People in the 32 percent bracket or higher get more value from it, but even then, the absolute dollar benefit is limited.
If you are trying to maximize the deduction, paying interest in December rather than January matters less than you might think because the phaseout is based on full-year AGI, not payment timing. What matters more is timing your other income. If you can defer a bonus or realize a capital loss in the same year, reducing your MAGI by even a couple thousand dollars can push you below the phaseout threshold and recover far more than the deduction itself is worth. I had a client who was sitting at 91,000 dollars of MAGI and lost the entire deduction. She had an unrealized loss in her brokerage account. She sold a small position to realize about three thousand dollars in losses, dropped her MAGI to 88,000, and came back into the phaseout range. The strategy was straightforward but the math was the kind of thing that only shows up when you actually work through it. If you want the official worksheet, go to the IRS website and pull the Form 1040 instructions for the current tax year. The Student Loan Interest Deduction Worksheet is included near the Schedule 1 instructions. Do not use an outdated version. The phaseout ranges change periodically, and the 2023 worksheet had different thresholds than the 2024 version. Using the wrong year will give you the wrong phaseout percentage and possibly make you overclaim or underclaim the deduction. The worksheet assumes you understand which income items count toward MAGI. If you have a complicated return with foreign income, rental properties, or self-employment, the MAGI adjustment can be nontrivial. In those cases, running the calculation twice with different assumptions and comparing the result to what your software produces is a reasonable sanity check. If the numbers diverge by more than a few dollars, check your MAGI additions first. That is where the errors usually hide.