Building a Study Guide for Money Management and Financial Planning That Actually Works
I spent three years designing financial literacy curricula for a community nonprofit before moving into corporate training. The material itself is straightforward. The way people absorb it is not. Most study guides fail because they treat money management and financial planning like subjects you can memorize rather than skills you practice. A spreadsheet or a textbook chapter won't change someone's spending habits. Neither will a well-formatted PDF. Here is the core framework I use, built from watching real people try and fail at applying what they learned. Start with the order of operations, not with theory. People need to know what to do first, second, third before they care about the underlying mechanics of compound interest or tax-advantaged accounts. The typical mistake is leading with definitions. Nobody remembers what a Roth IRA is until they have decided they want one. I organize study guides around decision points rather than topics. Each section should answer: when would you use this, what tool do you need, what is the exact calculation or form, and what goes wrong most often. The hierarchy I follow is emergency fund, high-interest debt, basic insurance, retirement accounts, budgeting systems, and then advanced topics like college savings or estate planning. That last point matters. Estate planning gets thrown in too early and overwhelms people who have not yet settled on a monthly budget.
Every concept needs a worked example with real numbers. I prefer examples that show both the textbook outcome and the realistic outcome. A $500 monthly retirement contribution grows to roughly $450,000 over 30 years at a 7% return. That is the textbook version. The realistic version includes years where the market drops, the person misses two contributions because of a car repair, and the actual total lands closer to $380,000. Both numbers belong in the guide. The gap between them is where people lose confidence and quit.
A Tool You Can Download and Customize
The most useful single component is a living cash flow template paired with a debt payoff calculator. Here is how to build it. Start with a spreadsheet that tracks actual income against fixed expenses, variable expenses, and debt minimums. Add columns for projected surplus or deficit by month. Link the debt payoff section so that extra payments shift the balance automatically and recalculate the interest saved. Do not hard-code assumptions. If someone enters a 6.5% interest rate on their credit card, the calculator should adjust every downstream figure. I created a version of this for a class of adult learners who were all at different income levels and debt points. One student had $12,000 in medical debt at 0% for 18 months, another had a $40,000 car loan at 4.2%, and a third was carrying $8,000 in credit card balances at 24%. The same template handled all three because I built in conditional formatting that flagged which payoff method applied. The snowball method for the medical debt during the promotional window, the avalanche method for the car loan once the promotional window closed, and direct balance transfers with a fees calculation for the high-interest card. It took about 20 minutes per person to set up after I walked them through the template once.
Get the Full Details

The Counter-Intuitive Part Nobody Teaches
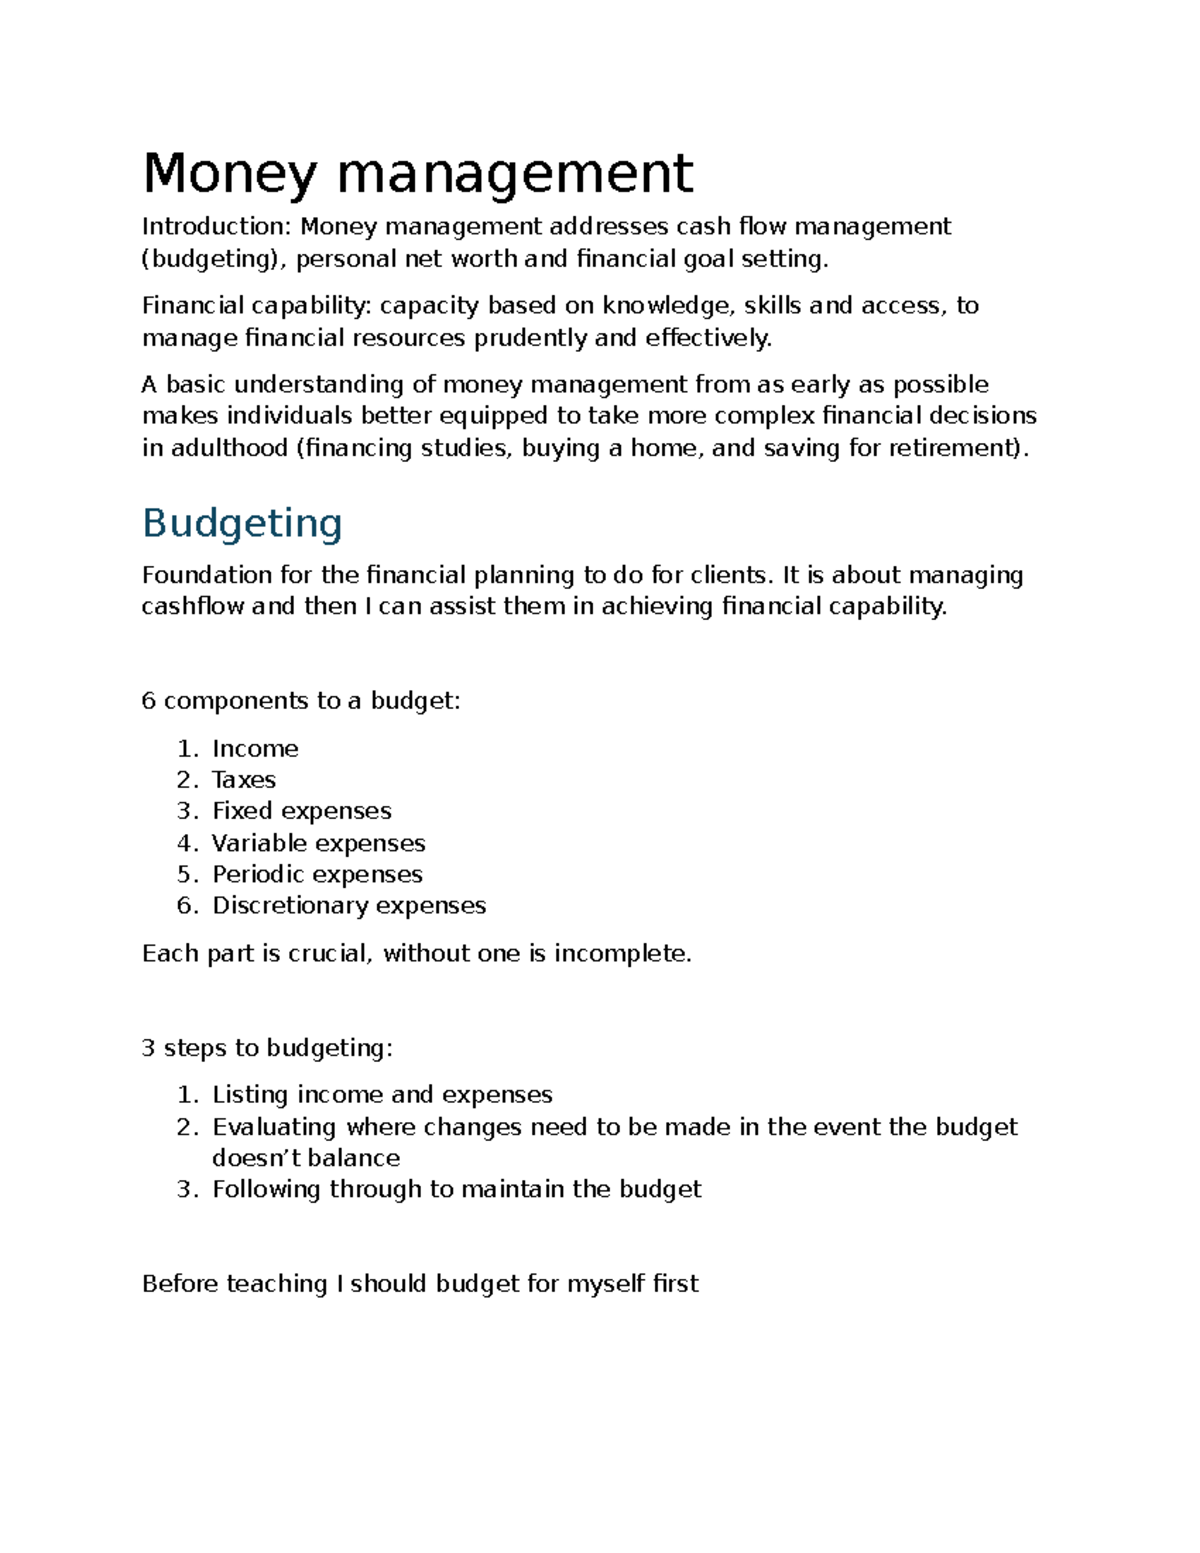
Most study guides tell people to track every expense. That is usually the wrong advice. Tracking every expense works for about six weeks and then burns people out. The research I have seen and the classroom data I collected both show that expense tracking loses predictive power once the novelty fades. What actually moves the needle is category-level budgeting combined with a weekly 15-minute reconciliation. People who review their spending once a week catch drift before it becomes a crisis. People who track every coffee purchase usually stop tracking entirely by month three. Another thing that surprises beginners: paying off the smallest balance first, the snowball method, produces better behavioral outcomes than the avalanche method even when the avalanche method saves more money in interest. I do not recommend this because it is mathematically superior. I recommend it because I watched a student with $9,000 in credit card debt pay off three smaller cards first, feel momentum, and then attack the largest balance. She stayed in the program long enough to be debt-free. Another student with the same total debt chose avalanche, got nowhere emotionally, and stopped engaging with the material after four months. Behavioral psychology in personal finance is not fluff. It is the difference between completion and dropout.
What Breaks These Study Guides
The biggest bottleneck is outdated tax information. A study guide published in early 2024 will have incorrect 401(k) contribution limits by the end of the year. The 2025 limits changed. Anyone distributing this material must note the year on every page and flag contribution limits, standard deduction figures, and education credit thresholds as variables that require verification. I add a revision log at the front of every guide I distribute. It looks like this: updated for 2025 tax year, contribution limits revised, links verified as of March 2025. Five minutes of work that prevents credibility damage later. A second failure mode is assuming readers have access to the tools you are teaching. If you recommend automation through a banking app and your audience uses a credit union with a clunky interface, the guide becomes irrelevant. I include an alternative path for every major recommendation. Manual transfers for people without auto-pay. Paper statements for people who distrust apps. Cash envelopes for people who need physical friction to control spending. Flexibility is not a nice-to-have in a study guide. It is the entire point.
How to Distribute It
If you are creating a downloadable guide, package it as a PDF with clickable table of contents and a companion spreadsheet. The PDF carries the concepts and examples. The spreadsheet carries the practice. Separating them forces people to move from reading to doing, which is where retention happens. A single monolithic document tends to sit unread or get bookmarked and forgotten. I have seen this pattern repeatedly across workshops and online courses. Include a one-page summary at the beginning and a checklist at the end. The one-pager answers: what is this, who is it for, and what is the first action. The checklist answers: have I completed the essential steps, and where do I go next if I get stuck. I also add a FAQ section based on questions I actually heard in class, not questions I imagine people might ask. The real questions are always the same: what if I cannot save $500, what happens if I lose my job during debt payoff, and how do I handle a partner who disagrees with the plan. Answer those honestly and you have a usable document.

A Specific Edge Case and Workaround
I encountered a problem with a student who had irregular income as a freelance graphic designer. The standard monthly budget template broke immediately because her income varied by plus or minus 40% month to month. She could not meaningfully assign a fixed amount to groceries or rent on some months. Rather than force her into a template that did not fit, I switched her to a percentage-based system. She allocated a fixed percentage of each deposit to savings, debt, and essentials instead of a fixed dollar amount. When income dropped, everything scaled down proportionally. When income rose, the surplus grew faster. It required a one-time adjustment to her spreadsheet and a different mindset shift, but it stayed functional across four income cycles. I now include an irregular income module in every study guide I produce. It takes up two pages but covers roughly a third of my students. Do not lead with investment strategies. Do not include affiliate links to brokerage signups inside the core material. Do not promise specific returns. Do not present a single brand or platform as the default solution. These choices undermine trust faster than any typo or formatting error. The guide should function as reference material, not as a sales funnel. People can smell that instantly and they stop reading. Keep the language flat. You do not need enthusiasm to teach financial planning. You need clarity, accuracy, and enough practical grounding that someone can open the document at 11 p.m. after a shift and actually do something with it.