How the Suze Orman Budget Worksheet Actually Works
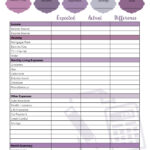
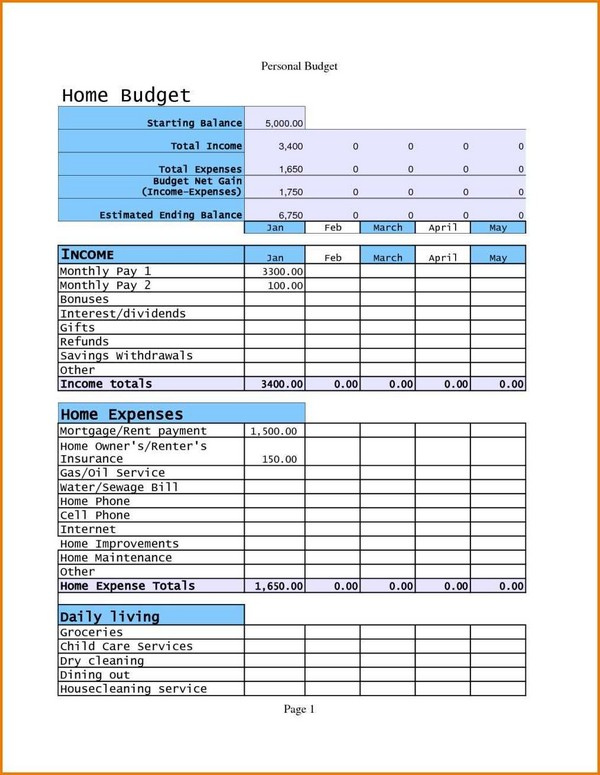
Most people find the Suze Orman Budget Worksheet through Google searches after watching her show or reading her books. The worksheet itself is a straightforward 50/30/20 budgeting tool — 50% for needs, 30% for wants, 20% for savings and debt repayment. The math is simple enough that you could do it on a napkin. The hard part is making yourself actually track where your money goes. You can find the original Suze Orman Budget Worksheet on her website at suzeorman.com, usually under the free resources or tools section. She also partners with Financial Engine and other platforms that host downloadable versions. Sometimes the file format shifts between PDF, Excel, or a web-based form depending on when you look. Print it if that helps you think clearly. I prefer paper because it forces you to sit down and do the work instead of skipping ahead. Fill it out using your last full month of actual spending. Not estimated spending. Not what you think you spent. What you actually spent. Pull your bank statements and credit card statements and categorize everything line by line. This step usually takes longer than people expect. If you have irregular income, that adds another layer of complication that the standard worksheet doesn't handle well. I've had clients who are self-employed or commission-based struggle with this part because the 50/30/20 framework assumes a steady paycheck coming in every two weeks.
There is one edge case that comes up constantly. People with large seasonal expenses — things like property taxes, insurance premiums, car registration, holiday spending — will blow right past their 50% needs allocation because those bills cluster in certain months. I worked with a client last year who lived in a high-property-tax state and was consistently "over budget" by nearly $800 a month even though her day-to-day spending was tight. The workaround was to divide those annual expenses by twelve and treat them as monthly line items on the worksheet, then adjust her discretionary category accordingly. Once she did that, the numbers stopped looking scary. The worksheet tracks your income first, then subtracts the three main categories. Whatever lands in the twenty percent bucket is non-negotiable. That means debt payments beyond minimums and savings contributions go there before anything else gets considered. This is the part most people mess up because they want to allocate toward savings after paying for lifestyle stuff. Suze's point is that you pay your future self first and live on whatever is left.
The Parts People Skip and Why It Hurts Them
The worksheet asks you to separate needs from wants honestly. Rent is a need. A subscription to a streaming service is a want. The line between those categories gets blurry fast for a lot of people. Dining out is frequently categorized as a want, but if you don't cook at home and eat out every single day, that's actually your food expense and should count as a need. Misclassifying things like this is the most common error I see, and it completely distorts the picture the worksheet is supposed to give you. Another thing most people get wrong is running this worksheet once and calling it done. The Suze Orman Budget Worksheet is meant to be a monthly exercise. Your income changes. Your spending shifts with the seasons. The numbers from March don't tell you much about what November looks like. I typically recommend running it for three consecutive months before you trust what the data is showing you. One month is a snapshot. Three months is a pattern. The biggest limitation of this system is that it doesn't account for people whose income falls below a certain threshold. If you make less than forty thousand dollars a year in most metro areas, the fifty percent needs allocation might still not cover rent, utilities, groceries, and transportation. In those cases, forcing the 50/30/20 split creates a false sense of failure. The worksheet isn't designed for that scenario, and Suze herself has acknowledged this in later editions of her books. When the percentages don't work, you drop the wants category entirely and redirect everything available toward debt reduction and emergency savings until your income situation improves.
Get the Full Details
A couple of practical tips that don't get enough attention. First, carry over any unspent amount from one category to the next month rather than treating it as gone. If you only spent eighty percent of your wants budget, that remaining twenty percent isn't lost, it just becomes a cushion for the following month. Second, track high-interest debt separately. The worksheet lumps all debt into the twenty percent bucket, but if you have credit card debt at twenty-two percent interest alongside a car payment at five percent, prioritizing them differently within that bucket makes a real difference over time. Pay off the high-interest obligation first inside that allocation before applying more to the lower-rate debt. The Suze Orman Budget Worksheet won't solve your financial problems on its own. It's a diagnostic tool first and a planning tool second. You have to do the actual behavioral work of sticking to the categories after the numbers are on the page. That's where most people fall apart. The worksheet makes the problem visible. You're the one who has to change what you do about it.