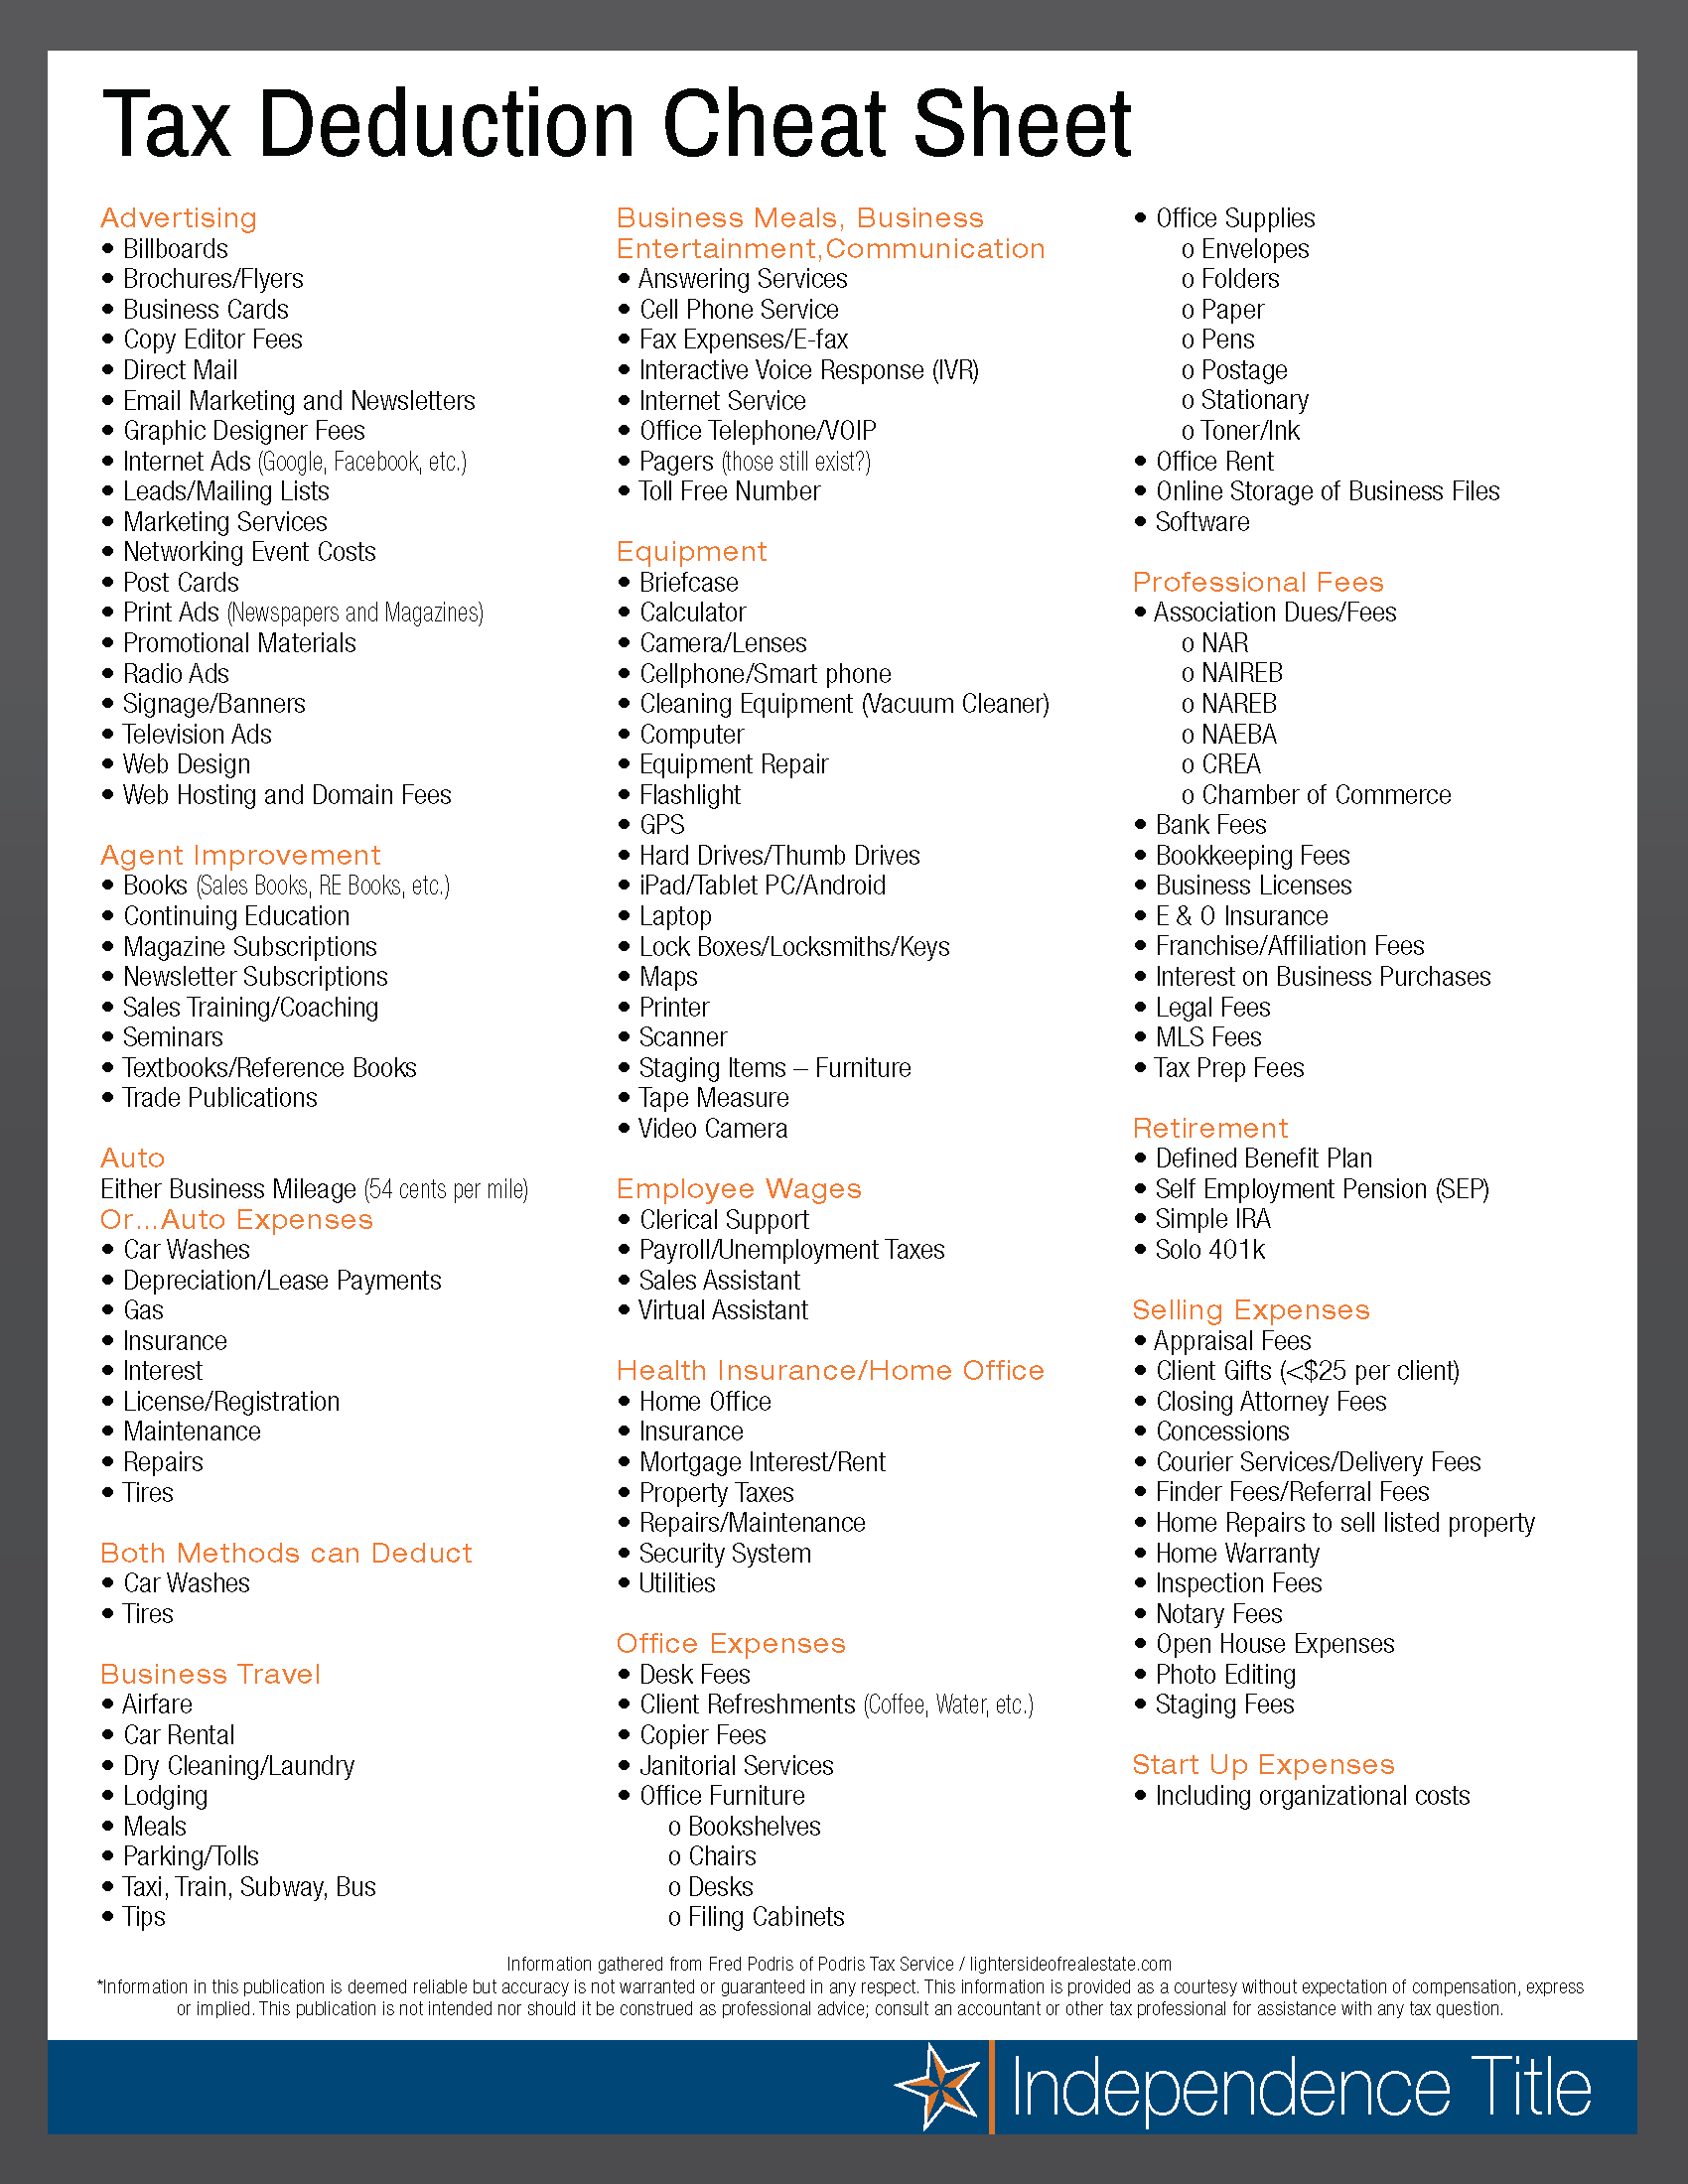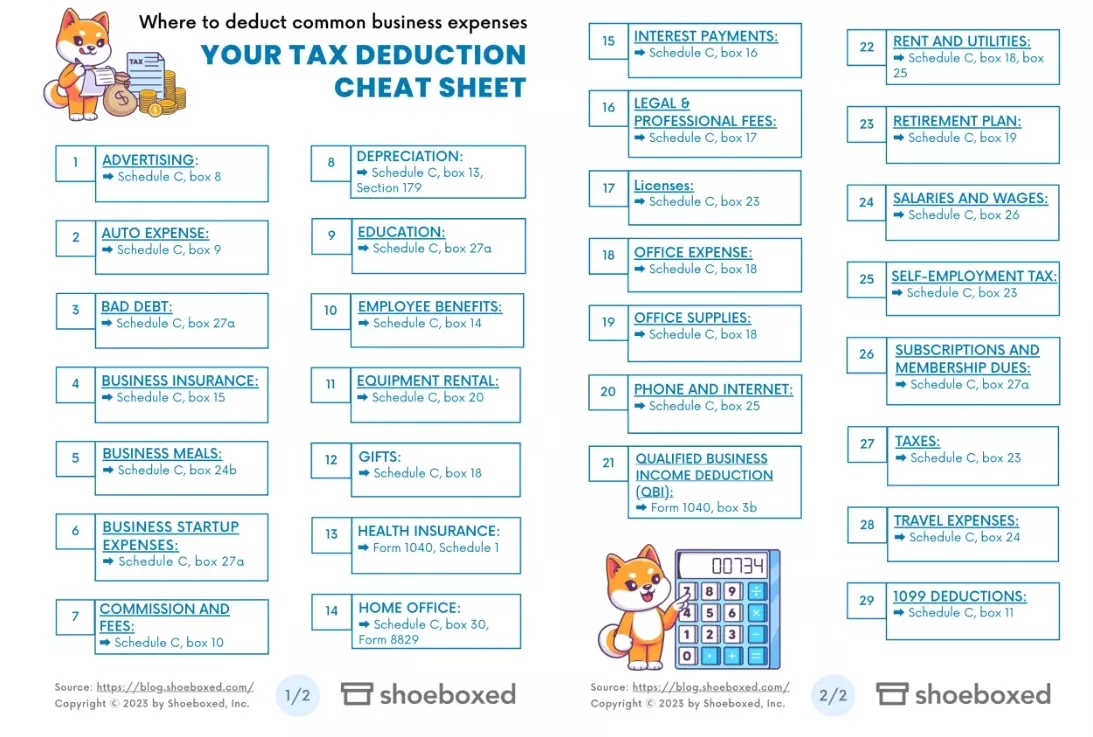
How to Actually Use a Tax Deduction Cheat Sheet Without Losing Your Mind
Most people treat these things like religious texts. They print one out, underline a few lines, then throw it in a drawer until tax season hits again. That is not how you use a Tax Deduction Cheat Sheet. It is a reference tool, not a strategy. You flip to it when you need to verify a limit, check a threshold, or remember whether something falls under business expense versus capital asset. That is it. Everything else is just noise.The real value comes from understanding the categories, the timing, and the documentation rules. Let me walk through how I actually use mine and where people mess up. A proper cheat sheet covers the main deduction buckets and their current limits. That means standard vs. itemized, above-the-line adjustments, business expenses, and any category-specific caps. The IRS publishes the updated numbers every year, and they shift more often than people realize. A 2023 version of most cheat sheets is already wrong for 2026 filings. Here is what mine actually contains, in order of use:
Standard deduction amounts by filing status. Single, married filing jointly, head of household. These are published annually. For 2026 the numbers are roughly $14,600 for single, $29,200 for married filing jointly, and $21,900 for head of household. Round numbers. Easy to misremember if you are pulling from a sheet two years old. Above-the-line adjustments. Things like traditional IRA contributions, HSA contributions, student loan interest, educator expenses, self-employment tax deduction, and the self-employed health insurance deduction. These reduce your AGI directly. People forget that AGI drives a lot of other eligibility thresholds, so the indirect impact of these is bigger than most realize. Business expense deductions for freelancers and small business owners. Home office, supplies, vehicle use (standard mileage rate vs. actual expenses), professional fees, and Section 179 expensing. The home office deduction alone catches most people off guard because the simplified method caps at 300 square feet at $5 per square foot, but the regular method can yield more if your actual expenses justify it.
Capital gains holding periods. Short-term vs. long-term matters more than beginners think. Assets held over one year get preferential rates. Under one year, they stack on top of your ordinary income and push you into higher brackets. This is the kind of detail that lives on the back page of the cheat sheet but is the most important thing to check before selling anything.
Get the Full Details

Where People Waste Money on Deductions
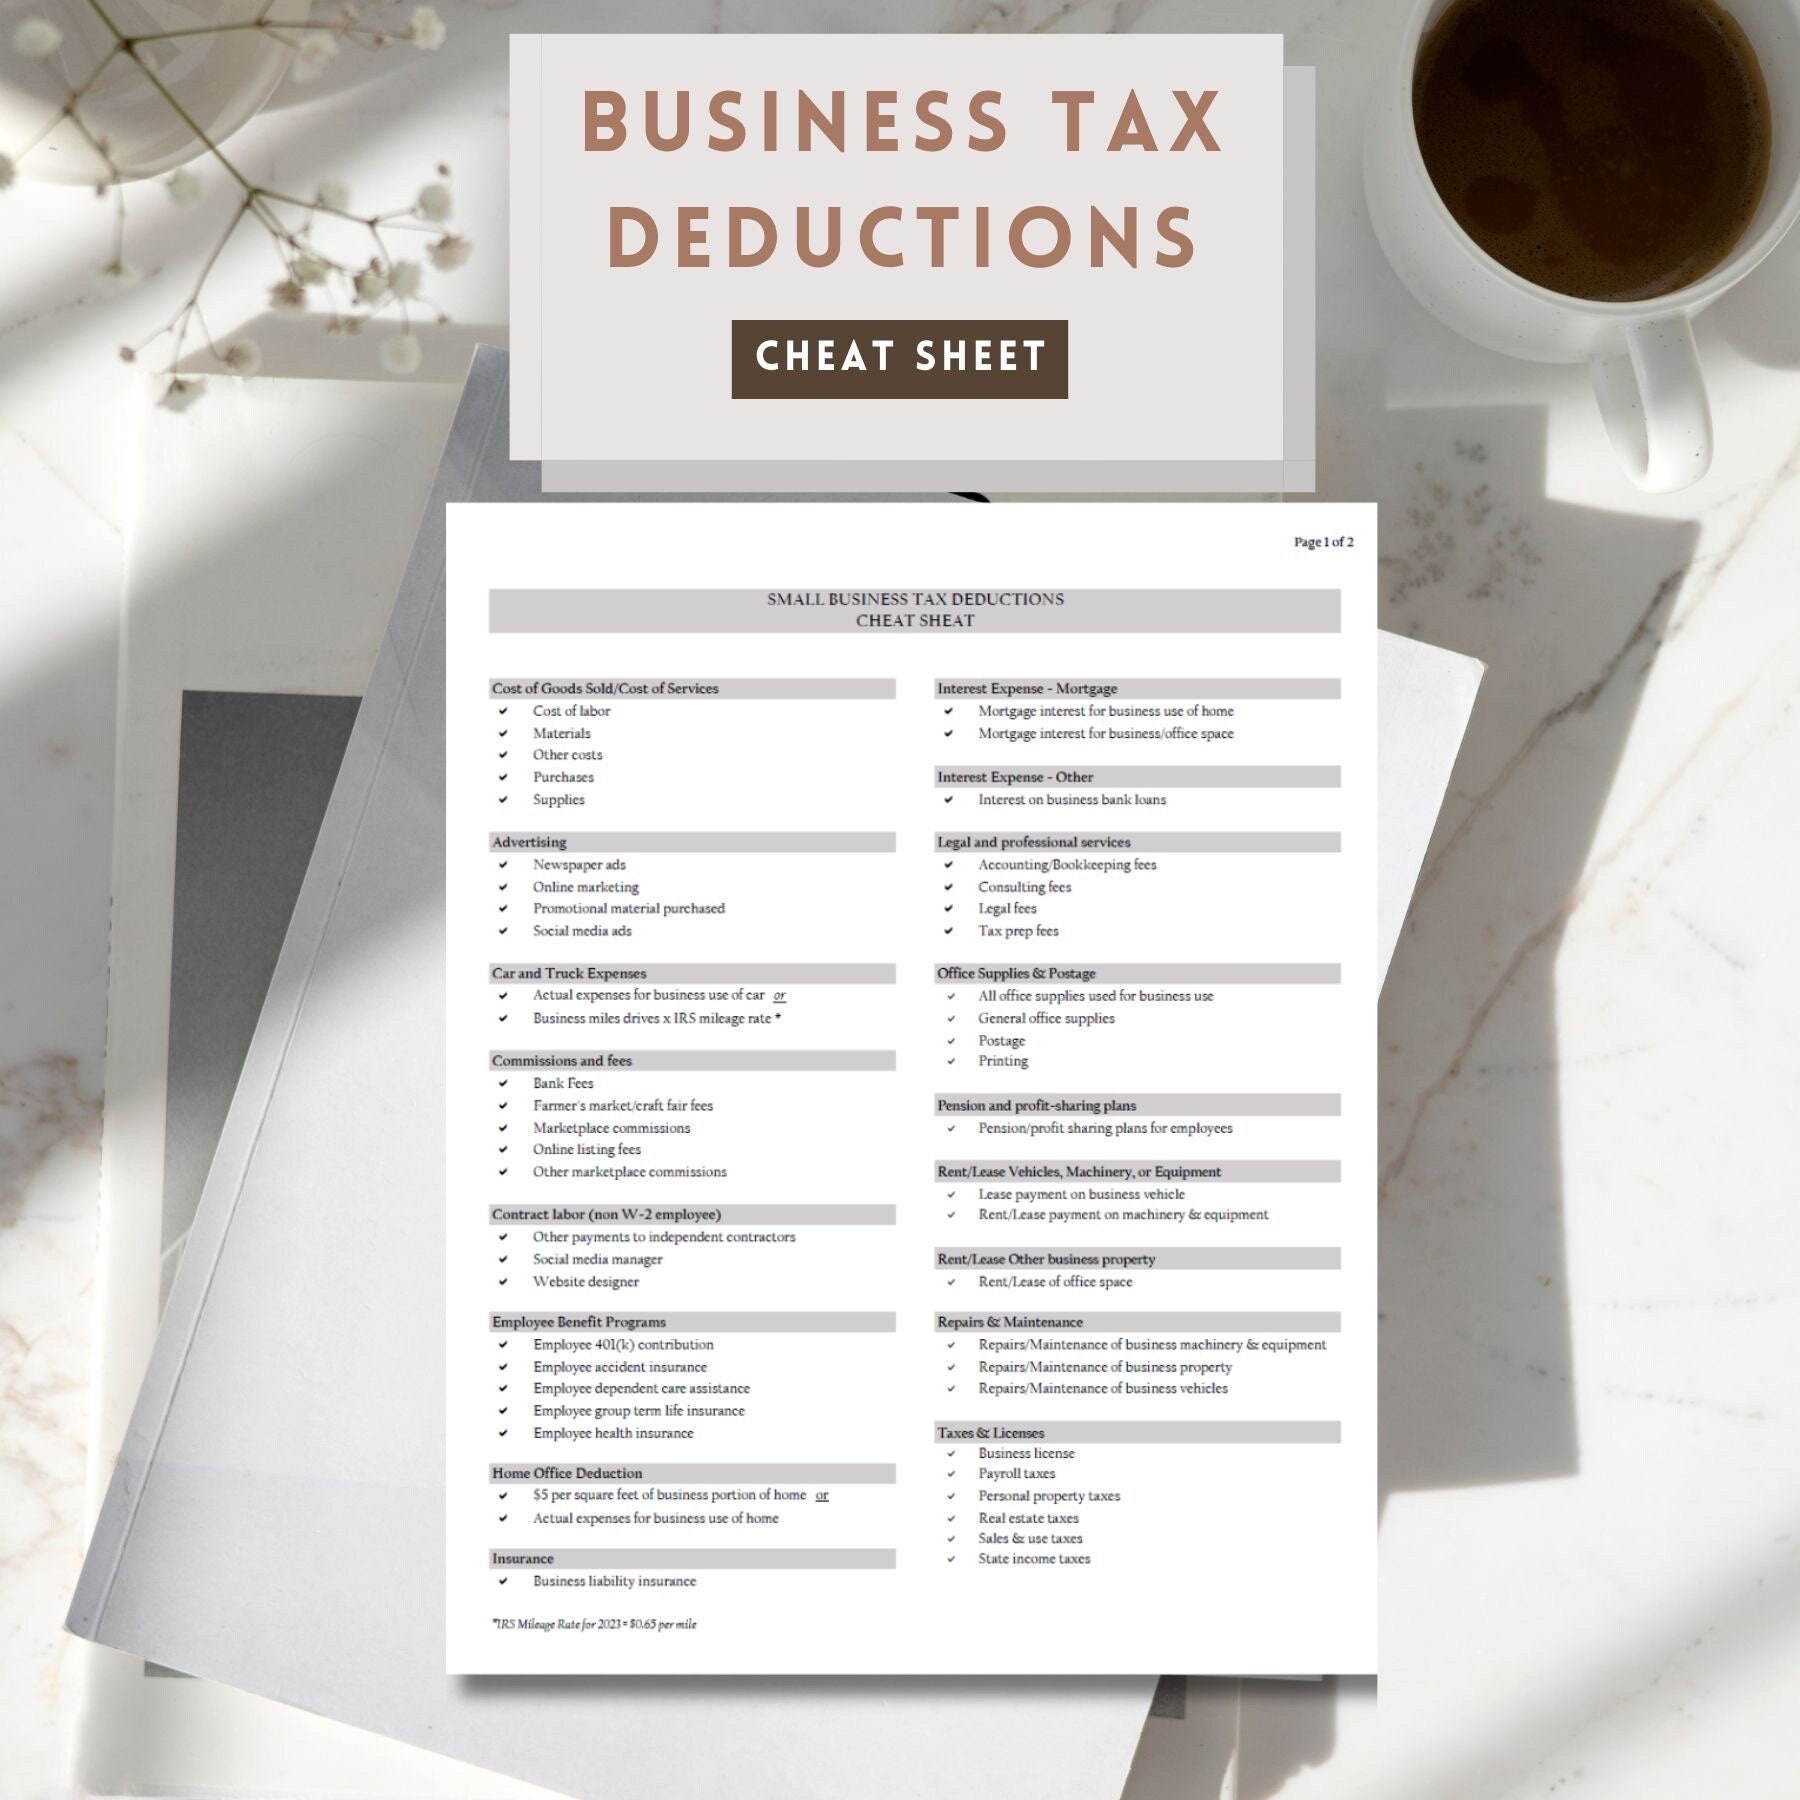
The biggest mistake I see is treating the standard deduction as a floor instead of a choice. If your itemized deductions do not exceed the standard amount, there is no benefit to itemizing. Period. But many people have a cluster of expenses in a given year that push them just over the line. Medical expenses over 7.5% of AGI, state and local taxes capped at $10,000, mortgage interest, charitable contributions. Run the numbers before committing to itemizing. Another trap is misclassifying capital assets. I had a client once who deducted $8,400 worth of computer equipment and software in a single year across five different purchases. He thought he was writing them off as ordinary business expenses. They were not. Each piece was over the de minimis safe harbor threshold, and he needed to depreciate them over three to seven years depending on the type. We amended the return and took the Section 179 election instead, which let him expense the full amount in one year if he structured it right. The fix cost us about three hours of work and a corrected Schedule C. The original mistake cost us an extra $2,100 in unexpected tax liability plus penalties. Never skip the asset categorization step, even if you have ten small purchases to account for. Vehicle expenses are another mess. The standard mileage rate for 2026 is 70 cents per mile for business use. Actual expenses method involves gas, insurance, maintenance, depreciation, and registration. The cheat sheet lists both. What it does not tell you is that if you use your car for both business and personal purposes, you need contemporaneous logs. Guessing how many business miles you drove and filling in the gap later is audit bait. I keep a simple spreadsheet with date, purpose, starting odometer, ending odometer, and miles. Takes twenty seconds per trip. Saved me from reconstructing three years of records during a random review once.
What Most Cheat Sheets Leave Out
They rarely mention the documentation retention rules. You need to keep receipts, logs, and supporting records for three years from the filing date or the due date, whichever is later. Seven years if you underreport income by more than 25%. Indefinitely if you never filed a return. These rules are not optional, and nobody reads them until they are already behind on paperwork. They also skip over the interaction between deductions and credits. A deduction lowers your taxable income. A credit lowers your tax bill dollar for dollar. You want credits first. The deduction helps, but it is not the same thing. Mixing them up leads to wildly inaccurate projections of what you will actually owe or get back. The SALT cap change is another quiet landmine. The $10,000 limit on state and local tax deductions has been in place since 2018, but people still act surprised when they hit it. If you live in a high-tax state and own a home, you are likely already at or near that ceiling. Additional property taxes or increased state income tax payments beyond that point provide zero federal deduction benefit. This changes your state-level tax planning entirely, but you will not see it reflected on most generic cheat sheets.
How I Build and Maintain My Own
I do not buy or download most of these. They are outdated before they print. I maintain a living document in Google Sheets with columns for category, description, limit, current year value, source link, and last verified date. Every time the IRS publishes a new revenue procedure or notice, I update the relevant row. The whole thing takes maybe fifteen minutes a month. The source links point directly to IRS pages, not blog posts summarizing the IRS pages. I learned that the hard way after citing a third-party article in a client meeting that had the wrong depreciation schedule. For quick reference during filing season, I keep a condensed one-page version printed out on my desk. It covers the standard deduction, the top ten above-the-line adjustments, the current standard mileage rate, the Section 179 limits, the SALT cap, and the charitable contribution rules for cash and non-cash gifts. That is it. Everything else is in the master sheet. The condensed version fits on one side of an 8.5 by 11 page. If you need more detail than that, you are looking at the wrong thing. The master sheet is here: Internal Revenue Service publication lookup page. Bookmark it. Check it quarterly. That is the only workflow that survives beyond one tax season without breaking.
When a Cheat Sheet Fails You Completely
These tools assume you are dealing with straightforward situations. If you run a multi-state business, have foreign income, deal with estate matters, or own rental properties across state lines, a cheat sheet will not help you. The complexity is not in the deduction categories themselves but in how they interact across jurisdictions and filing requirements. In those cases, the cheat sheet is background reference at best. You need a CPA or enrolled agent who understands the specific intersection of rules that applies to your situation. I have seen people try to self-file complex partnership distributions using only a cheat sheet and end up with mismatched K-1s that trigger notices six months later. The cost of fixing those errors dwarfs any fee you would pay for professional help upfront. The same goes for cryptocurrency. Tax treatment of digital assets has shifted multiple times in the last few years, and most cheat sheets have not caught up to the current reporting requirements. Even updated ones often omit the cost basis tracking methods available. If you trade crypto, you need a dedicated tracking tool and a practitioner who follows the guidance updates, not a one-page summary.
Practical Use Case
Last year a client came to me with a Schedule C that looked fine on the surface. She had claimed $12,000 in home office expenses using the simplified method and $4,500 in startup costs under Section 195. The Section 195 election was wrong. She had started the business three years prior, so the startup window had closed. We refiled using the amortization election instead, spreading the deduction over eighteen months. The tax difference was minor, but the compliance path was cleaner. The cheat sheet had the Section 195 rules in the right place, but the date-sensitive limitation was easy to miss if you were just scanning for the dollar amount. That is the exact kind of edge case where a cheat sheet is useful and dangerous at the same time. It gives you enough to start looking in the right section, but it does not substitute for reading the surrounding text and understanding the timing rules. Use the cheat sheet to find the right category quickly. Then read the IRS source material for that category. Then apply it to your specific situation with the documentation to prove it. Three steps. No shortcuts between them.
Summary of Key Rules
The standard deduction is not always the best option. Itemizing requires a calculation. Run both. Keep logs for vehicle use and home office. Classify assets before deducting them. Verify every number against the current IRS publication. Update your reference material every January. Do not rely on a single sheet for multi-state, international, or complex entity situations. When in doubt, professional help is cheaper than an amendment.