What Actually Happens When You File
Most small business owners treat taxes as something they deal with once a year, usually in March or April, and panic through it. I've watched people do this for twenty years. The reality is that tax compliance for a small business isn't a single event, it's a continuous process that compounds poorly if you ignore it month to month. The core requirement is straightforward: you need to classify your business correctly, track income and deductions throughout the year, and file the right forms by the right deadlines. But the classification piece is where people make expensive mistakes. Operating as a sole proprietorship by default is fine until you're not, and then you're either underpaying quarterly taxes or overpaying and sitting on a refund that should have been yours throughout the year.
Understanding Tax For Small Business Owners
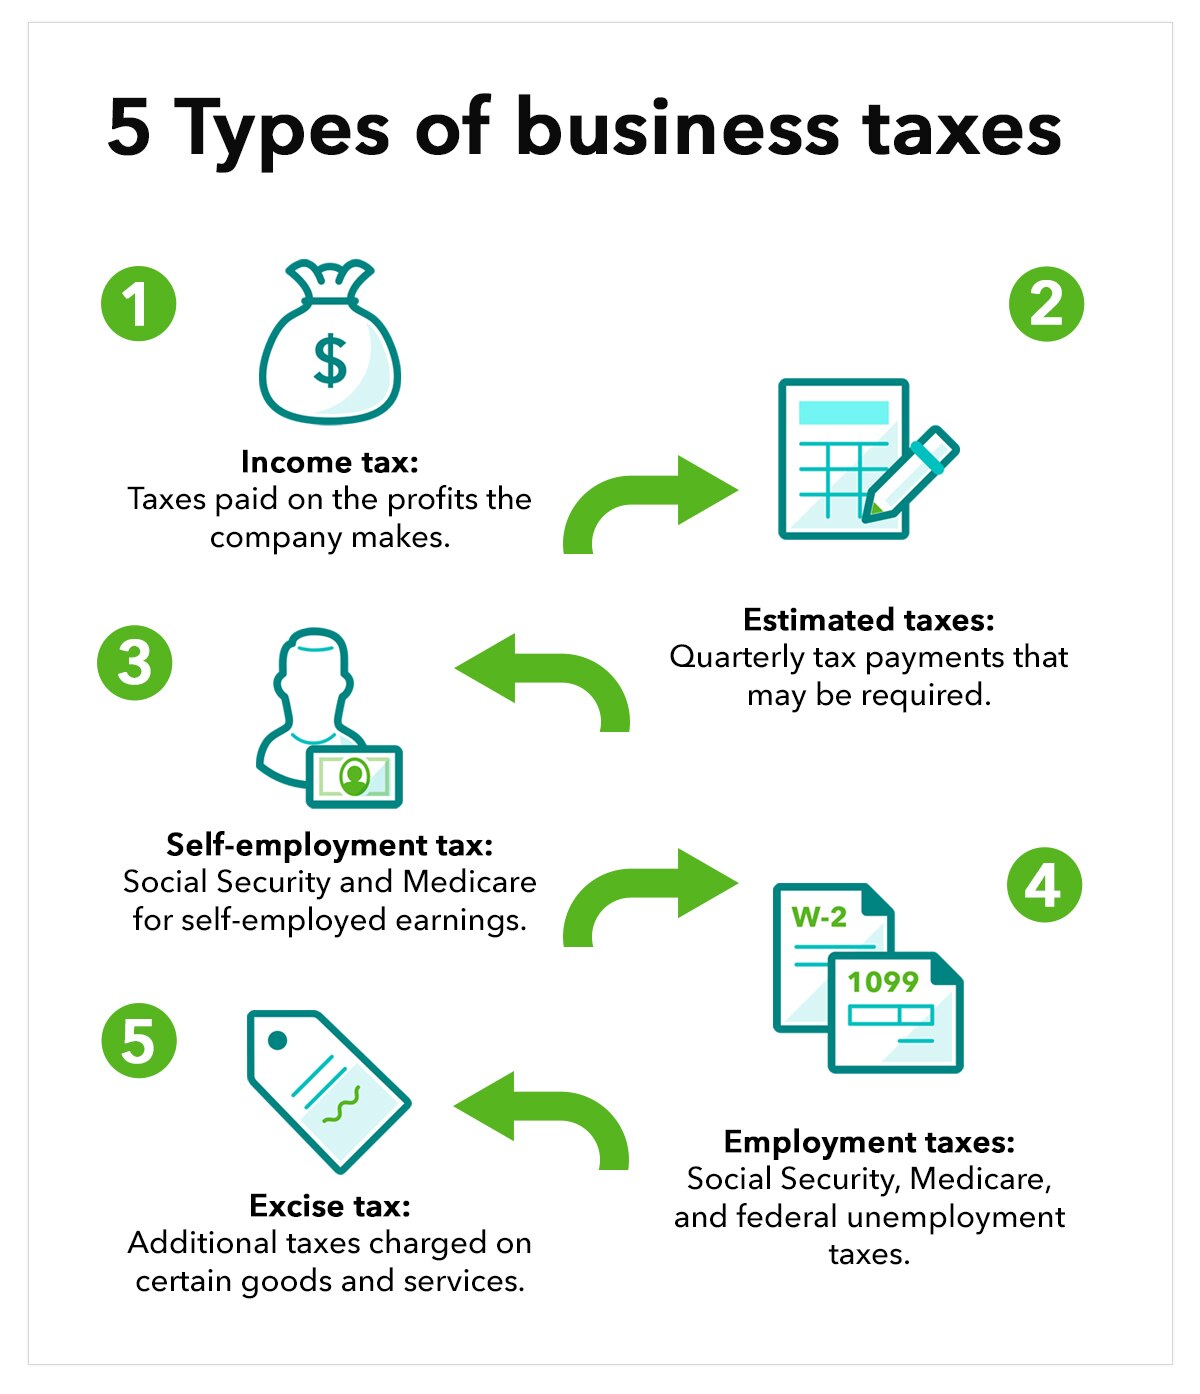
This concept covers everything from how you structure the entity to what deductions qualify, how self-employment tax works, and the quarterly estimated payment schedule that catches most people off guard. The IRS treats small business owners differently than W-2 employees because there's no employer withholding taxes from your paychecks. You have to do it yourself, on your own schedule. Self-employment tax alone is 15.3 percent on your net earnings, and that's on top of whatever income tax bracket you fall into. A lot of people hear that number and immediately want to switch to S-corp election to save money, but that decision isn't free and it adds its own layer of complexity and cost.
How I Actually Handle My Quarterly Payments
I use a combination of a dedicated business checking account and QuickBooks Self-Employed to track everything in real time. The workflow is simple but non-negotiable: every dollar comes in, I automatically split 30 percent into a separate tax savings account, and I review the category allocations at the end of each month. By the time April comes around, I already know exactly what I owe and whether I need to adjust my next quarter's payment. The key thing nobody tells you is that underpayment penalties are calculated per quarter, not annually. If you underestimate your first quarter by even a thousand dollars and don't correct it, the penalty starts accruing immediately. You can catch up later, but the penalty doesn't disappear. I learned this the hard way in 2019 when I had a client whose bookkeeper hadn't been tracking quarterly estimates properly. We owed about four hundred dollars in penalties alone that we could have avoided with a simple spreadsheet reminder set up six months earlier.
Get the Full Details
Entity Structure Decisions That Actually Matter
The most common structural question I get asked is whether to stay a sole proprietorship or become an LLC. These are not the same thing, and confusing them costs people money. An LLC is a legal entity that provides liability protection. It does not change how the IRS taxes you by default. A single-member LLC is still taxed as a sole proprietorship unless you file Form 2553 to elect S-corp status. The S-corp election only makes financial sense once your net profit is roughly above forty thousand dollars. Below that threshold, the added compliance costs of payroll processing, separate tax filings, and potential state-level requirements outweigh any tax savings. I've seen consultants with twenty-five thousand in net profit file S-corp elections anyway, save maybe eight hundred dollars in taxes, and spend three thousand on a bookkeeper to manage the extra paperwork. That's a losing proposition. On the flip side, staying a sole proprietorship when you should be an LLC exposes you personally to liability claims against the business. That distinction matters more than any tax bracket calculation. If you're in a profession where someone could sue you for damages, the LLC structure isn't optional, it's basic risk management.
Deductions People Miss Every Year
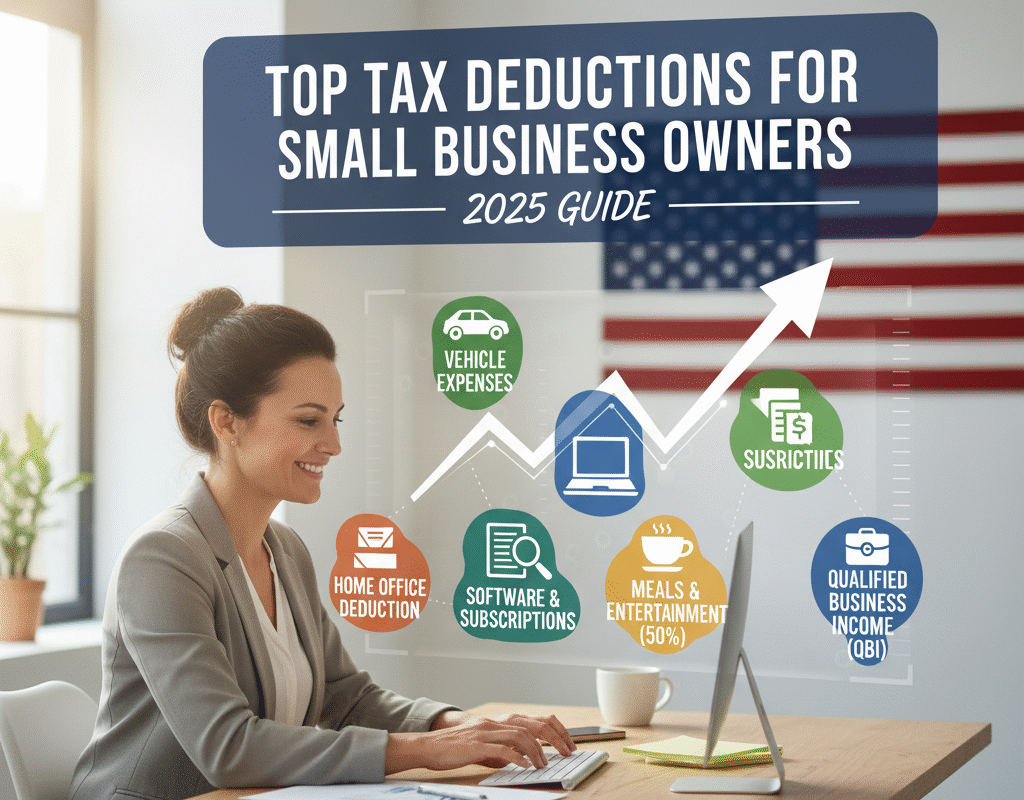
The home office deduction gets mentioned constantly, but most people misunderstand the requirements. You need exclusive and regular use of a space for business purposes. That means a spare bedroom your kids use during the day doesn't qualify. A corner of your living room where you open your laptop every morning for work might, but only if you can document it consistently. The simplified method lets you deduct five dollars per square foot up to three hundred square feet, which works out to a maximum of fifteen hundred dollars without having to calculate actual expenses. The regular method can yield a larger deduction but requires tracking utilities, insurance, and depreciation tied to that portion of your home. Here's something most guides don't emphasize enough: the standard mileage rate is almost always better than tracking actual vehicle expenses unless you drive an extremely fuel-inefficient truck. For 2024, the rate is sixty-seven cents per mile. If you drive ten thousand business miles annually, that's six hundred and seventy dollars. Calculating the actual cost would require tracking gas, maintenance, insurance, depreciation, and repairs, and the result would likely be lower unless your vehicle is particularly expensive to operate. Keep a simple log, either in an app like MileIQ or a basic spreadsheet, and you're set. Another frequently overlooked area is the Section 179 deduction for equipment purchases. You can deduct the full purchase price of qualifying equipment and software bought or financed during the tax year, up to the annual limit, rather than depreciating it over multiple years. In 2024, the limit is one million six hundred and twenty-five thousand dollars, phased out dollar for dollar after that. If your business bought a new laptop, some specialized tools, or even a vehicle under the weight threshold, you may be able to write off the entire cost in year one instead of spreading it over five or seven years.
Common Pitfalls That Cost Real Money
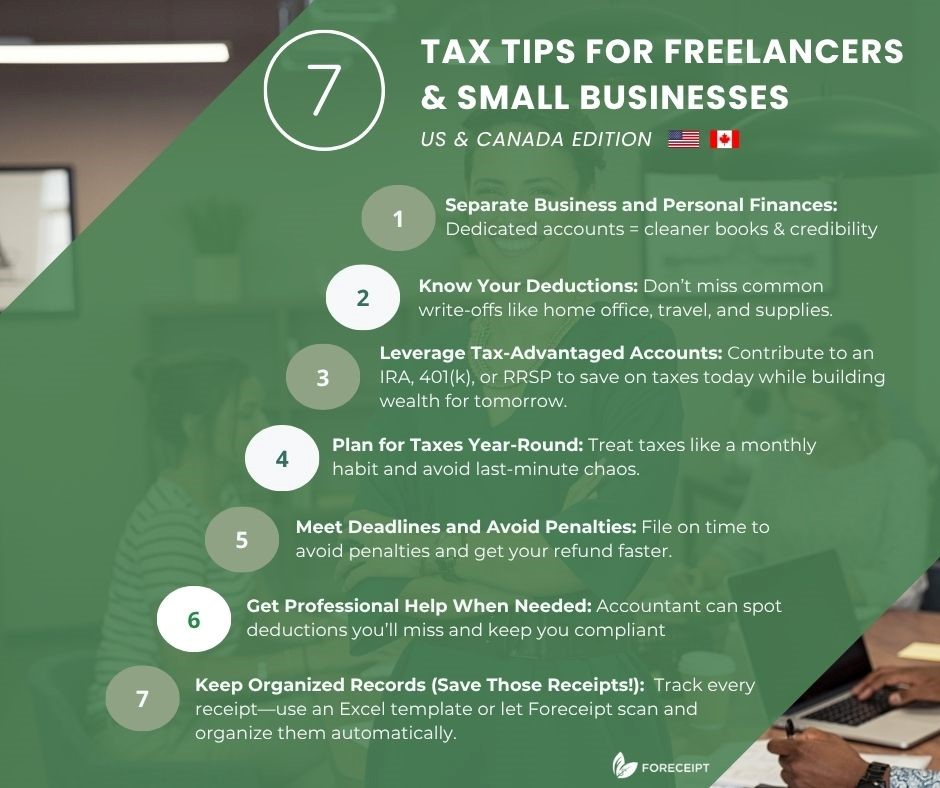
The biggest mistake I see is mixing personal and business expenses on the same account. When you have a single checking account with both personal income and business spending, your deductible expenses become nearly impossible to prove during an audit, and you'll likely miss deductions because they're buried in noise. Open a separate business account the same day you start earning income. It takes approximately fifteen minutes and saves hours of reconciliation later. A second mistake is treating every expense as deductible without understanding the distinction between a repair and an improvement. Fixing a leaky faucet in your office is a repair, fully deductible this year. Replacing the entire plumbing system is an improvement, and you have to depreciate it over several years. The line between the two is blurry enough that it causes problems, especially with older properties where "repairs" often turn into gradual renovations. Quarterly payment timing is another blind spot. The four due dates are April 15th, June 15th, September 15th, and January 15th of the following year. Missing any one of these by even a few days triggers a penalty of half of one percent per month on the underpaid amount, compounding quickly if you're consistently late. I set calendar reminders six months out and pay the day before the due date to buffer for processing delays.
When You Should Probably Hire Someone
DIY tax filing works fine if your business is a simple sole proprietorship with straightforward income and a manageable number of deductions. The moment you add employees, multi-state operations, inventory, or significant passive income streams, the complexity jumps quickly. A good CPA or enrolled agent costs between two and five thousand dollars annually for a small business, but they typically find deductions and strategies that save more than their fee. The break-even point varies, but for most businesses grossing over one hundred thousand dollars, professional help pays for itself. If you do hire someone, ask about their experience with your specific industry, not just their credentials. A generalist who handles restaurants one day and consultants the next may miss deductions that are standard practice in your field. I've had clients switch from a generic firm to one that specializes in their type of business and immediately recovered thousands in overlooked deductions.
A Note on Record Keeping That Actually Works
The IRS doesn't require you to keep records in any particular format, but they do require you to keep them for three to four years depending on the situation. The practical question is whether you can produce them when needed. Digital receipts scanned into a folder system organized by year and category take about twenty minutes a week and eliminate the paper pile that derails so many people during tax season. Cloud storage with a consistent naming convention, something like YYYY-MM-description, makes retrieval trivial. One edge case worth noting: if you receive payments through a platform like Stripe, PayPal, or a marketplace, those platforms issue you a Form 1099-K only if you exceed certain thresholds. But the absence of a 1099 doesn't mean the income isn't taxable. I've seen people exclude six-figure incomes from their returns because a platform never sent them a form, and that doesn't hold up under scrutiny. Track all income regardless of whether you receive a tax document for it.