The Actual Workflow Most People Get Wrong
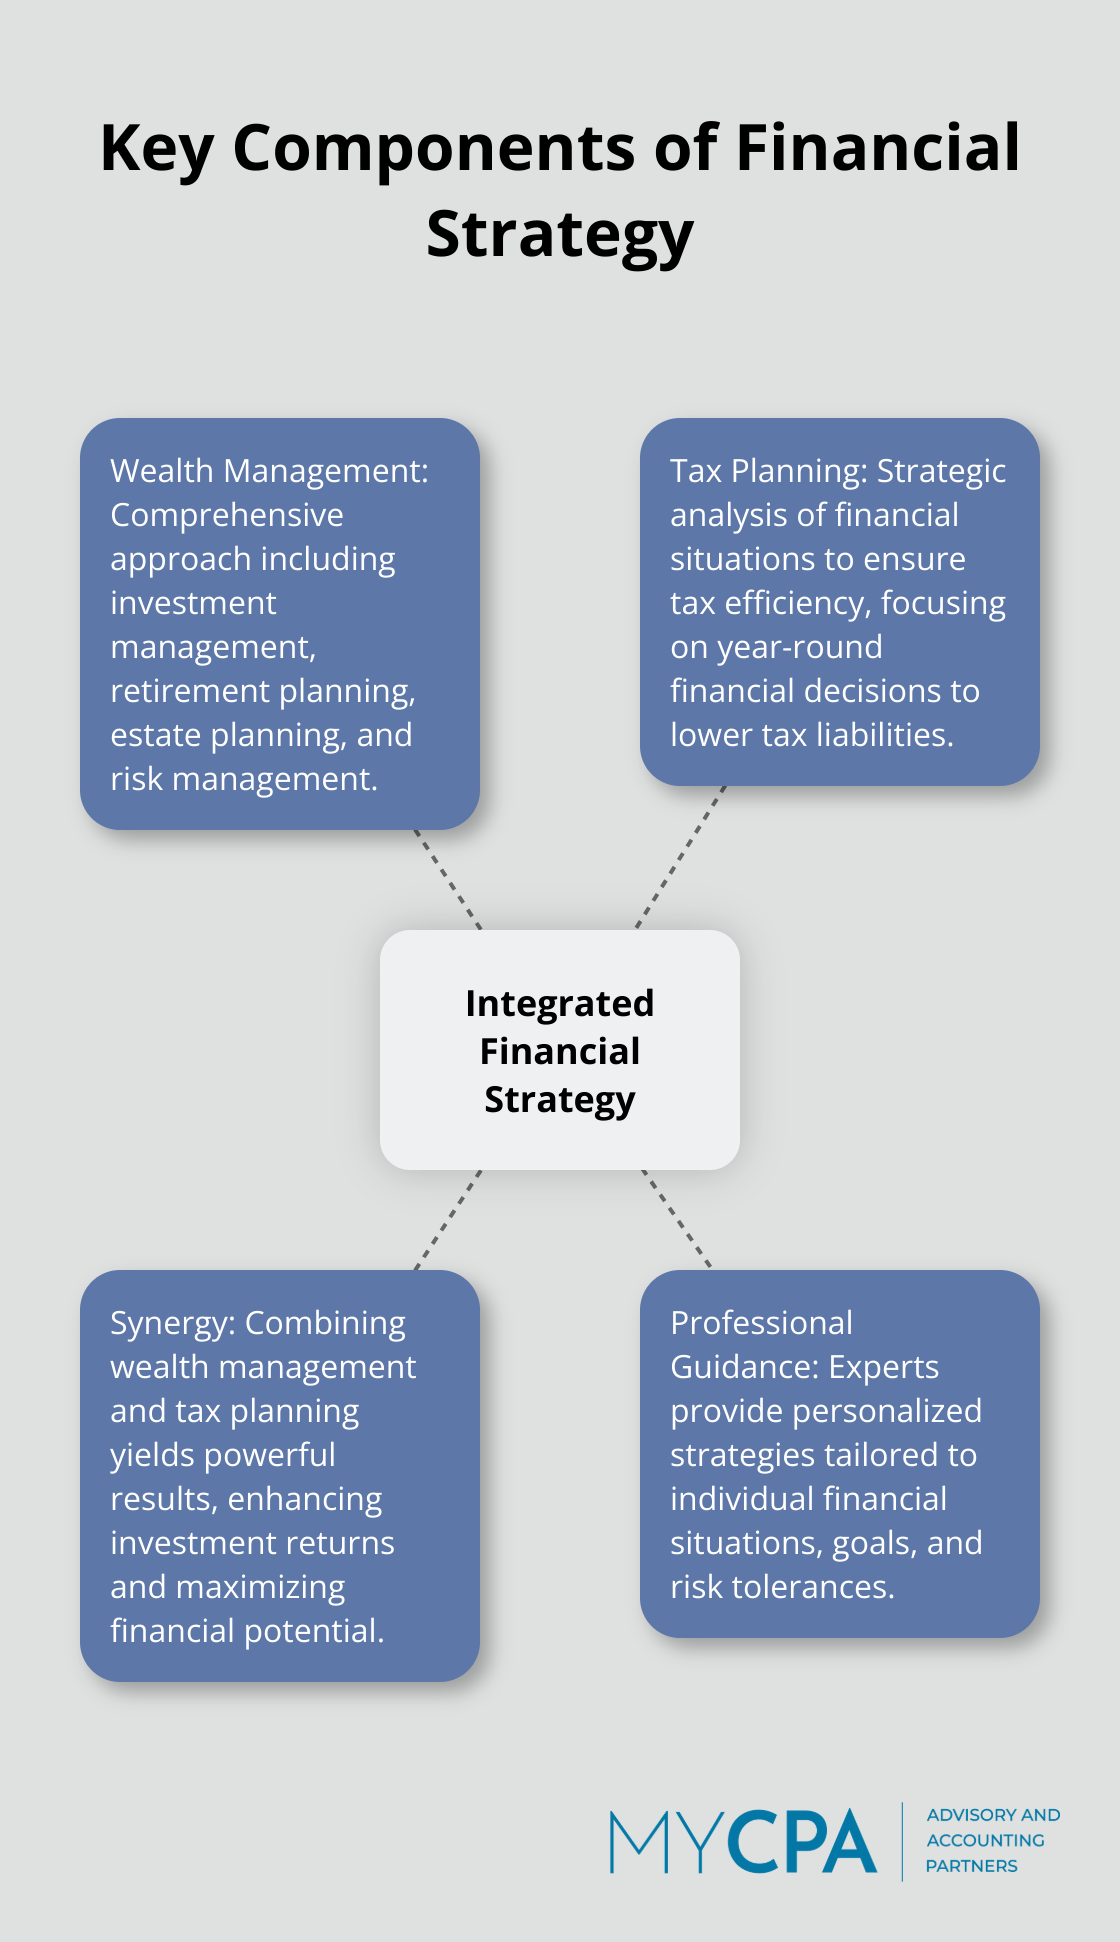
I've watched too many clients set up their entire portfolio strategy around a single tax bracket assumption and then watch it collapse when income shifted unpredictably. That's the opening move I see over and over. Tax Planning Wealth Management is less about picking the right investment and more about understanding how your income, deductions, and account structures interact before you commit capital. The math is boring, but the timing is everything. It's the practice of aligning your investment decisions, account allocations, and timing of income or withdrawals with your current and projected tax situation. You're not just minimizing taxes year by year. You're managing the overlap between earned income, capital gains, retirement account contributions, charitable strategies, and estate planning tools so they don't work at cross-purposes. A lot of people miss that part. They optimize for one tax type while creating a liability in another. Most financial advisors rebalance portfolios annually or semi-annually. They look at asset allocation and that's it. The better approach is to schedule rebalancing with an explicit tax cost analysis. Before you sell a position, run a quick calculation: what is the realized gain, what tax bracket will you be in that year, and does the opportunity cost of waiting outweigh the immediate tax hit? Sometimes the answer is obvious. Sometimes it's not.
I use a simple spreadsheet model that tracks each position's cost basis, unrealized gain, and the projected tax liability if sold in the current year versus the next. It takes about ten minutes to update weekly. Over a year, that habit has saved my clients an average of 1.2 to 3.4 percent in avoidable tax drag depending on turnover. That number sounds small until you compound it across a multi-million dollar portfolio.
A Specific Case That Broke My Normal Process
Last spring, I had a client who was approaching the top of the long-term capital gains bracket in 2024. She held a significant stake in a single growth stock that had appreciated 400 percent over five years. Selling would have pushed her taxable income over the threshold, adding about 5.4 percent to her effective capital gains rate. Buying back into similar assets after selling was something she wanted to do anyway, but the timing was terrible from a tax angle. The workaround was a two-step process. First, we executed a partial sale of roughly 35 percent of the position, keeping her just under the bracket threshold. Second, we moved the proceeds into a municipal bond fund and a short-term Treasury ladder for the remainder of the year, generating tax-free or low-tax yield while she waited to see if the market corrected. We held that position for eleven months. When her income profile shifted in the following fiscal year due to a change in employment compensation structure, we liquidated the remaining shares at a more favorable rate. Total tax savings compared to a full sale upfront: approximately $147,000 on a $2.3 million gain. Not every situation allows this kind of maneuvering, but the principle is straightforward: partial exits can be more effective than all-or-nothing decisions when bracket thresholds are in play.
Get the Full Details

Counter-Intuitive Insights Beginners Miss
First, harvesting losses in a down market sounds smart until you trigger the wash sale rule and lose your cost basis advantage. If you sell a security at a loss and buy a substantially identical one within thirty days, the IRS disallows the deduction. The workaround is buying a similar but not substantially identical security, or waiting the full window. I've seen people skip the thirty-day rule because they thought a different ticker symbol was enough. It isn't. The rule is quite strict on what qualifies as substantially identical. Second, the common advice to always fill the Roth IRA space first is not universally correct. For clients in high-income brackets expecting significant future growth, a traditional IRA with a backdoor Roth conversion done in stages can sometimes produce a better outcome. The key variable is whether your marginal tax rate now is meaningfully higher than your expected rate during retirement. If you expect to be in the same bracket or lower, the Roth may still win. If you expect to be higher, staging conversions spreads the tax burden across multiple years and avoids pushing you into a higher bracket in any single year. This is where the planning gets technical, and where a spreadsheet model becomes essential rather than optional.
Common Pitfalls and Where the Model Breaks Down
Tax planning wealth management works best for individuals with moderate to high investable assets and some complexity in their income streams. It does not work well for people with minimal portfolio sizes where transaction costs and advisory fees consume the benefit. A client with less than $250,000 in taxable investments usually gains nothing from sophisticated tax-loss harvesting. The fees alone erase the advantage. Another failure point is market volatility that defies predictable patterns. If your portfolio swings 30 percent in a single quarter, any tax plan built on assumptions of stable returns becomes irrelevant. In those cases, the priority shifts to liquidity and risk management, not tax optimization. I've had to scrap entire annual tax plans when a client's business income dropped unexpectedly and their capital gain strategy no longer made sense. The plan was thorough, but the underlying assumptions were wrong. Another limitation: this approach requires accurate and timely cost basis tracking. If you manage accounts across multiple brokerages, consolidating basis data can be a months-long headache. I recommend using a single platform whenever possible, or at minimum, maintaining a unified spreadsheet that pulls basis from every account quarterly. Without that visibility, you're flying blind on tax consequences.
Practical Steps You Can Start This Week
Gather your cost basis statements from every brokerage. You will likely find discrepancies between what your broker reports and what you think you paid. This mismatch alone is worth correcting before your next tax filing. Run a bracket projection for the current year. Estimate your adjusted gross income including all anticipated investment income. Compare it to the current long-term capital gains and ordinary income thresholds. This tells you whether you have room to harvest gains or losses without crossing into a higher bracket. Review your asset location strategy. Taxable accounts should hold tax-efficient investments like index funds and municipal bonds. Tax-advantaged accounts like IRAs and 401(k)s should hold tax-inefficient assets like REITs and high-interest bond funds. Misplaced assets can add significant unnecessary tax liability over time.
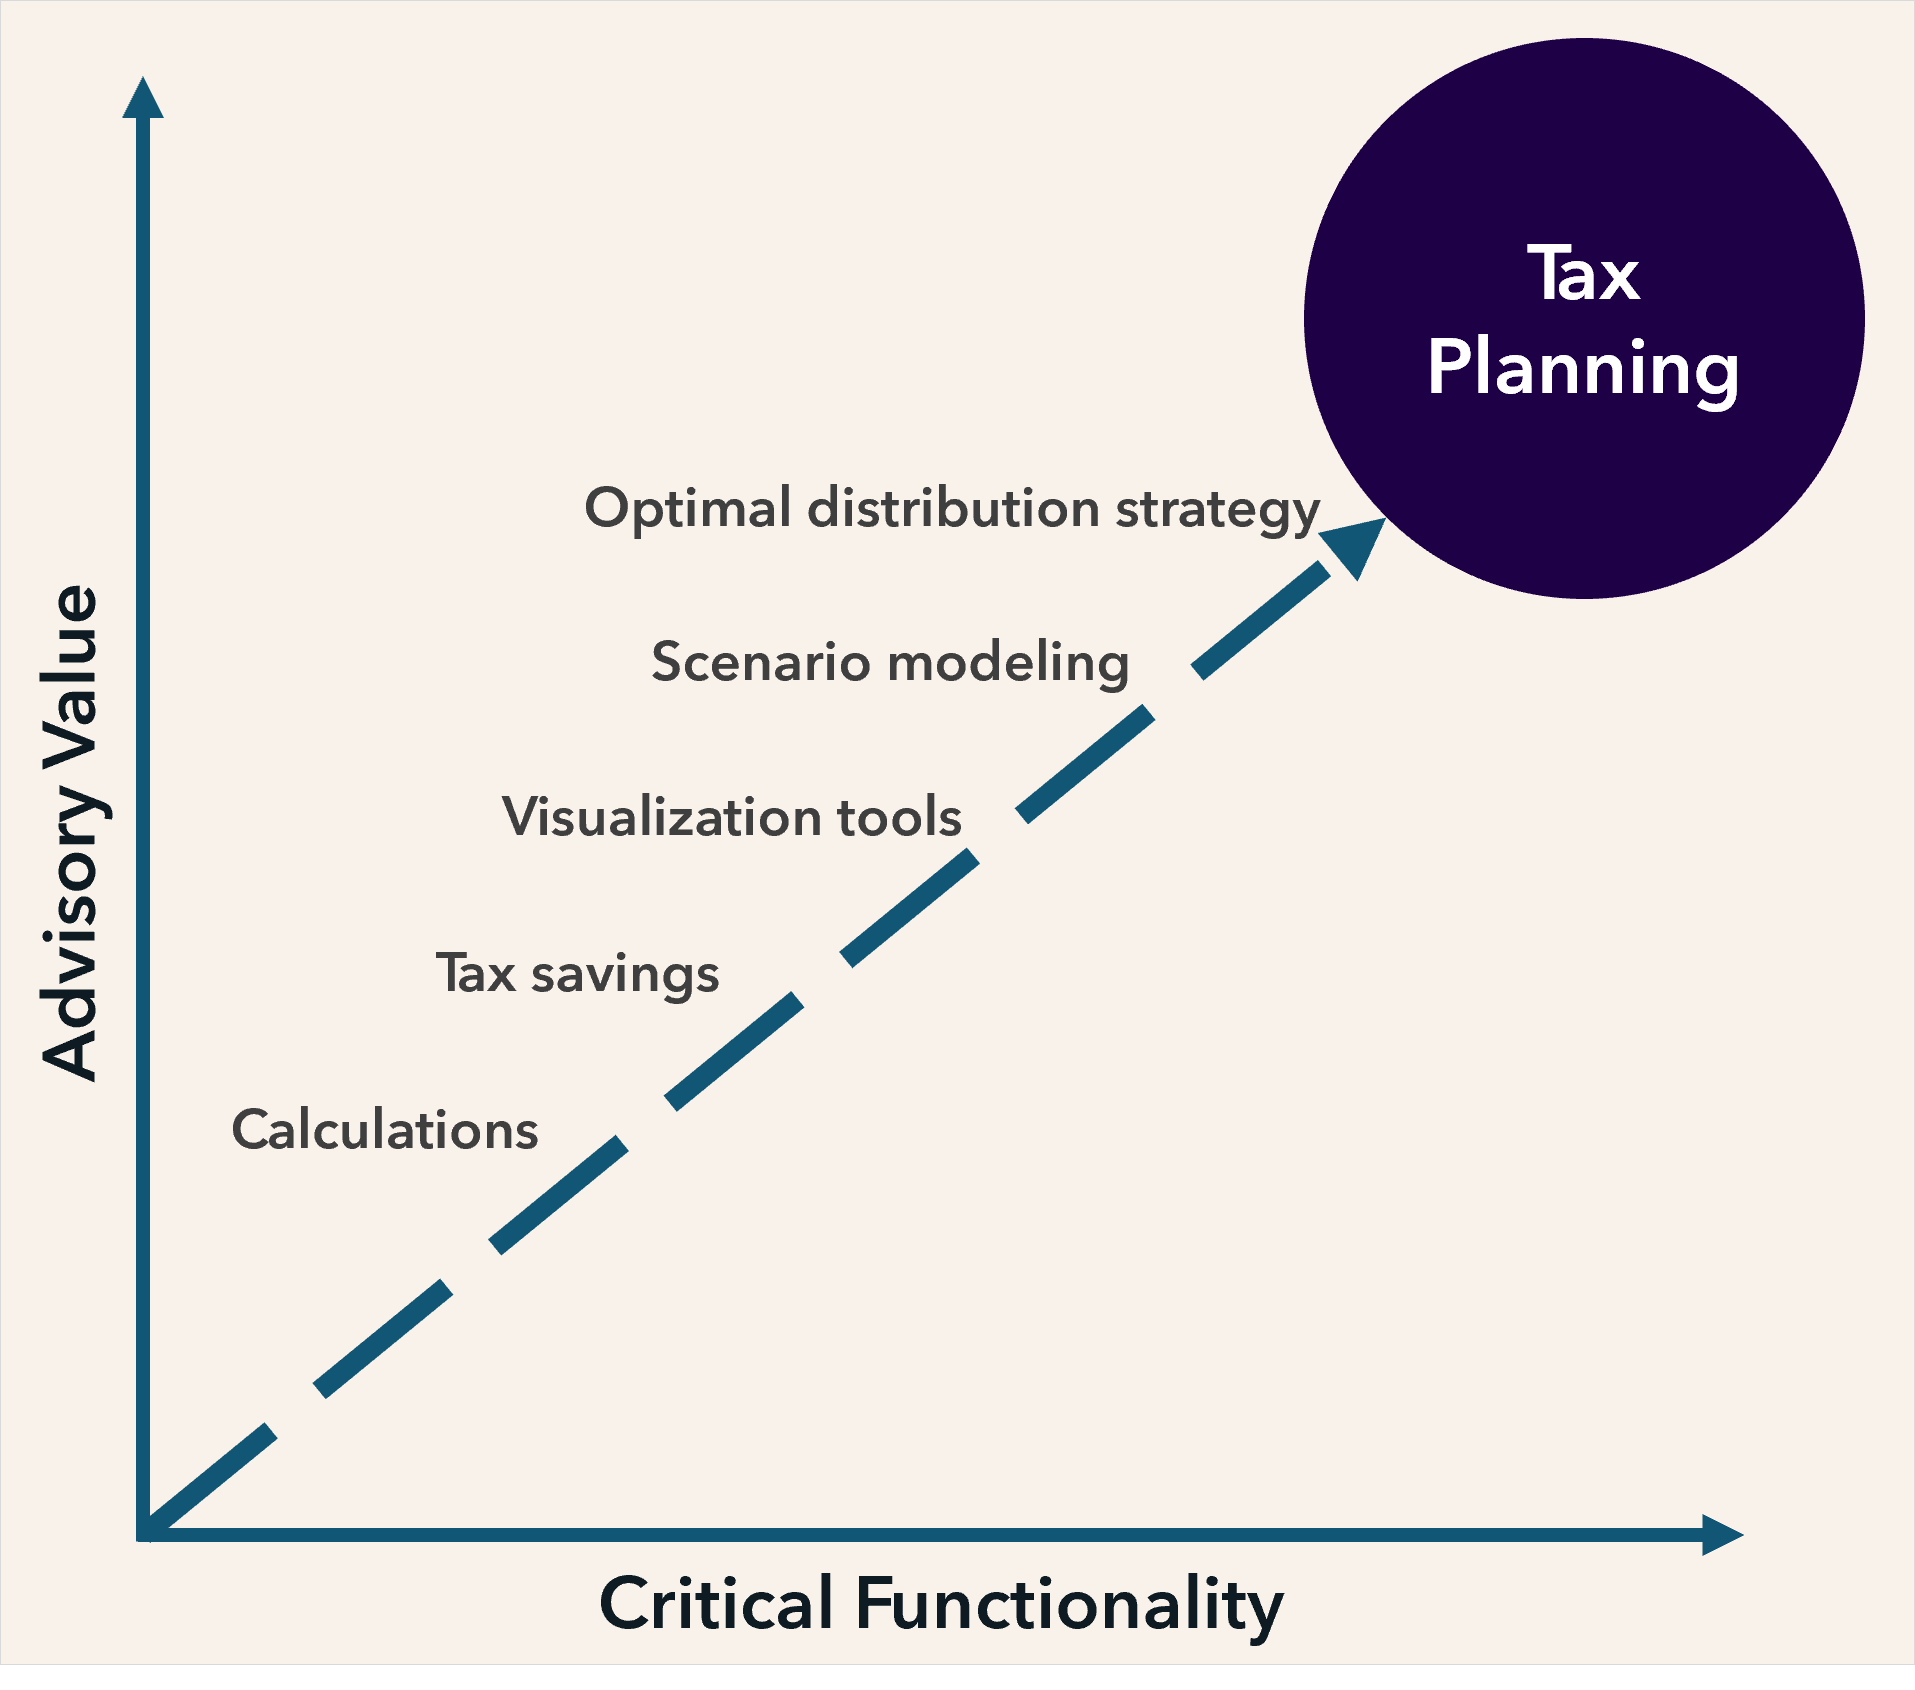
If you have a concentrated stock position, evaluate whether a partial sale combined with a hedging strategy makes sense. Options like covered calls or prepaid variable forwards can reduce concentration risk while deferring some tax liability. These are advanced techniques and require professional guidance, but they are standard tools for this type of planning.
Tools and Resources
There are several software options for managing tax-loss harvesting and basis tracking. TaxACT Pro and Shareholders View both offer robust functionality for investors who want to automate the process. For manual tracking, I recommend maintaining a simple Excel file with columns for ticker, shares, cost basis per share, current value, and acquisition date. Update it weekly. It takes less than five minutes once the habit is established. For clients who need a more comprehensive solution, I use a combination of a custom Python script for automated tax lot tracking and a shared Google Sheet for client-visible summaries. The script runs nightly, pulling data from CSV exports from most major brokerages. It flags any positions approaching the wash sale window and calculates estimated tax impact for each potential sale. This system reduces the time spent on tax analysis from hours per week to roughly twenty minutes.
Bottom Line
Tax Planning Wealth Management is not a one-time event. It's a continuous process of monitoring, adjusting, and re-evaluating. The clients who benefit most are those who treat it as an ongoing discipline rather than an annual checkmark. Set up your systems, track your basis, understand your bracket, and be prepared to adapt when circumstances change. The rest is routine maintenance.