Stop Wasting Your Month-End Close
Most small business owners end up with spreadsheet chaos. You have three different tabs for expenses, your bank reconciliation is a myth, and your "profit and loss" doesn't match what the bank says you earned. This happens because nobody built the right skeleton before they started throwing data at it. A well-structured template for accounting modern workflows solves this. It forces every transaction into a single source of truth, calculates your balances automatically, and gives you a clean set of financial statements without the manual copy-paste work that causes errors.Template For Accounting Modern
Here's the thing about building one yourself. You don't need fancy software to start. You need a system that actually works for your business. I've built and rebuilt these templates for dozens of companies over the years. Some use them successfully for years. Others abandon them within six months because the template was too rigid or too loose. The difference comes down to structure. A proper template needs four core pieces. A transaction log that captures every single entry with date, account, description, amount, and type. A chart of accounts that matches your actual business structure, not some generic list from the internet. Automatic calculations that roll your transaction data into summarized financial statements. And reconciliation sections where you match your records against your bank statements each month. The biggest mistake I see is building the chart of accounts backward. People start with categories that feel right for their business, then try to force their transactions into those buckets. Instead, you should look at your last six months of actual bank statements and build your chart of accounts from what you've already been spending and earning money on. This takes one afternoon and results in a system that maps cleanly to real life. I had a client who tried to use a pre-made template from a business website and spent three weeks arguing with it because the account categories didn't match anything in her actual books. We scrapped that approach entirely and built from her bank data. The template for accounting modern practices that I built for her took four hours to set up and has run without modification for eighteen months.
Building the Transaction Log
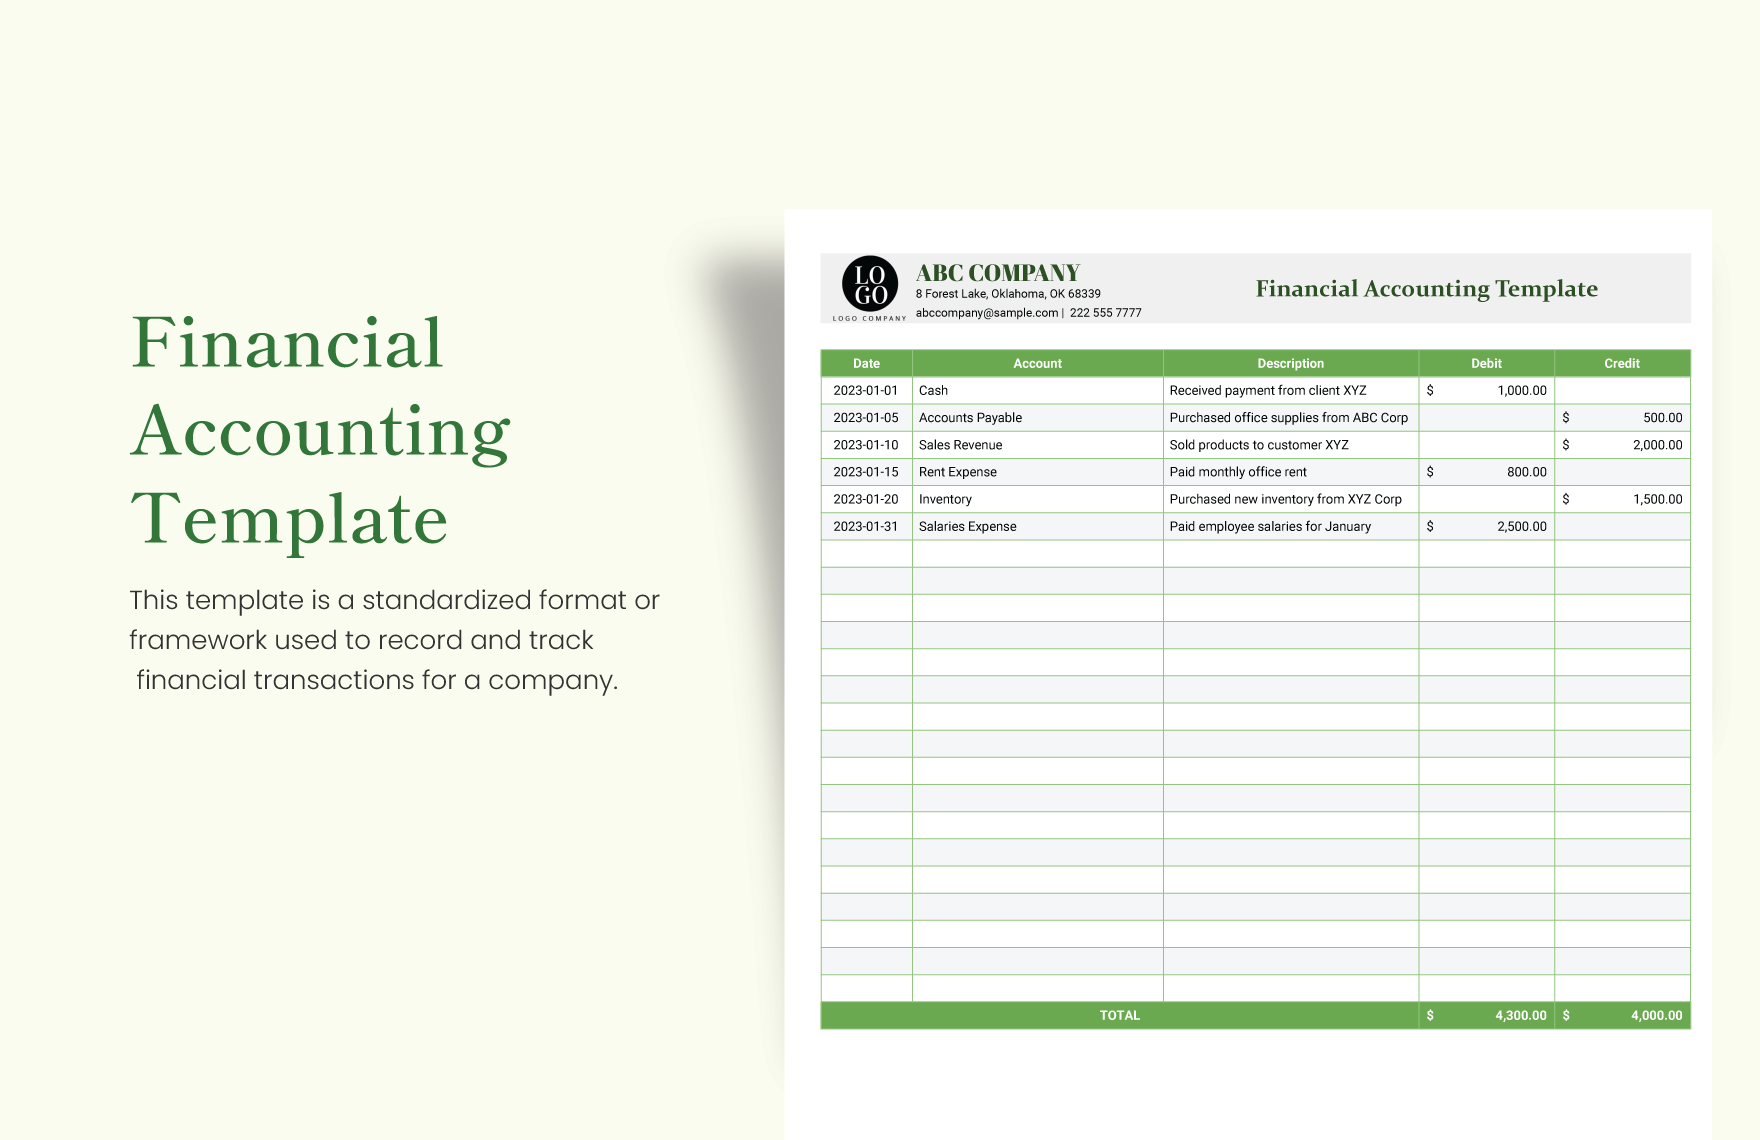
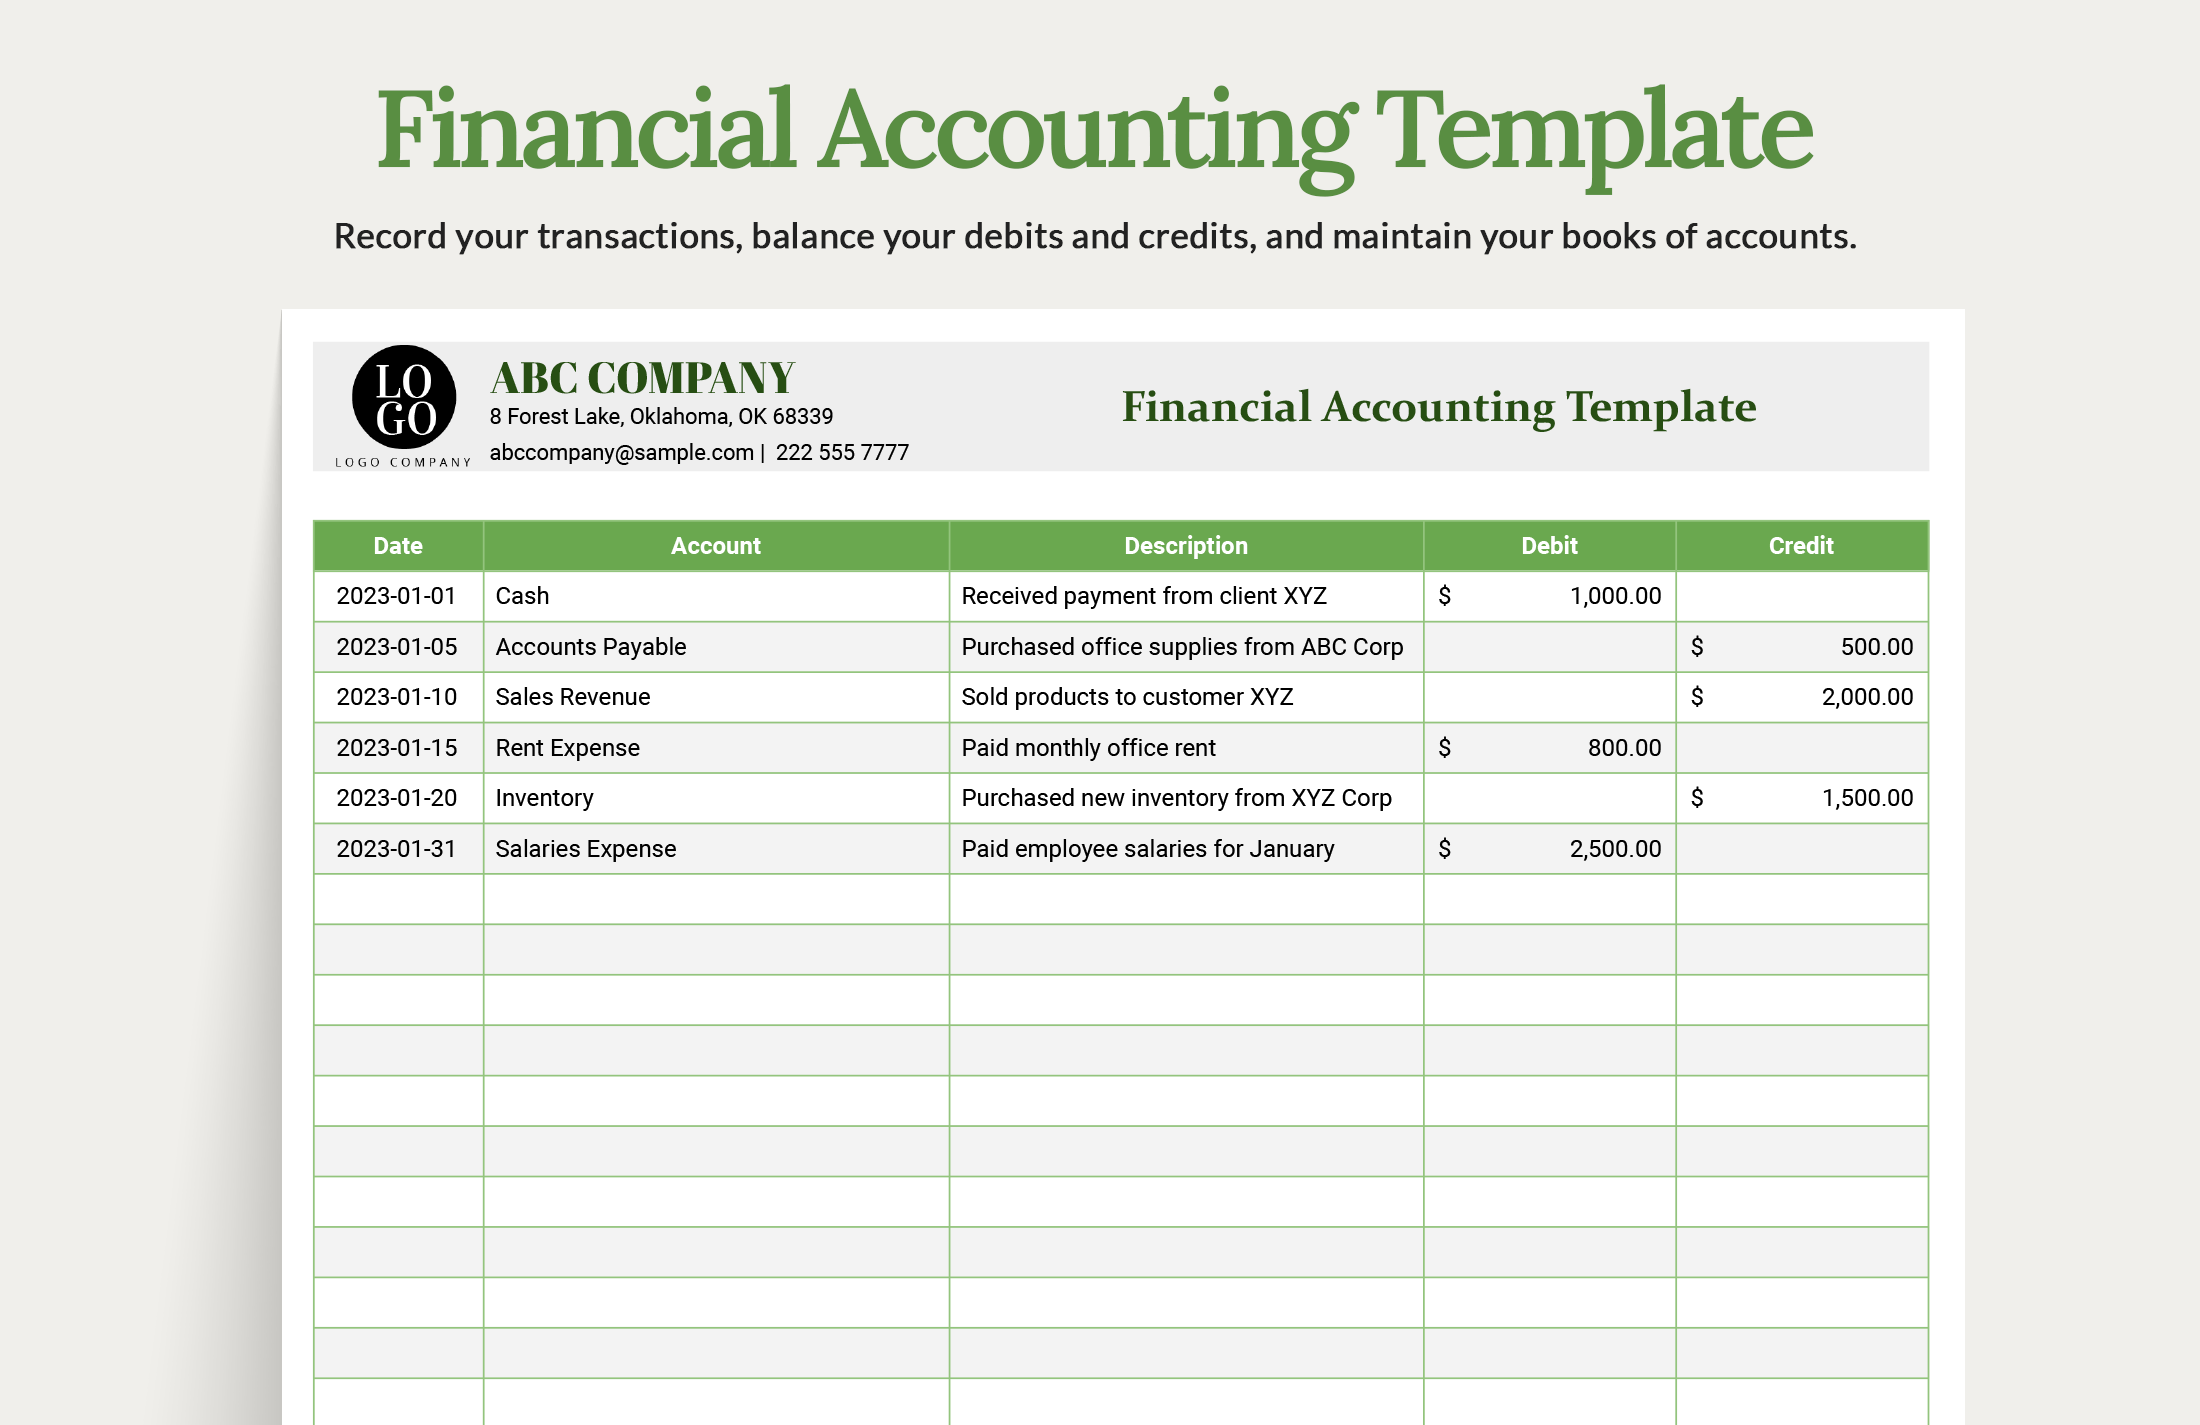
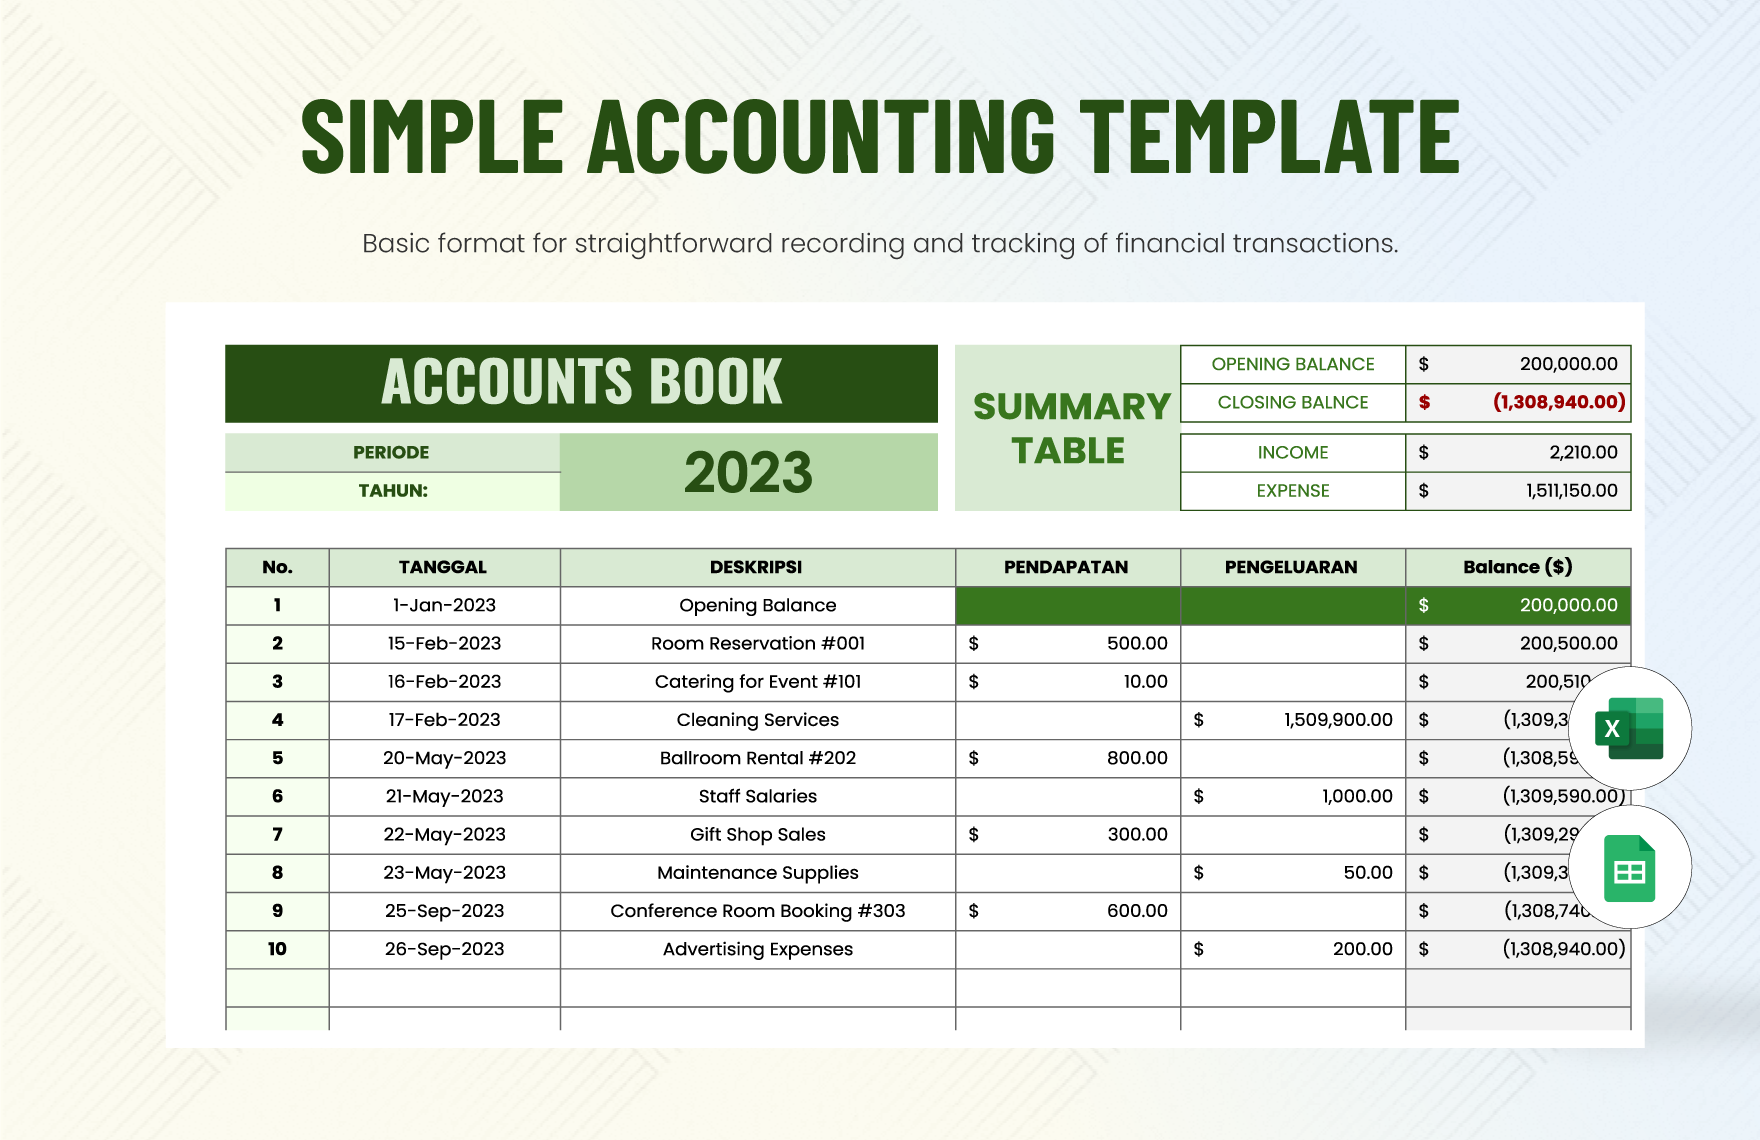
Your transaction log is the foundation. Everything else depends on it. Every transaction you record here feeds directly into your income statement and balance sheet. There should be no other input point. If you're recording transactions in three different places, you already have problems. Set up columns for: Date, Entry ID, Account, Description, Debit, Credit, Type, and Reconciled Status. That's it. Do not add columns for "priority" or "importance" or any other subjective field. Those are noise. The Entry ID should be a simple sequential number. You can generate it with a formula like ROW()-1 if you put the header in row 1. The Reconciled Status column uses a dropdown with Yes and No values to track which transactions you've matched to your bank statement. Use data validation on the Account column to create a dropdown from your chart of accounts. This prevents typos and ensures every entry references a valid account. In Google Sheets you can set this up under Data > Data validation. In Excel it's under Data > Data Validation. Both work fine. The point is to stop letting people type in arbitrary account names and create duplicates that break your summaries later.
Chart of Accounts Structure
Your chart of accounts determines how your financial statements are organized. Keep it practical. Most small businesses only need thirty to fifty accounts to run cleanly. The temptation is to create sub-accounts for everything. Office Supplies Expense, Office Supplies - Cleaning, Office Supplies - Break Room. This looks organized until you need to generate a report and realize you have twelve variations of the same expense scattered across your sheets. Use a numbering system that makes sense. Assets in the 1000s, liabilities in the 2000s, equity in the 3000s, revenue in the 4000s, cost of goods sold in the 5000s, operating expenses in the 6000s. This isn't religious. It's just a convention that every accountant understands immediately. When you hand your books to a CPA or tax professional, they won't need to ask you what your account numbers mean. One thing people consistently mess up is mixing balance sheet and income statement accounts in the same category groups. Assets and liabilities belong together. Revenue and expenses belong together. Don't create mixed categories like "Assets and Loans" or "Expenses and Revenue." Keep them separate and your balance sheet will balance itself. Well, almost. More on that shortly.
Get the Full Details
Automatic Financial Statement Calculations
This is where the template earns its keep. You should never manually calculate your totals. Every number on your income statement and balance sheet should pull from your transaction log using formulas. If a single transaction is wrong, the financial statements should update automatically when you fix that one entry. For your income statement, use SUMIFS formulas that filter your transaction log by account and date range. Something like: =SUMIFS(TransactionLog!E:E, TransactionLog!C:C, "6010", TransactionLog!A:A, ">="&StartDate, TransactionLog!A:A, "<="&EndDate)
This pulls all debits from account 6010 within your selected period. Adjust the column references to match your actual sheet layout. Copy this pattern for every account on your income statement. Your balance sheet works the same way but you'll also need running totals because balance sheet accounts accumulate over time rather than resetting each period. Here's a counter-intuitive insight most beginners miss. Your balance sheet should always balance by design, not by accident. If your transactions are recorded correctly with debits equaling credits in every entry, the sum of all asset accounts will always equal the sum of all liability and equity accounts. This isn't a theory. It's double-entry bookkeeping. But many template builders don't set up the validation to prove this to themselves. Add a row at the bottom of your balance sheet that subtracts total liabilities and equity from total assets. If this number isn't zero, something is wrong with your transaction log or your formulas are pulling from the wrong range.
Reconciliation Workflow
This is the part everyone skips and then regrets. Your reconciliation section compares your transaction log against your actual bank or credit card statements. You mark each transaction as reconciled once it matches. This catches errors, missing entries, and duplicate recordings. Set up a reconciliation tab with columns for: Date, Transaction Description, Amount (from your log), Amount (from bank statement), Match Status, and Notes. Use conditional formatting to highlight mismatches in red. When your log total and your bank total match, the difference should be zero. If it isn't, either you missed a transaction in your log, recorded something incorrectly, or the bank statement has an error. Usually it's the first one. I've spent far too many hours tracking down discrepancies caused by a single transposed digit. $1,247 recorded as $1,274. The reconciliation catches this immediately. Without it, the error sits there silently eating into your reported profit until someone notices during tax season. And they usually won't notice until the numbers look vaguely wrong and you can't explain why.
Common Pitfalls and Workarounds
Formula errors are the most frustrating problem. A broken reference, a changed range, or a copied cell that doesn't adjust properly can silently corrupt your entire financial statement. I recommend wrapping every critical formula in an IFERROR function that returns a clear error message. This way you know immediately when something is wrong instead of discovering it three months later when your numbers don't add up. Another issue is duplicate entries. Someone records a transaction, then records it again because they forgot they already did. Your totals are now inflated and nobody notices. Add a uniqueness check on your Entry ID column. In Google Sheets you can use =COUNTIF(EntryIDRange, EntryID) and flag anything greater than one. This prevents accidental duplicates. The version control problem is real too. If two people edit the same template, you can lose work or create conflicting data. Use cloud storage with version history. Google Sheets or Excel Online both handle this well. Turn on version history and review changes weekly. Don't let the template sit unreviewed for months while transactions accumulate.
When a Template Isn't Enough
I should be honest about the limitations here. A spreadsheet template works well for small businesses with straightforward transactions, a single bank account, and maybe one or two credit cards. It breaks down when you have multiple entities, inventory tracking that requires perpetual systems, multi-currency operations, or complex revenue recognition rules. In those cases, dedicated accounting software like QuickBooks, Xero, or FreshBooks is faster and less error-prone than any template you can build yourself. Even in those situations though, a simple transaction log template can serve as a supplemental tool. Some business owners maintain a detailed expense tracking template alongside their main accounting software to catch things the software misses. A good example is project-based costs that need to be tracked separately from regular expenses. The software handles the bookkeeping. The template handles the operational detail. Templates also become problematic when you scale past a certain point. The manual entry burden grows linearly with your transaction volume. At a certain volume, the time spent entering and verifying data exceeds the cost of automated accounting software. For most businesses this crossover point is around $200,000 to $500,000 in annual revenue. Below that, the template approach is perfectly viable. Above that, you should seriously consider upgrading.
There's also the issue of data security. Spreadsheet files stored locally can be lost, corrupted, or accessed by unauthorized people. Cloud-based solutions with proper access controls mitigate this risk. If you're using a template, store it in a secure cloud folder with appropriate permissions. Never email template files between collaborators. That's how versions diverge and data gets lost.
What to Download and How to Use It
If you're building from scratch, start simple. Create one spreadsheet with four tabs: Chart of Accounts, Transaction Log, Income Statement, and Balance Sheet. Link them together with basic SUMIFS formulas. Test it with a month of real data before you rely on it. I know this sounds obvious but most people skip the test phase and then discover their formulas are wrong when tax season arrives. For those who want a starting point, I've made a basic version available. It includes a pre-built chart of accounts with common small business categories, a transaction log with data validation, automatic income statement and balance sheet calculations, and a reconciliation section. The file is formatted for Google Sheets but works in Excel with minor adjustments. You can find it on most template marketplaces or build your own from the structure outlined above. The real value of any template for accounting modern purposes isn't the spreadsheet itself. It's the discipline of recording transactions daily, reconciling monthly, and reviewing your financial statements weekly. The template enforces that discipline. Without it, the discipline tends to fade quickly. Build the system. Maintain the system. Let the system do the work.