Getting Started
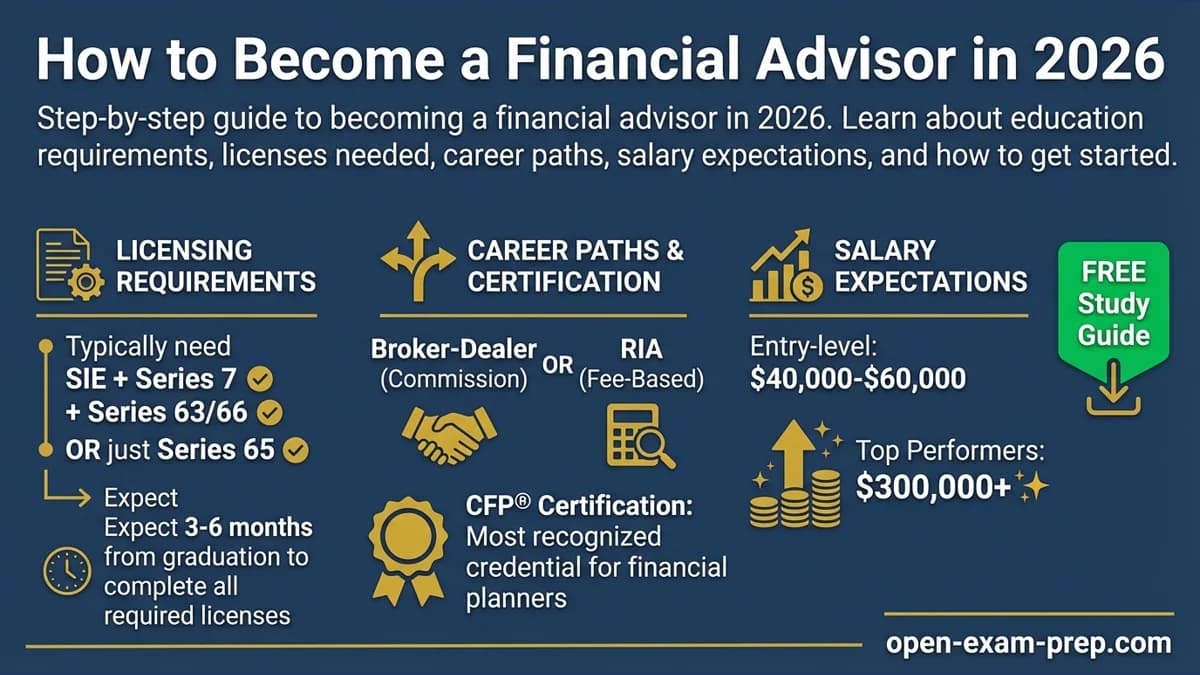
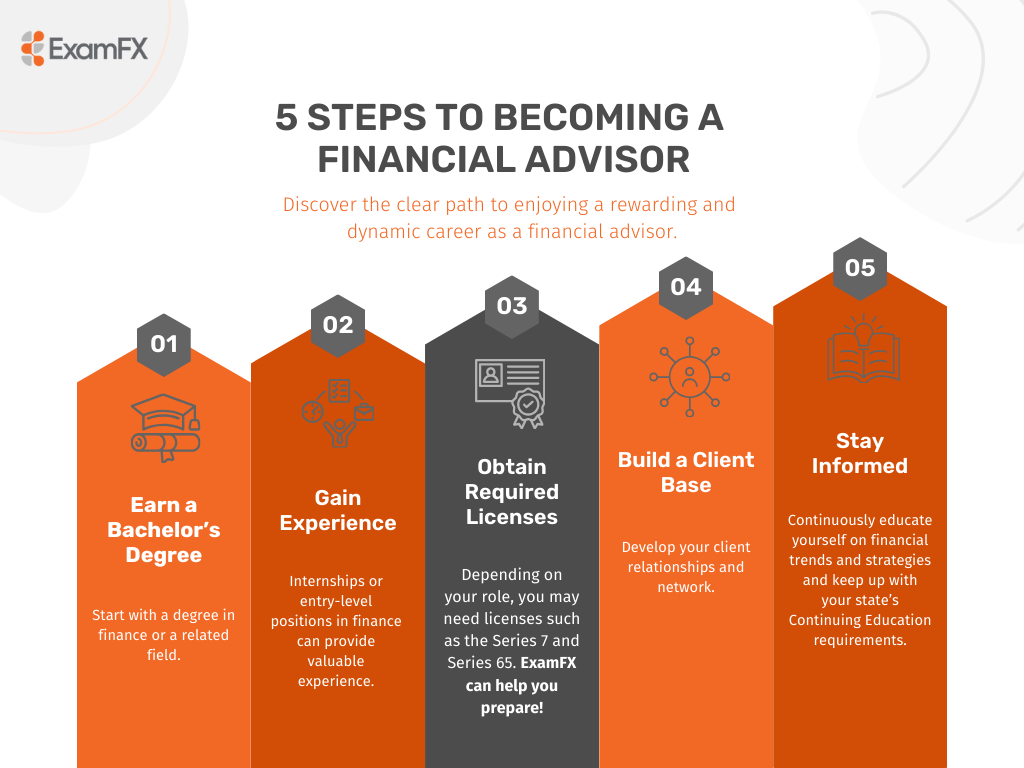
Becoming a financial advisor is straightforward if you can tolerate paperwork. The licensing landscape varies by country but generally requires you to pass at least one exam and register with a regulatory body. In the US, that means FINRA for most entry points. In the UK it's the FCA and SoA, with different qualification pathways depending on whether you do the apprenticeship route or go the academic way. I want to skip the motivational fluff and just tell you what you actually need to do. First you decide which jurisdiction you'll operate in and what kind of advice you want to give. The products you recommend change everything about your education path. A retirement planning focus looks very different from an insurance-based compensation model. Most people start with either the Series 65 in the United States or the CISI Level 4 Diploma for UK-based advisors. The 65 combines the 63 and the 66 and gives you full registration as an investment adviser representative. It covers federal securities law, ethical practices, and investment vehicle fundamentals. I found that the ethics section was the easiest part and also the part where people consistently score poorly because they underestimate it. You do not want to be the advisor who fails on conflict of interest questions.
After passing the exam you need to sponsor yourself through a firm. That means finding a registered investment advisor or broker-dealer willing to take you on. This is where the process gets annoying. Some firms have waiting lists. Others want you to bring clients with you. The smaller RIAs tend to be more flexible with entry-level candidates but they usually require you to handle a wider range of tasks than at a big firm. One edge case I ran into: you can technically sit for the Series 65 without being sponsored, but you can't activate the license until you're associated with a firm. The exam score stays valid for two years after you pass it. This creates a window where people study ahead of time, which is smart, but then they lose the score if they can't find sponsorship quickly enough. I knew someone who wasted four hundred dollars on a retake because their target firm had an extended hiring review period. My workaround was to apply to at least five firms during the final month of study so I had backup options if the first choice stalled out. Once you're sponsored and your license is active, there's ongoing compliance work that most people don't expect. You'll need background checks renewed periodically, continuing education every year, and your firm will run its own internal reviews. The CE requirement for the Series 65 is two years of ethics, product knowledge, and regulations covering at least twelve hours. Many firms automate this but the actual learning matters less than completing it on time. Missing CE deadlines can trigger compliance flags that slow down client onboarding.
Advanced Considerations That Most Beginners Miss
The CFP certification is the gold standard but it's expensive and time-consuming. You need a bachelor's degree from an accredited institution, complete a CFP-registered education program, pass the CFP exam, and have two thousand hours of professional experience. Some of that experience can be waived if you've already spent time in the industry in certain advisory roles. The whole process typically takes between eighteen months and three years depending on how much you already have on your plate. Here's something counterintuitive: having a CFP before you have solid practical experience can actually make you worse at advising people. You learn theory in isolation and build habits around textbook scenarios that rarely happen in real client meetings. I'd recommend getting licensed and working for at least a year before pursuing the CFP. By then you'll know exactly where your knowledge gaps are and the exam will feel more manageable. Another thing nobody talks about is the fiduciary standard versus suitability standard distinction. If you operate under a brokerage model, you're held to suitability. You have to recommend products that are suitable for the client but you don't have to put their interests above your own compensation. Under a fiduciary model as an RIA, you legally have to put the client first. This changes how you present recommendations, how you disclose conflicts, and how you structure your fees. Most clients don't understand this difference and many advisors don't either until they get sued or audited.
Get the Full Details
Technology has changed the game considerably. Practice management software like Redtail or Salesforce Financial Services Cloud handles client documentation, communication logs, and compliance reporting. Learning one of these systems before you start your first day saves weeks of frustration. I spent my first three months manually tracking everything because I didn't bother learning the CRM during onboarding. It wasn't funny after week six when a compliance audit came up and I couldn't produce basic correspondence records. There's also the question of compensation models. Fee-only advisors charge clients directly for advice. Fee-based advisors charge fees but can also earn commissions on product sales. Commission-only models are mostly dead now for new registrations since most firms phased them out after Reg BI and the fiduciary rule discussions. Your compensation choice affects your clients' trust and your own ability to give unbiased recommendations. I've seen advisors struggle with this transition when they move from commission-based firms to fee-based RIA setups. The income drop in the first year is real and nobody warns you about it. If you're starting from zero and the licensing route feels too steep right now, you could begin as an associate or paraplanner under a licensed advisor. This gives you industry exposure, helps you build relationships, and lets you figure out whether you actually want this career before investing money in exams and certifications. It's not a failure path. It's how most successful advisors actually enter the field without burning through their savings on unnecessary credentials.