Getting TDR Right When the Debtor Can't Pay
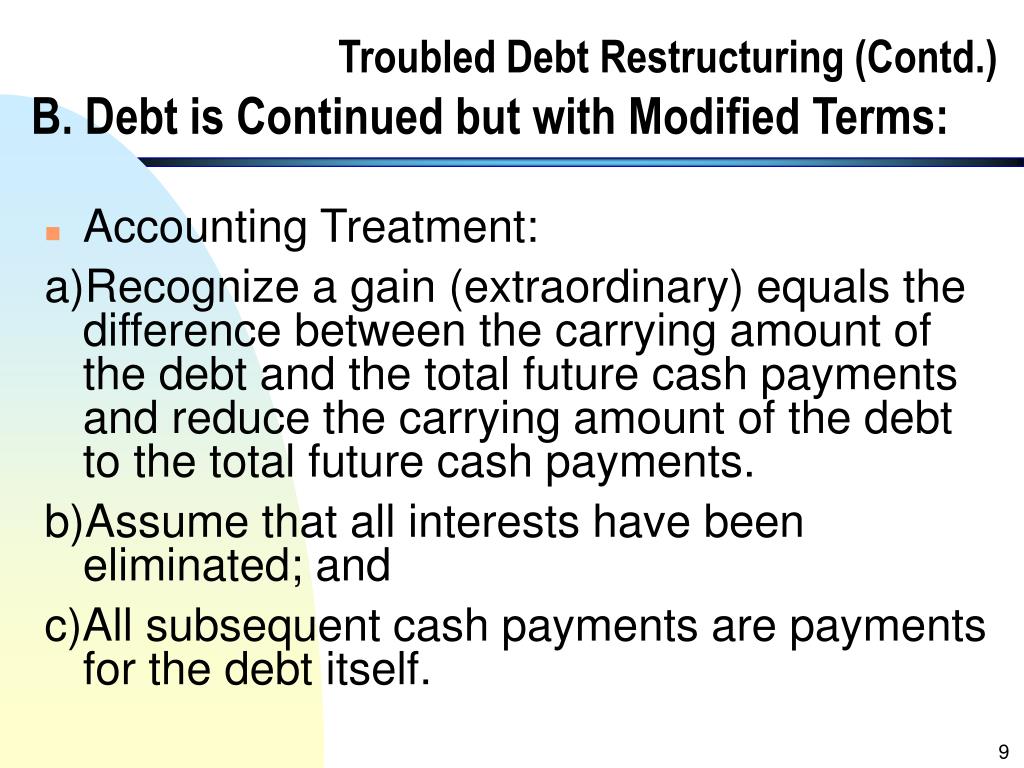
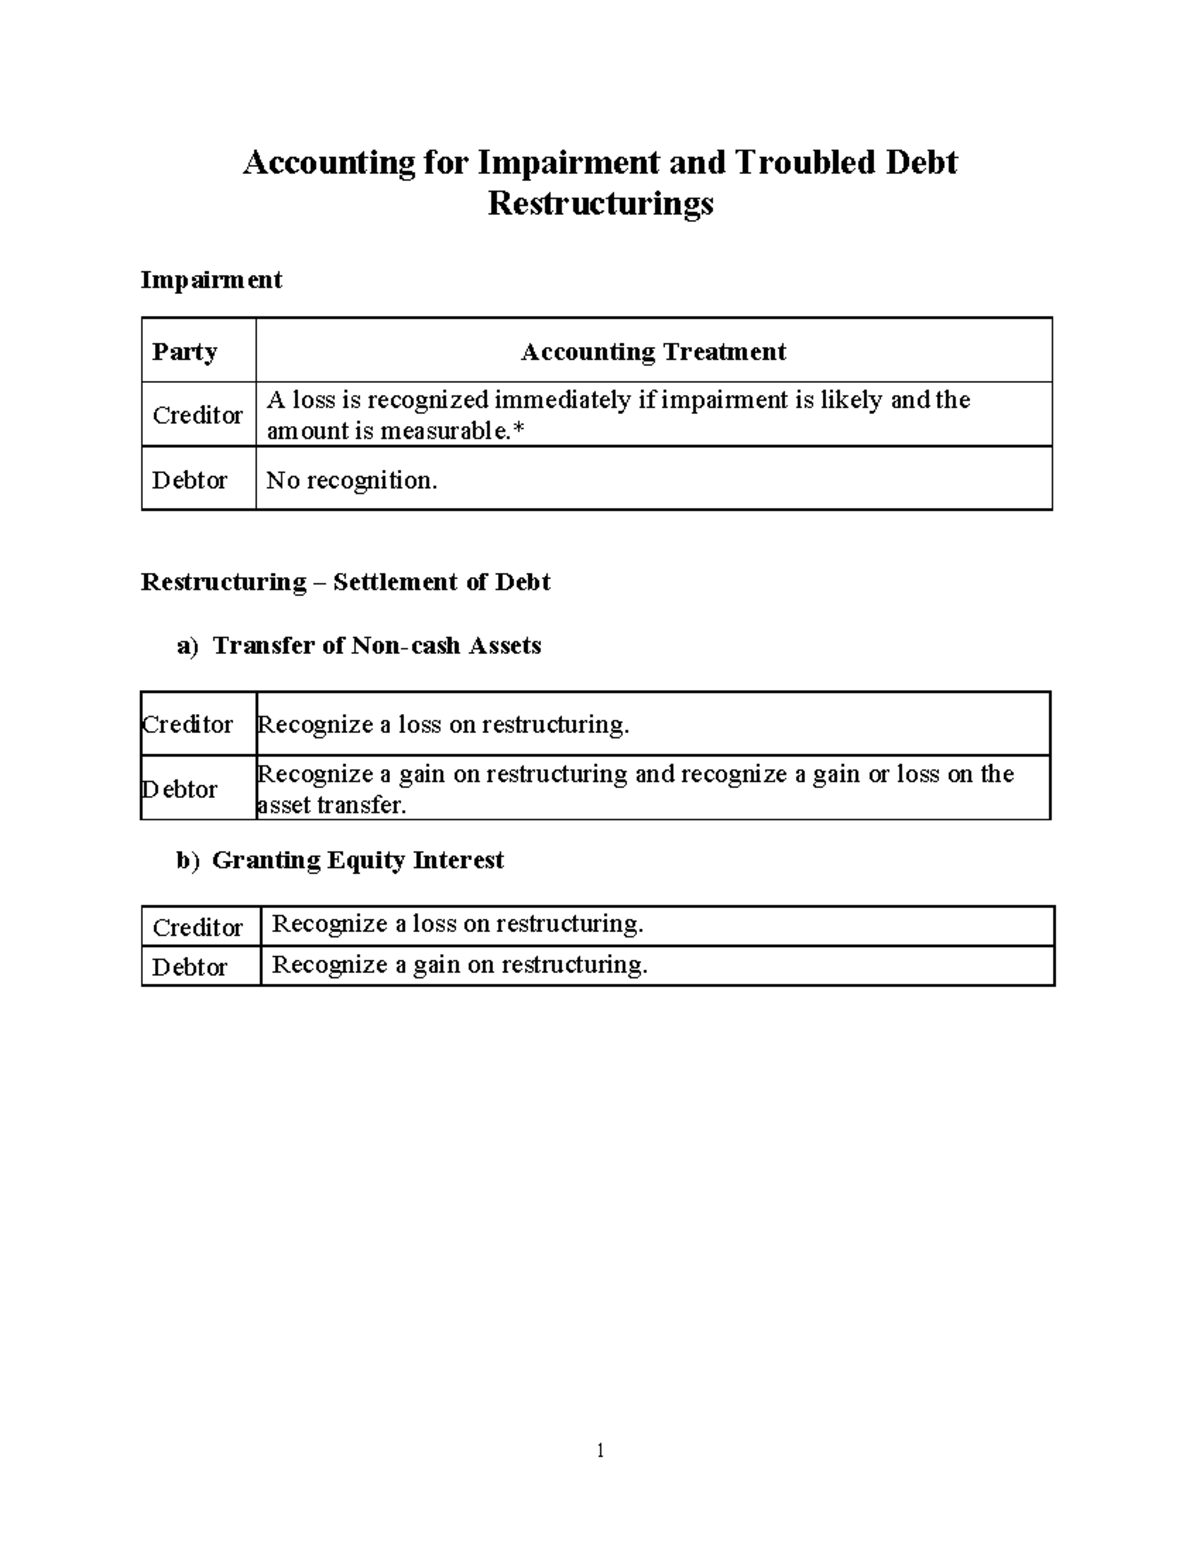
Troubled Debt Restructuring Accounting is one of those topics that looks straightforward on paper and turns into a mess once you actually have to model it. The core idea is simple enough: a lender modifies the terms of a loan because the borrower is already struggling financially, and you have to decide whether that modification constitutes a TDR under ASC 310-40 or if it's just a normal renegotiation. I've seen people trip over this repeatedly. The issue isn't the concept. It's the implementation details, especially when you're dealing with modified cash flows, discount rates, and the distinction between a troubled restructuring and a fresh start.
Troubled Debt Restructuring Accounting
Let me walk through how I actually approach this. When I get a case file, the first thing I do is check whether a concession was granted. That's the threshold question. If the creditor didn't give up anything material, you're not in TDR territory. You can stop there. But if they did, then you move into the measurement phase, which is where most people get it wrong. The measurement has two parts. First, you determine the new fair value of the restructured debt using the original lender's effective interest rate. Second, you compare that to the carrying amount on the books. Any difference becomes either a discount or a reserve, depending on which way the numbers go. Here's what trips people up. They use the current market rate instead of the original effective rate. That's incorrect under ASC 310-40. The standard says you stick with the rate that existed at the time of the original loan agreement. If you deviate from that, your impairment calculation will be off and audit won't touch it.
I ran into a specific edge case last year that illustrates this. We had a commercial real estate loan that was restructured with a below-market interest rate and a extended maturity. The borrower had clearly experienced financial difficulty. The easy answer would have been to just discount the new cash flows at the contract rate. But the contract rate itself was below market, which created a problem: were we measuring the concession or burying it inside the rate? The workaround I used was to layer the analysis. I calculated the present value of the restructured cash flows at the original effective rate to get the TDR component. Then I separately evaluated whether the below-market rate feature required additional recognition under ASC 835-30 on imputed interest. This two-layer approach meant the concession wasn't being double-counted or hidden. It took about three hours of model work that wouldn't have been necessary if the restructuring had used a market-rate coupon. Another thing nobody warns you about. The definition of financial difficulty is broader than most accountants expect. It's not just about bankruptcy or default. It includes situations where the borrower couldn't obtain funding from other sources at terms that would apply to a financially healthy entity. I've seen lenders classify restructurings as TDRs even when the borrower was technically current on payments because the lender knew the cash flow projections were unrealistic without a modification.
Get the Full Details

Common Pitfalls That Will Waste Your Time
One recurring mistake I see is ignoring the modification vs. extinguishment test. Not every restructuring is a continuing loan. If the new terms differ materially from the old ones — and the standard gives you a ten percent test as a safe harbor — you might need to treat this as an extinguishment and recognize a gain or loss immediately instead of amortizing a discount over the remaining term. The ten percent test compares the present value of the new cash flows to the old carrying amount using the original effective rate. If the difference exceeds ten percent, it's a substantive modification. This isn't a recommendation. It's the bright line the standard provides. Another practical issue. The disclosure requirements under ASC 310-40 are extensive and many firms barely scratch the surface. You need to disclose the number of modifications, the carrying amount of restructured loans, the economic circumstances that led to the restructuring, and the impairment recorded. Auditors will ask for this every quarter. If your working papers don't support it, you'll be scrambling at filing time.
There's also a timing problem that catches people off guard. Once a loan is classified as a TDR, it stays a TDR for reporting purposes even if the borrower later recovers. You don't get to reclassify it back to performing status just because the borrower caught up on payments. The standard is explicit about this. I've watched CFOs push back on this because it drags down their loan portfolio metrics, but the guidance doesn't provide an out. The biggest limitation of the current framework is that it's largely backward-looking. It focuses on the restructuring event itself and doesn't capture forward-looking indicators of credit deterioration well. If a loan is performing but the underlying collateral is underwater and the borrower's cash flows are degrading, you might still need to evaluate whether an allowance for credit losses is appropriate under CECL, but the TDR designation alone won't flag that risk. If you're working through a complex restructuring with multiple tranches, different classes of creditors, or embedded derivatives, the measurement gets complicated fast. In those situations, I usually recommend building a separate cash flow model rather than trying to stretch an existing loan servicing spreadsheet. The existing tools aren't designed for the kind of rate layering and concession isolation that TDR work requires. A clean model takes maybe an afternoon to set up and saves you several days of reconciliation work during audit.
What to Do When the Standard Doesn't Cover It
There are edge cases where ASC 310-40 doesn't give you clear direction. Debt issued by subsidiaries, for example, can create ambiguous situations when the parent guarantees the obligation but the guarantee itself is modified. I've seen inconsistent treatment across audit firms on whether the subsidiary-level restructuring should be evaluated separately or consolidated with the parent guarantee. Another gray area involves partial payments. If the borrower makes a partial payment as part of the restructuring and the creditor accepts it in full satisfaction, the accounting treatment depends on whether that partial payment is considered a genuine concession or something else. The standard doesn't spell this out clearly enough for borderline cases. The practical advice here is to document your reasoning thoroughly and get comfort from your auditor early. Don't wait until the field work starts. A quick email exchange with your audit partner can save you weeks of back-and-forth on a classification issue. Most firms will give you a preliminary view if you lay out the facts clearly.

One more thing. The interaction between TDR accounting and loan servicing rights is worth understanding. If you're a servicer holding the asset but not the owner, the impairment calculation falls on the holder, but you're the one doing the monthly cash flow work. Make sure your reporting systems can output the data in the format the investor needs. I've seen servicers get into trouble because their platforms weren't set up to track the original effective rate separately from the modified rate, which is the exact distinction the standard requires. Troubled Debt Restructuring Accounting isn't the most glamorous area of financial reporting, but it's consequential. The classifications affect your allowance calculations, your disclosure burden, and how investors view your loan quality. Getting it right the first time is significantly cheaper than fixing it after the auditors come back with questions.