Why Economics Can't Function Without Math
I spent about six years building econometric models for a regional development agency before moving into advisory work. The single most useful thing I learned is that mathematics in economics isn't about making things look rigorous. It's about forcing yourself to be unambiguous when you'd otherwise be talking past everyone in the room. I've watched policy briefs get dismissed because the author used the word "significant" to mean both "statistically significant" and "practically important" in the same paragraph. That ambiguity costs time and credibility. The Use Of Mathematics In Economics serves as a shared language, nothing more and nothing less. When you write out a production function or a utility maximization problem, you're creating something that can be tested, disputed, and refined. Verbal arguments in economics are inherently vulnerable to reinterpretation. Equations are not immune to disagreement, but at least everyone is arguing about the same thing.
The Practical Use Of Mathematics In Economics
Let me walk through how this actually works on the ground rather than giving you a textbook definition. Suppose you need to estimate the impact of a minimum wage increase on employment in a specific industry. You could write a persuasive essay about why workers deserve more pay. You could also build a difference-in-differences model using county-level data from two neighboring states with different wage floors, control for observable characteristics, and report your standard errors. Both approaches exist. They serve different purposes. The mathematical approach requires you to state your identifying assumption explicitly: parallel trends between treatment and control groups in the absence of the policy. If that assumption doesn't hold, your estimate is garbage, and you need to know that before anyone else points it out. I learned this the hard way early in my career on a project evaluating a job training program in the Midwest. My initial OLS specification showed a 12 percent earnings gain for participants. Then I added individual fixed effects to control for time-invariant ability, and the estimate dropped to 3.4 percent. The program was still effective, but the magnitude changed dramatically once I stopped treating participant selection as random noise.
Core Mathematical Tools You Actually Need
You don't need a graduate-level math degree to do applied economics. Here's what separates people who can read a paper from people who can produce one. Optimization is the foundational tool. Almost every economic problem is an optimization problem under constraints. Consumers maximize utility subject to a budget constraint. Firms maximize profit subject to a production technology. Governments maximize welfare subject to revenue requirements. The Lagrangian method handles the constraint calculus, and understanding first-order conditions lets you read most theoretical papers without getting lost in the notation. I see a lot of practitioners skip this and go straight to software, which works until the model breaks and you have no idea why. Difference equations and dynamic programming matter whenever you're dealing with decisions over time. If you've ever tried to model savings behavior, investment timing, or resource extraction, you've run into the Bellman equation. It sounds intimidating but the logic is straightforward: the value of being in a state today equals the immediate payoff plus the discounted value of tomorrow's optimal decision. I worked on a natural resource depletion model where the wrong discount factor choice shifted the optimal extraction schedule by nearly a decade. The math forced us to confront an assumption we'd been glossing over for months.
Get the Full Details

Probability theory and statistics are non-negotiable for empirical work. Maximum likelihood estimation, instrumental variables, Bayesian updating, bootstrapping standard errors. These are the tools you use when the world doesn't hand you clean experimental data, which is almost always. The key insight that beginners miss is that statistical significance does not equal economic significance. A coefficient can be significant at the one percent level with a sample of fifty thousand observations and still represent an effect so small it wouldn't move a policy discussion. Always check the magnitude against the scale of the variables involved.
Where The Math Breaks Down
I want to be blunt about the limitations because I've seen too many people treat economic models as truth generators rather than approximation machines. General equilibrium models assume perfect information, rational expectations, and complete markets. Real economies have none of those things in the required degree. The models still produce useful insights about the direction of effects, but the quantitative predictions are often wildly off. During the 2008 financial crisis, several major DSGE models predicted that the banking sector shock would translate into a mild recession of about one percent GDP loss. The actual contraction was closer to four percent in the United States alone. Another failure mode is overfitting. With enough variables and enough flexibility in your model, you can make the data say almost anything. I once reviewed a working paper that used a structural vector autoregression with twelve lags and eight variables to identify monetary policy effects. The identification scheme was internally consistent but completely unrecoverable from the data. The authors called it a "necessary simplifying assumption." It was an unnecessary one. I recommended they collapse the system to three variables with four lags and test the robustness, which they did. The results didn't change direction, but the confidence intervals widened substantially, and that mattered for the policy recommendation. Behavioral economics has also exposed serious gaps in the standard mathematical framework. Expected utility theory assumes consistent preferences, but people violate transitivity, show framing effects, and discount the future hyperbolically rather than exponentially. You can patch these problems with adjusted models, but each patch adds complexity and reduces the predictive power that made the original framework useful. There's no clean solution here. You trade off internal consistency against descriptive accuracy, and the right balance depends entirely on what question you're trying to answer.
A Quick Reference For Getting Started
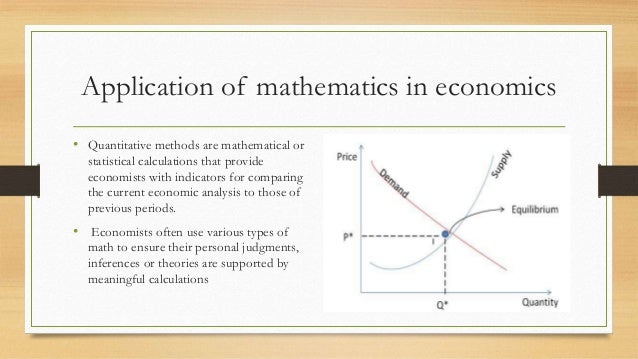
If you want to move from reading economics papers to doing the math yourself, start with linear algebra and calculus at the undergraduate level. Simon and Blume's Mathematics for Economists covers the essentials without unnecessary abstraction. For econometrics, Wooldridge's introductory text is dense but reliable. The free version available through many university repositories will get you through the core material on regression, inference, and panel data methods. Software-wise, Stata remains the standard in academia and government research because of its reproducibility and extensive documentation. R is free and increasingly dominant in methodological work. Python is gaining ground for computational economics and machine learning applications. I recommend learning one well rather than three superficially. A single tool used consistently will produce better results than three tools used occasionally. Build a simple model from scratch before running any real data. A supply and demand system with estimated parameters, solved for equilibrium, and simulated under a price ceiling gives you more practical understanding than a dozen sophisticated regression runs on data you don't fully understand. The math becomes a habit rather than a collection of formulas you apply mechanically.