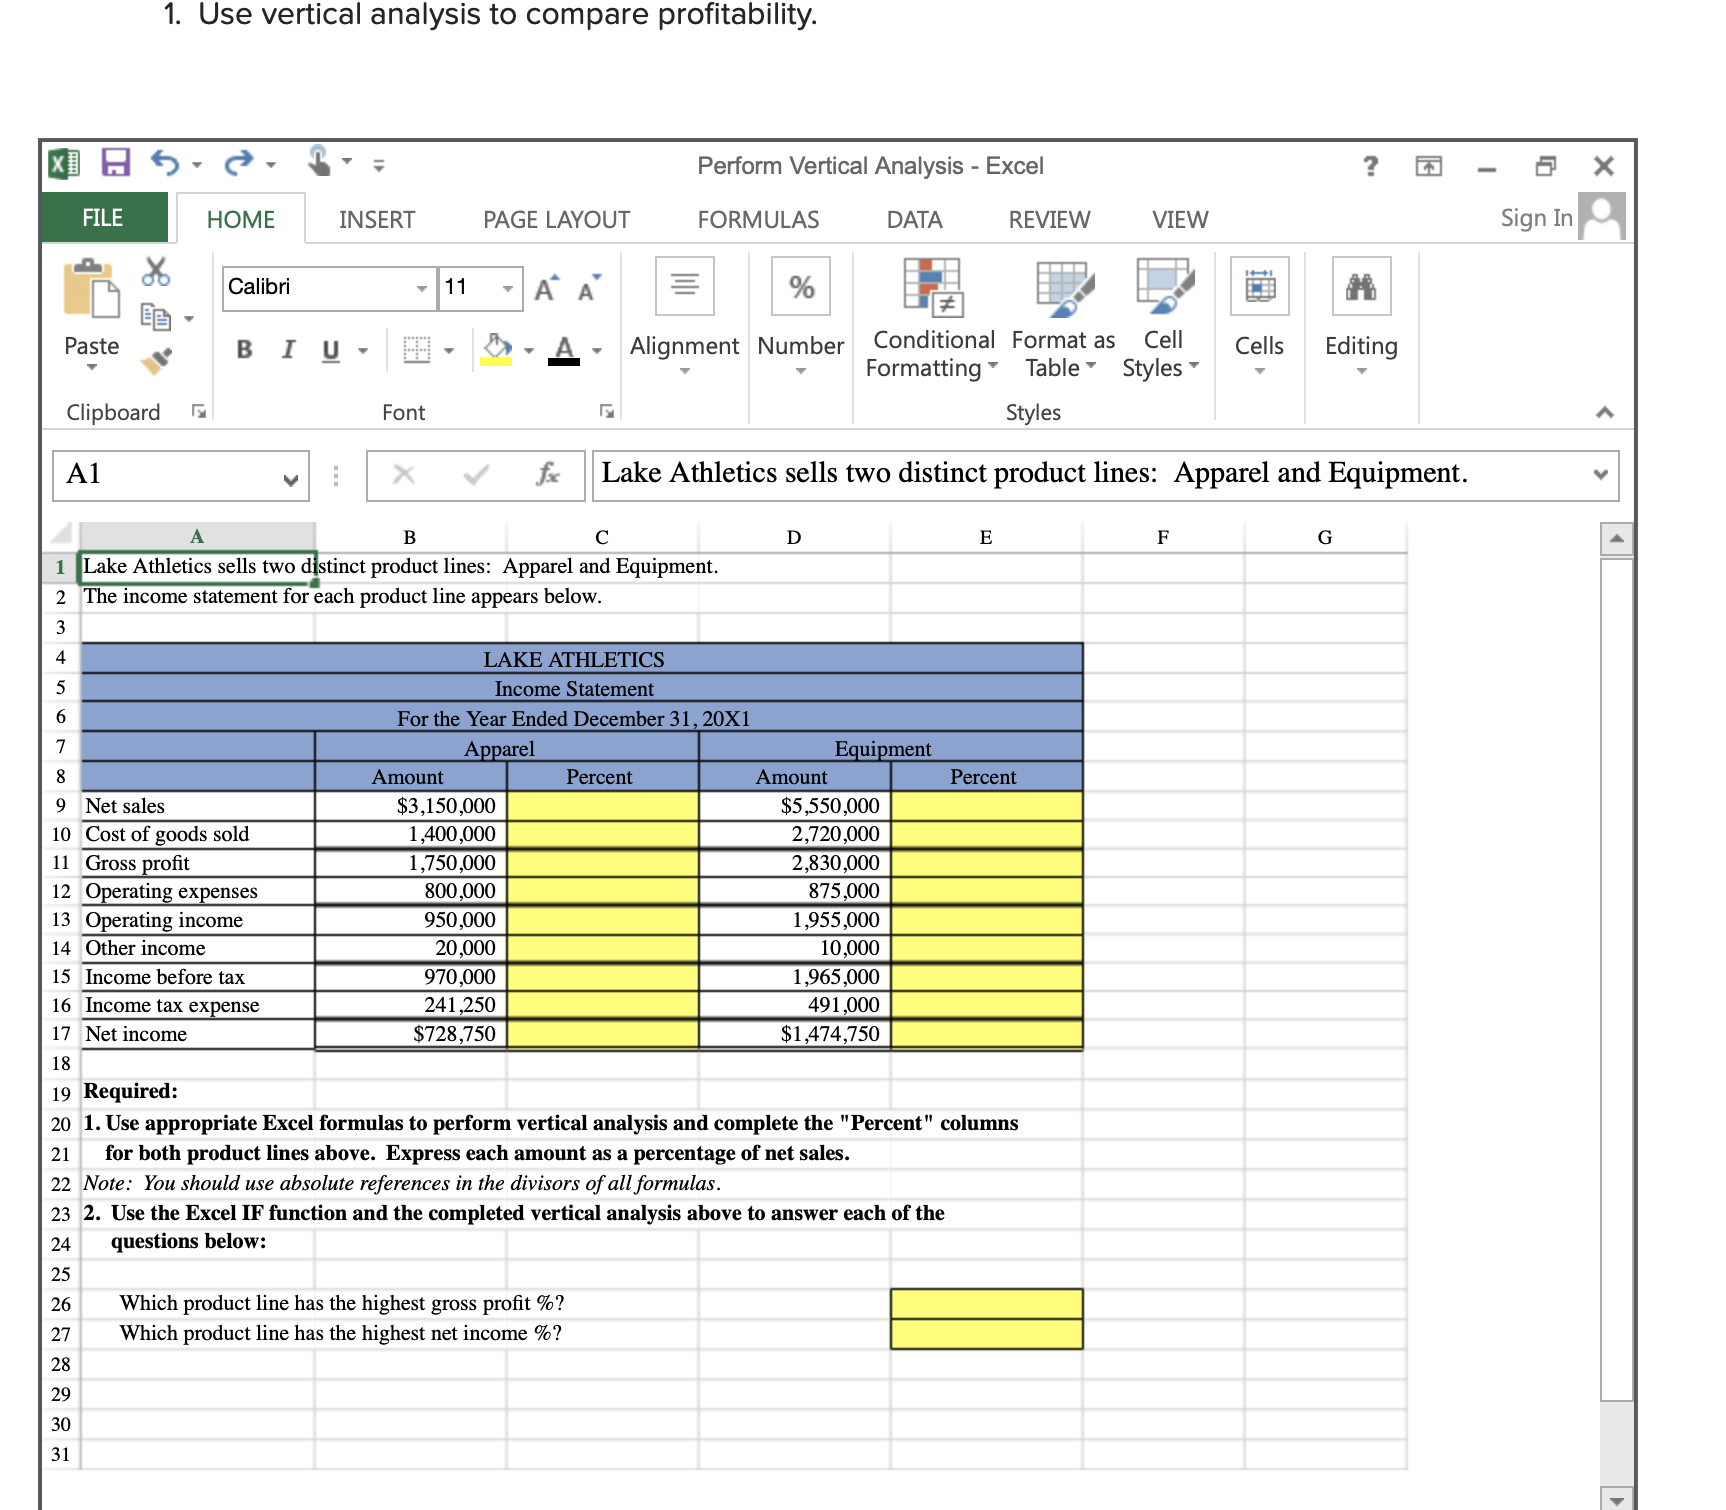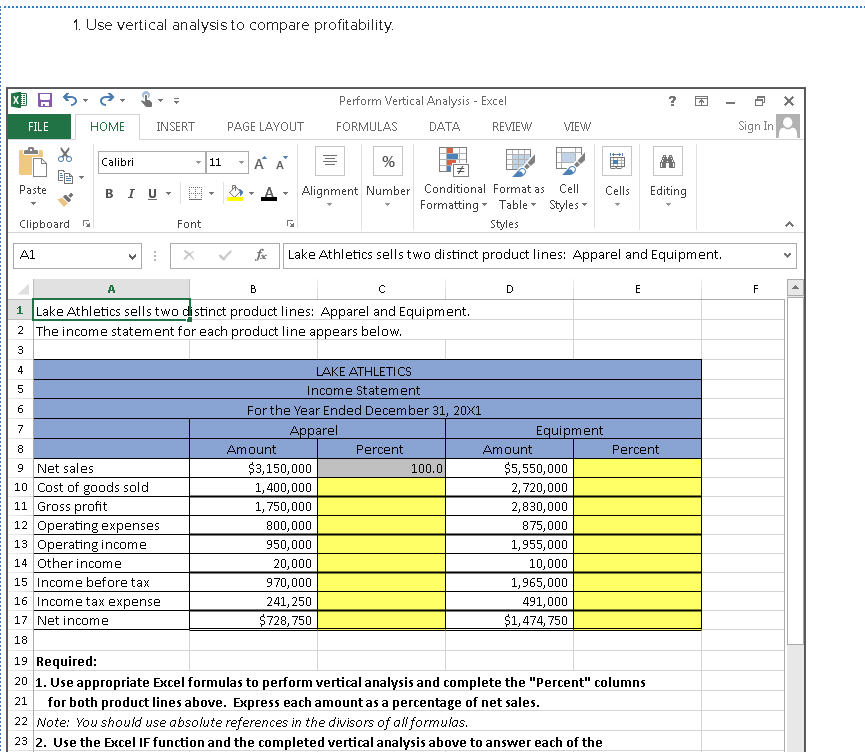
Vertical analysis isn't some advanced technique
It's just a way of looking at financial statements where every line item becomes a percentage of a base number. For the income statement, that base is revenue. For the balance sheet, it's total assets. You probably already do something like this without realizing it when you look at a P&L and wonder why gross margin matters less than operating margin. The problem with comparing profitability across companies or periods is that absolute dollar amounts lie to you. A company with $50 million in revenue and $5 million in net income looks worse on paper than one with $200 million and $25 million. But in reality the smaller company has a 10% net margin while the bigger one is at 12.5%. Vertical analysis strips away that distraction by normalizing everything.
How to Use Vertical Analysis To Compare Profitability
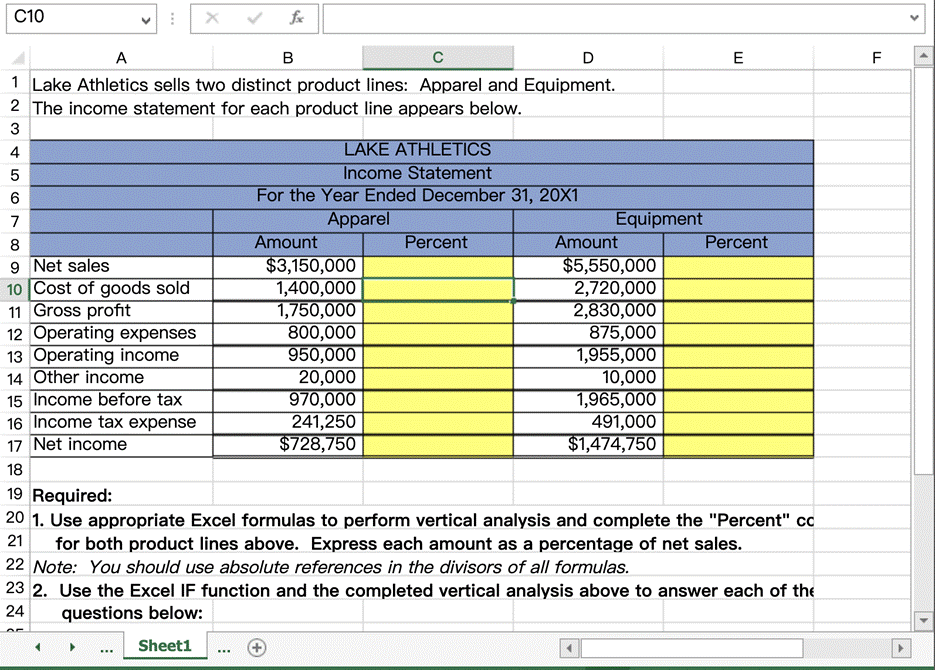
Here's what the actual workflow looks like. Take two income statements from different years or from two competing companies. Pick revenue as your base and convert every single expense line into a percentage. Cost of goods sold divided by revenue. Operating expenses divided by revenue. Interest expense divided by revenue. Even income tax becomes a percentage of revenue instead of sitting there as a raw dollar figure. Once everything is expressed as a share of revenue, you can stack those percentages side by side and see structural differences that dollar comparisons hide. Maybe Company A has a slightly lower gross margin but also dramatically lower selling expenses. Maybe Company B's R&D while Company A barely spends anything on research. The percentages make those tradeoffs visible. I learned this the hard way working with a manufacturing client who was convinced their cost of goods sold was out of control. Revenue had grown 40% year over year, which should have been a good thing, but net income had flatlined. When I ran the vertical analysis, I found that COGS had actually declined as a percentage of revenue from 68% to 62%, which meant they were gaining efficiency. The problem wasn't COGS at all. It was that freight costs, classified separately as operating expenses, had exploded in dollar terms because they'd shifted from regional to national distribution without anyone recalibrating the cost structure. The vertical view made the real issue jump off the page immediately.
The mechanics are straightforward but easy to misuse
Most people calculate vertical analysis correctly but then draw the wrong conclusions from it. A 2% drop in operating expenses as a percentage of revenue sounds great until you realize it came from deferring maintenance and cutting quality control staff. The percentage improved but so did the likelihood of a product recall six months later. Numbers don't tell you why something changed, only that it changed. Another thing nobody warns you about is the compounding effect of vertical analysis across multiple years. When you compare 2022, 2023, and 2024 side by side, small percentage movements can look dramatic on paper. A rise from 3.1% to 3.8% in administrative expenses sounds alarming, but in absolute terms it might only be $340,000 on $9 million in revenue. Context matters more than the raw percentage shift. You also need to watch out for companies with seasonal revenue patterns. Retailers and agricultural businesses especially distort vertical analysis when you compare quarterly results without accounting for the fact that fixed costs get spread over wildly different revenue bases depending on the quarter. Q4 for a holiday retailer will make every expense look tiny as a percentage of revenue, which can be misleading if you're not expecting it.
Get the Full Details
What vertical analysis can't do for you
It doesn't account for different accounting methods. Two companies might report identical gross margins using vertical analysis while one capitalizes certain costs and the other expenses them. The percentages look the same but the cash flow profiles are completely different. If you're doing this analysis for investment purposes, you need to pull the cash flow statement too and cross-reference. It also breaks down when revenue is negative or near zero. A distressed company with declining sales will show exploding percentages for fixed costs because the denominator is shrinking. That's technically correct but not especially useful for decision making. In those situations horizontal analysis of absolute dollar changes is more informative, or you switch to comparing against industry benchmarks rather than the company's own prior periods. The biggest practical limitation is that vertical analysis treats all revenue the same regardless of quality. Recurring subscription revenue and one-time consulting fees both appear as 100% of revenue in the base calculation. A company can have excellent margin percentages but still be vulnerable to customer concentration risk that vertical analysis completely obscures. You have to look beyond the percentages to understand what's actually driving them.
A practical shortcut most analysts skip
Instead of converting every line item to a percentage, focus on the top five expense categories plus net income. That gives you the signal without the noise. Most profitability differences between companies come from gross margin, selling expenses, and either R&D or general administrative costs. The obscure line items rarely move the needle and just add visual clutter to your comparison tables. When I put this together for a private equity due diligence project, I created a single spreadsheet with five columns: Company A 2023, Company A 2024, Company B 2023, Company B 2024, and Industry Average. Each row was a percentage of revenue. The whole thing took about 45 minutes to build and immediately revealed that Company A's selling expense ratio had widened by 3.2 percentage points year over year while Company B had tightened theirs by 1.1 points. That gap told us more about competitive positioning than any margin discussion could have. The template approach works because you're not trying to be comprehensive. You're trying to be fast and directional. Vertical analysis is best used as a scanning tool that tells you where to dig deeper, not as a standalone proof of anything. Run the percentages, flag the anomalies, then go read the notes to the financial statements to understand what actually happened.