The Unsexy Truth About Reading Balance Sheets
I spent about eight years trying to find cheap stocks the old way, and most of that time was wasted on things that looked cheap but weren't. Ben Graham's approach was straightforward on paper. You bought businesses trading below their net current asset value or at a reasonable discount to tangible book value. The math was clean. The execution was not. The problem with following Graham strictly is that the universe of qualifying stocks shrinks to nearly nothing during normal market conditions. In 2021 and 2022 I ran screen after screen looking for net-net candidates and found exactly three companies across the entire S&P 500 that met the strict criteria. Three. Out of five hundred. You cannot build a portfolio out of three stocks without taking on concentration risk that Graham himself would have rejected.
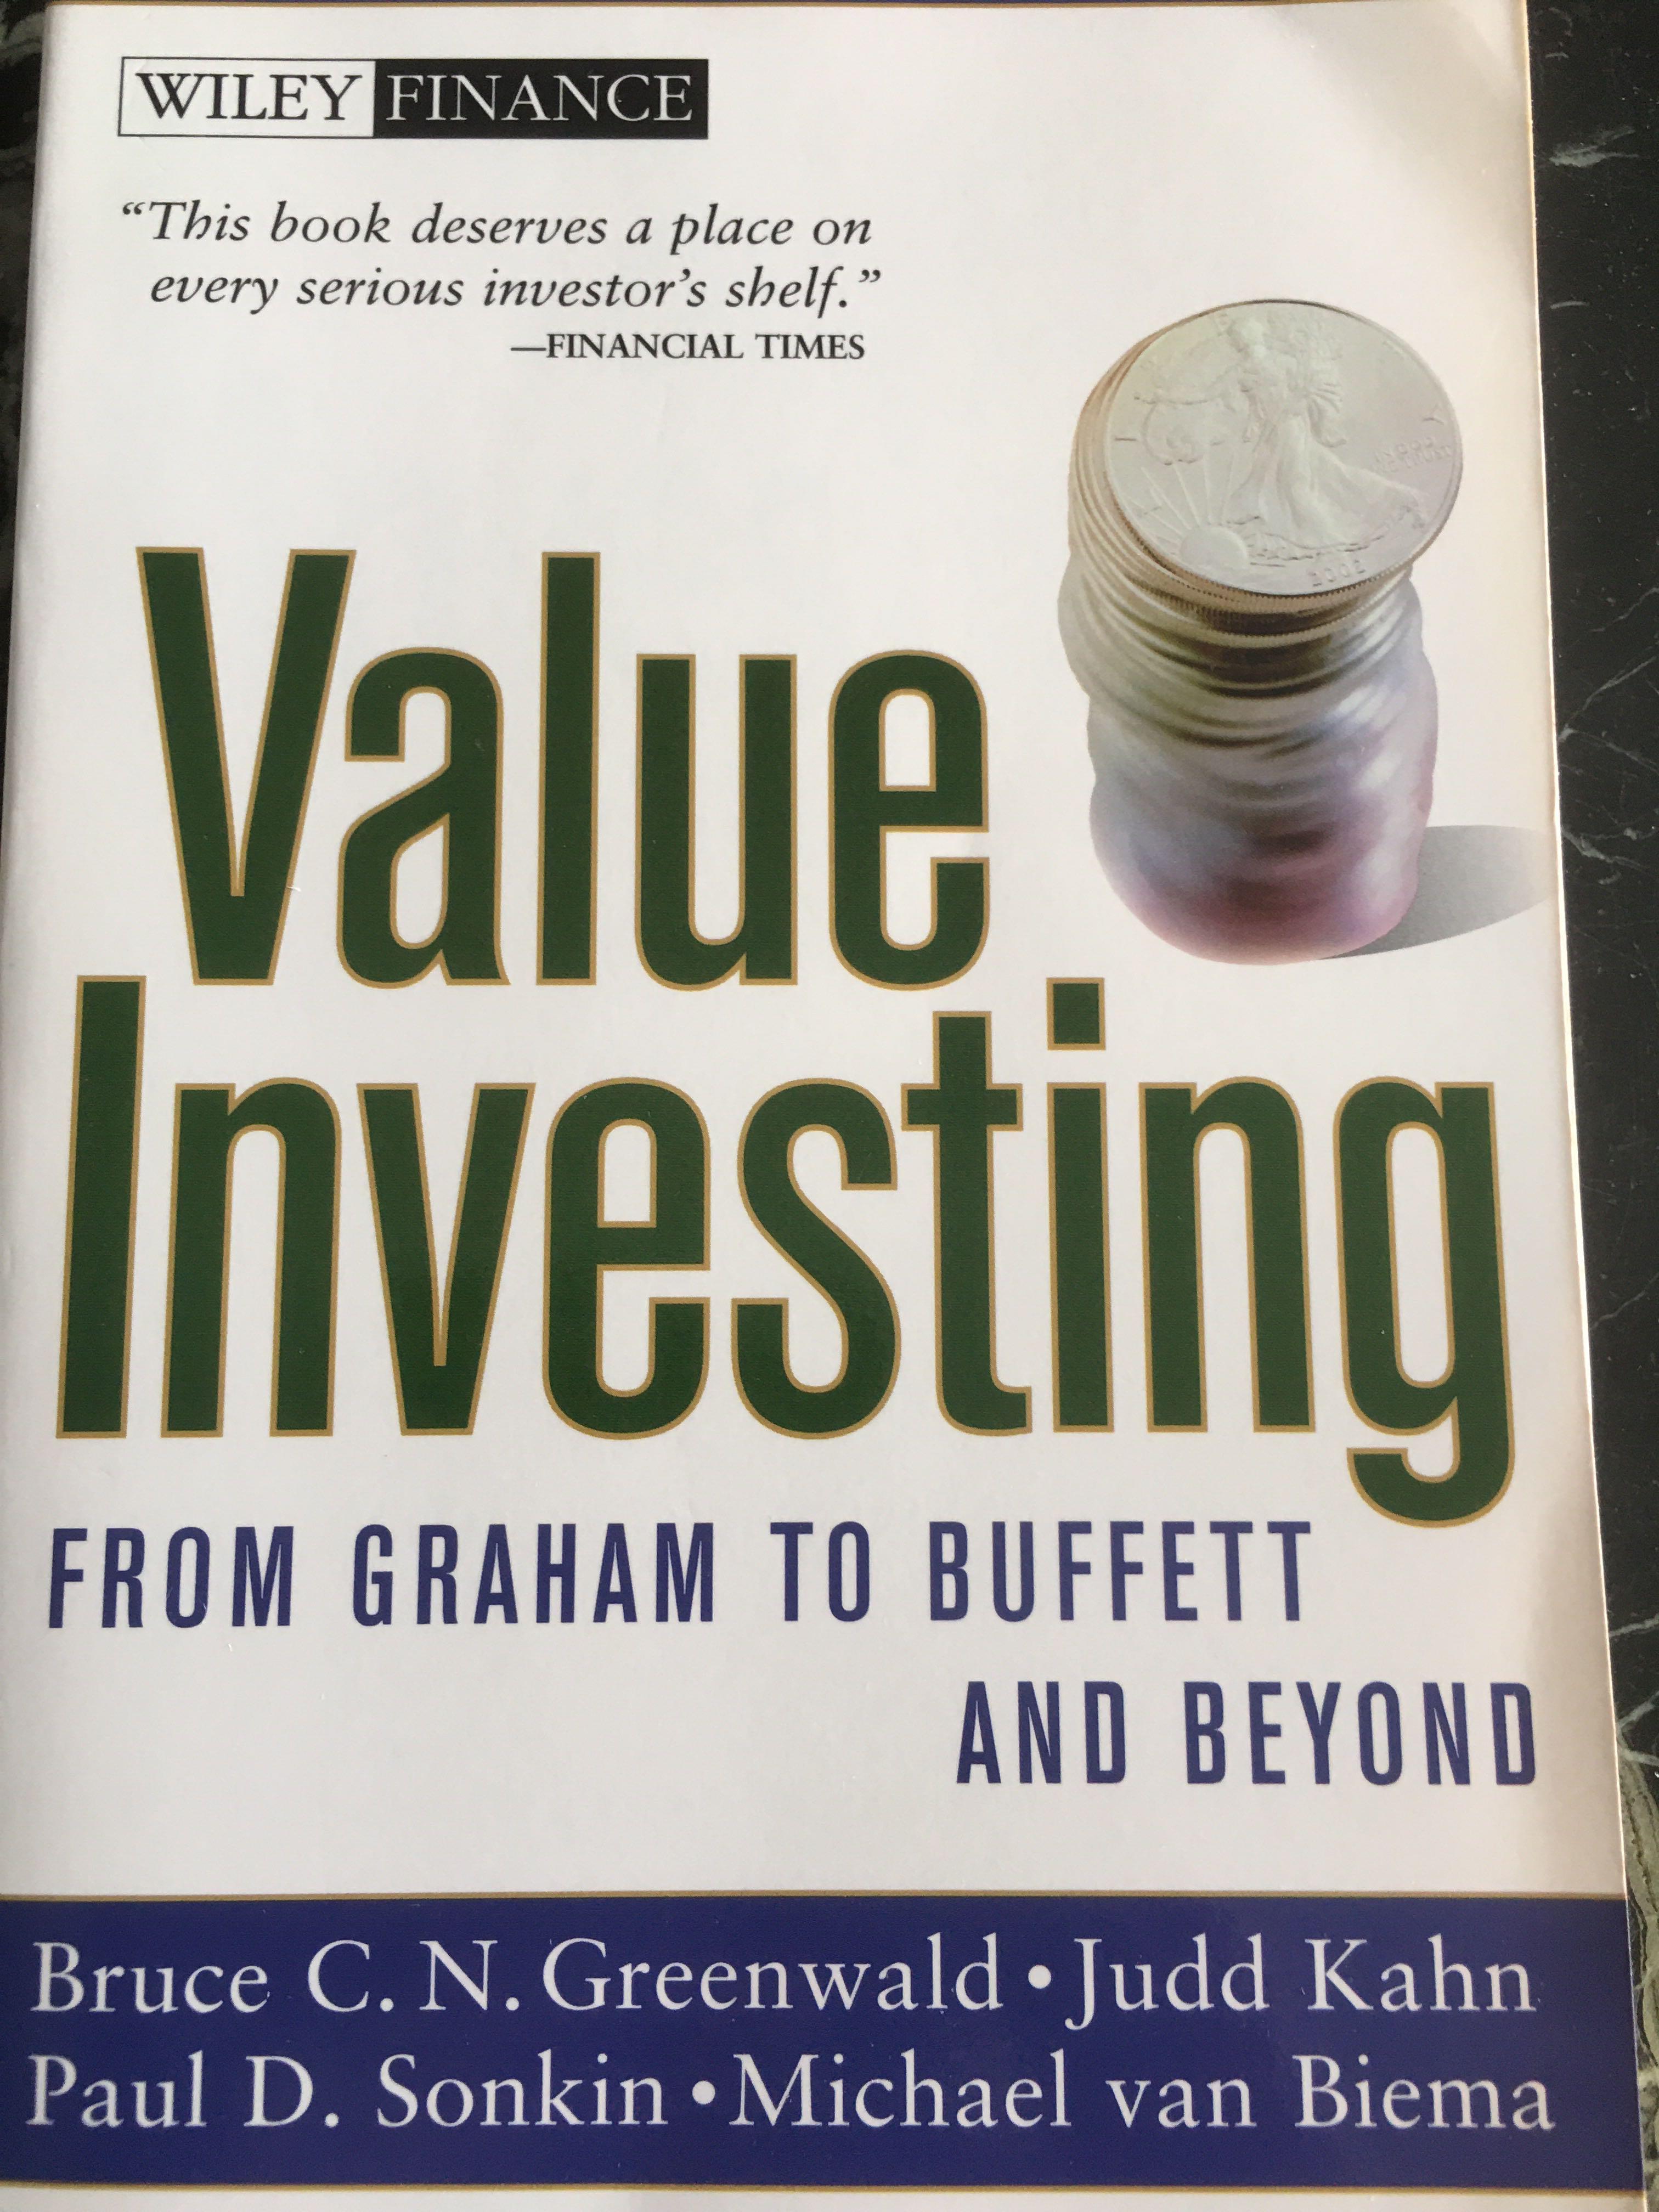
Value Investing From Graham To Buffett And Beyond
The shift happened because Buffett realized that buying a great business at a fair price often outperformed buying a mediocre business at a bargain price over any meaningful timeframe. This is the part most people skip when they read about Graham. They focus on the quantitative screening and miss the qualitative evolution that came next. Buffett started applying Moore's law logic to competitive advantages. He called it the moat, but the concept is simply this: some businesses can reinvest capital at high rates of return for decades without competitive erosion, while others cannot. The valuation methodology changes entirely depending on which category you are in. Here is how I actually work through a potential investment now. I start with the capital allocation track record of management, not the income statement. I pull ten years of annual reports and check whether retained earnings have translated into per-share intrinsic value growth. If management has destroyed capital through poor acquisitions or blind expansion, I walk away regardless of how cheap the stock appears. I learned this the hard way in 2018 when I bought a seemingly undervalued industrial company at 0.8 times book value because the balance sheet looked attractive. The CEO was quietly loading the balance sheet with goodwill from acquisitions that were slowly impairing. The stock went to 0.4 times book within eighteen months. I lost thirty-two percent before I sold. The quantitative screen had not caught it because the damage was happening through acquisition accounting, not operational deterioration. Now I check the acquisition history first. I look at how much of the company's market cap is attributable to goodwill and whether management has a pattern of overpaying. If the goodwill-to-equity ratio exceeds forty percent and the company has done more than two acquisitions in five years, I treat the book value as unreliable and switch to free cash flow yield as my primary metric instead.
The modern framework really comes down to three screens performed in sequence. First, I look for durable competitive advantages that show up as consistently high returns on invested capital above twelve percent over ten years. Second, I assess whether the business can sustain those returns without requiring massive incremental capital. This is where the moat analysis matters. A company that needs constant capital expenditure just to maintain its position is not a great business even if it looks cheap. Third, I apply a margin of safety to whatever intrinsic value I derive, and I never buy without it. Intrinsic value estimation is where most people get careless. I use a two-stage discounted cash flow model with conservative assumptions. Revenue growth is projected at the lower end of management guidance or historical average, whichever is lower. I assume operating margins revert toward the industry median over the projection period. The discount rate I use is ten percent, which is higher than the standard WACC approach because I am accounting for the uncertainty in long-term projections. Terminal value is calculated using a perpetuity growth rate of two and a half percent. That sounds low but it is deliberately conservative and accounts for the fact that very few businesses maintain supernormal growth rates indefinitely. One counter-intuitive thing about this approach that people miss: the quality filter is actually more important than the discount. A twenty percent discount on a deteriorating business is a trap. A ten percent discount on a compounding business with pricing power is usually a good entry point. I track this empirically. My holding period for quality businesses with fair prices averages four to six years. My holding period for deep value traps averages eleven months before I cut them loose.
Get the Full Details
There are scenarios where this methodology fails completely. Business model disruption is the main one. I have seen excellent value traps in retail, media, and legacy telecommunications where the fundamentals looked solid on paper but the underlying economics were being eroded by structural changes that annual reports do not capture. The workaround is to assess whether the company's product or service is still growing in total addressable market terms. If the category itself is contracting, no amount of cheap valuation helps. I also avoid highly regulated industries where pricing power is artificially constrained regardless of competitive position. For current opportunities, I run my screen monthly. The latest pass identified a regional insurance company trading at nine times forward earnings with a thirty-eight percent return on equity and zero debt. The intrinsic value estimate came to roughly 1.6 times the current price using the methodology described. Management has been buyback-active for four consecutive years, and the book value per share has grown at eleven percent annually over the past decade. This is exactly the type of setup the Graham-to-Buffett framework is designed to catch. The practical takeaway is that value investing is not about finding cheap stocks. It is about identifying businesses where the gap between price and intrinsic value is wide enough to absorb error, and where the underlying economics support continued capital appreciation over a multi-year horizon. The tools changed slightly between Graham and Buffett. The discipline did not.