Getting a Vehicle Sales Contract Right
Most people think a bill of sale is enough. It isn't. A Vehicle Sales Contract does more than document money changing hands. It establishes who bears the risk when the title hasn't transferred yet, who's liable if the car breaks down three days after purchase, and what happens if the buyer defaults on an installment plan. The difference between a lazy template and a contract that actually holds up in court usually comes down to three things: lien disclosure, payment mechanics, and dispute resolution. Skip any one of those and you've got a document that looks professional but does almost nothing.What You Need in a Vehicle Sales Contract
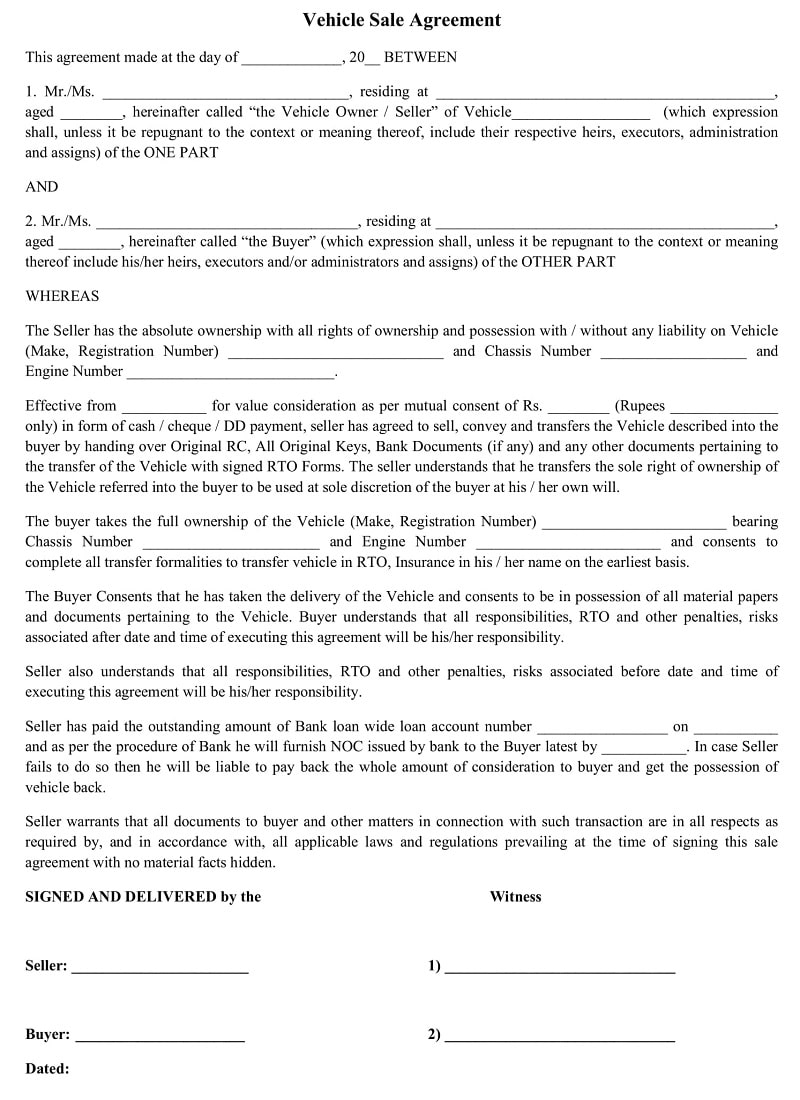
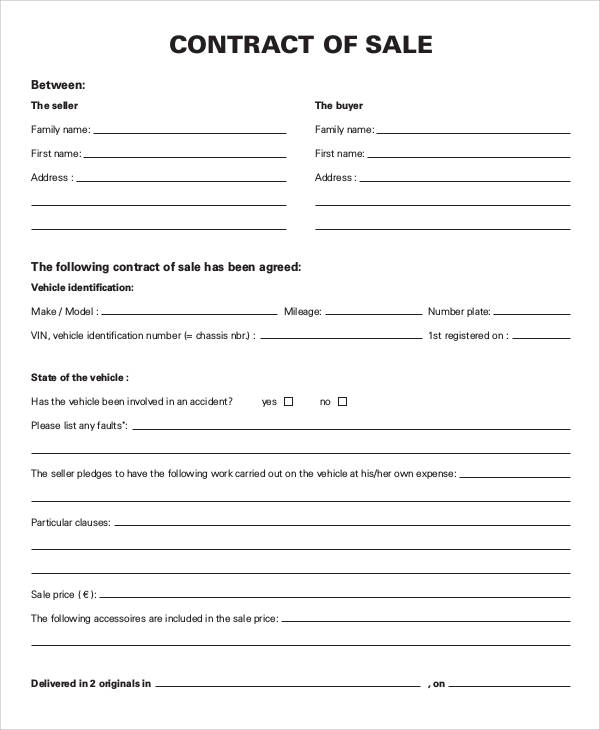
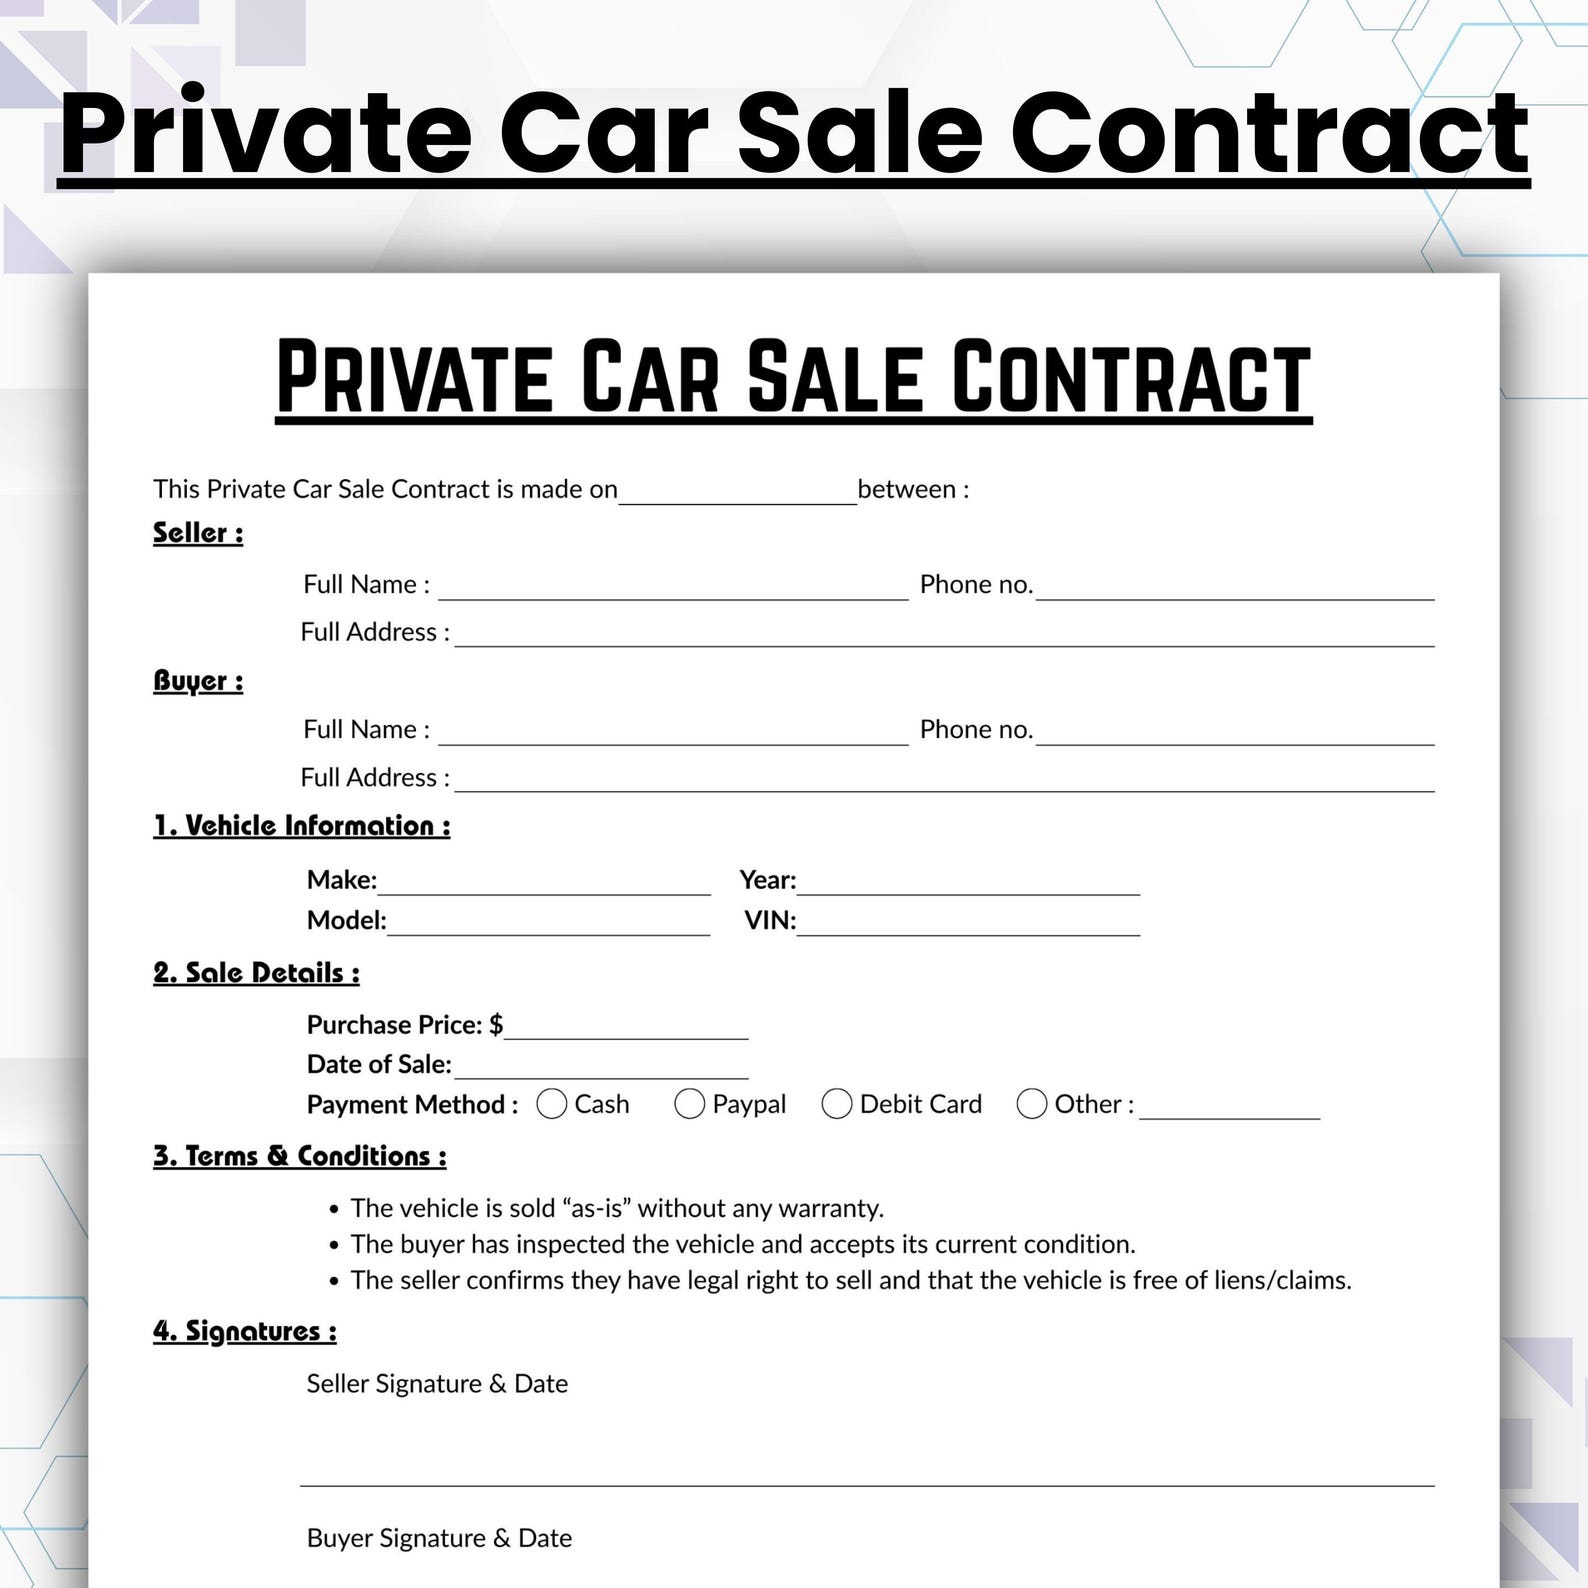
Start with the vehicle identification. Year, make, model, VIN, odometer reading at the time of signing, and the condition designation—new, used, or salvage. The odometer section matters because federal law requires a statement under penalty of perjury. If the odometer is actual, roll back, or not actual, you have to pick one. Selecting the wrong box doesn't just look careless; it creates a separate legal exposure that has nothing to do with the sale itself. Next, lay out the purchase price and payment terms in full detail. Cash price, down payment, any financing arrangement, the total amount owed, and the schedule for installment payments if applicable. Be specific about late fees, grace periods, and what triggers acceleration—meaning the entire remaining balance becomes due immediately. Vague language here is where contracts fall apart. "Buyer agrees to pay within a reasonable time" is not enforceable in most jurisdictions. Write the exact date, the exact dollar amount, and the exact consequence for missing a payment. The seller must disclose any known liens, encumbrances, or outstanding loans against the vehicle. If the car is being sold subject to an existing loan, state the lender's name, the payoff amount, and who is responsible for clearing the lien before the title can transfer. I handled a case last year where a seller checked the box saying "no liens" on the form, but there was a $4,200 balance with a credit union that hadn't been released yet. The buyer's title company flagged it during the transfer process, and the seller had to scramble to get a payoff letter within 72 hours or the deal would have collapsed entirely. The workaround was straightforward—I pulled the lien information directly from the state DMV's online database before anything was signed, which confirmed the exact lender and balance. That check takes about five minutes and eliminates the biggest source of post-sale disputes.
Include a warranty section, even if the sale is strictly "as-is." Write out exactly what the as-is clause means in your jurisdiction. Some states require specific bolded or capitalized language for as-is disclosures to be valid. California, for example, has a particular phrasing requirement. If you use a generic template from the internet and it doesn't match your state's statutory language, the warranty disclaimer gets thrown out and the seller suddenly has implied warranty liability on a used car they sold for cash. Transfer of ownership details come next. Specify the date of transfer, whether the seller provides the title at closing or within a set number of days, and who handles the registration and title fees. If you're dealing with a financed vehicle where the lender holds the title, note that the seller will forward the payoff documents to the buyer within a stated timeframe and that the buyer is responsible for ensuring the lien release is recorded. Add a dispute resolution clause. Most private vehicle sales don't go to court, but when they do, the difference between litigation and mediation or arbitration can mean the difference between spending three thousand dollars in legal fees and resolving the issue in a single session. Specify the governing law, the venue for any legal action, and whether mediation is a required precursor to filing a lawsuit.
Finally, both parties should sign and date the document. Notarization isn't always required but it adds a layer of verification that helps if anyone later claims the signature was forged or the seller didn't actually agree to the terms. A few states require notarized bills of sale for title transfer anyway, so checking your local DMV requirements before you finalize anything saves a follow-up trip.
Get the Full Details
Common Mistakes That Invalidate These Contracts
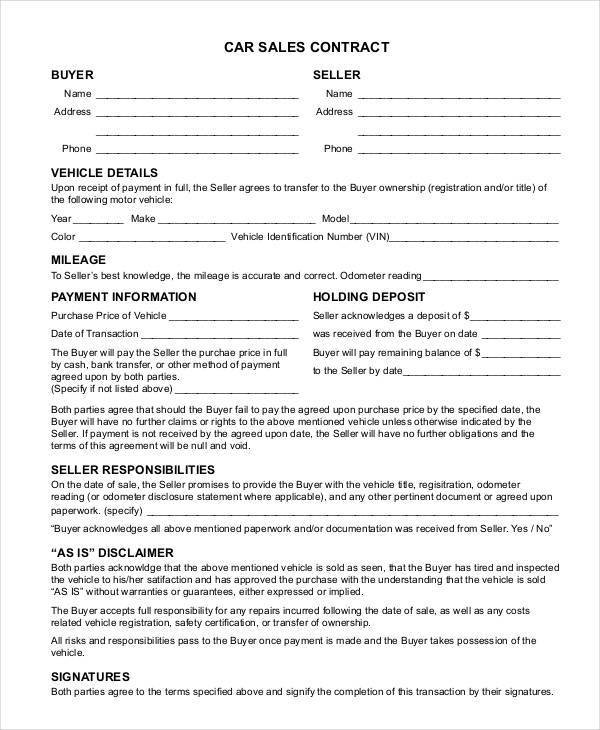
The most common mistake I see is relying on a downloaded template without verifying it matches current state law. These forms get updated periodically. A template from 2019 might reference a statute that was repealed in 2021. The contract looks fine on the surface but the legal basis it rests on no longer exists. Before you use any template, confirm the citation to your state's vehicle code is current. It takes ten minutes to verify on your state's legislature website. Another problem is the vague delivery of the title. Writing "seller will provide title" isn't sufficient. If the seller never provides it, you have no enforceable timeline. State clearly that the title must be delivered within a specific number of business days, and define what happens if it isn't—whether the buyer can rescind, claim damages, or pursue other remedies. I had a situation where a buyer purchased a vehicle, the seller took the check, said the title was "in the mail," and never followed through. The contract said the title would be delivered within ten days but contained no consequence for missing that deadline. The buyer ended up having to file a bond title through the state instead, which cost over two hundred dollars and took three months. A single sentence about the remedy for nondelivery would have prevented all of it. Odometer disclosure is another area where people cut corners. Failing to initial each section separately, skipping the "not actual mileage" option when it applies, or leaving the disclosure blank entirely are all problems. The federal odometer disclosure statement applies to vehicles under 16,000 pounds that are under 10 years old. If your contract doesn't include a compliant federal disclosure and your state doesn't have its own equivalent built into the form, you're exposed to statutory damages that can reach five thousand dollars per violation regardless of whether anyone was actually misled.
Where This Approach Breaks Down
A written Vehicle Sales Contract works well for private-party sales and small dealer transactions. It does not work well when you're dealing with a high-volume dealer operation that has its own standardized forms required by state law. Some states mandate specific dealer forms that override any private contract. In those cases, using a custom-drafted contract alongside the dealer form can create conflicts between the two documents. The dealer form controls because it satisfies the statutory requirement, and the extra contract just adds confusion rather than clarity. The other limitation is cross-state sales. If the seller lives in one state and the buyer in another, determining which state's disclosure requirements apply becomes complicated. The general rule is that the seller's state requirements govern the disclosure, but the buyer's state may impose additional obligations on the transferring party. I've seen two contracts reviewed for the same transaction—one under Florida law and one under Georgia law—with different warranty disclaimer requirements and different odometer wording. When the clauses conflicted, the buyer's state requirements effectively imposed the stricter standard on the transaction. If you're dealing with a sale across state lines, run the contract by someone licensed in both states rather than assuming one set of rules covers everything. Electronic signatures are accepted in all fifty states under the ESIGN Act, but some DMVs still require a wet-ink signature on the title application itself. Having a fully executed electronic contract doesn't guarantee you can complete the title transfer without printing and signing a physical copy. Check with your local DMV before assuming an e-signature approach will work end-to-end.
If you need a starting point, most state DMV websites offer a free bill of sale form that meets minimum requirements. It's not as thorough as a custom Vehicle Sales Contract, but it's legally compliant and free. For transactions over five thousand dollars or any sale involving an installment payment plan, I'd recommend spending the money on a document drafted or reviewed by someone familiar with your state's motor vehicle laws rather than relying on a generic template. The cost is usually between one hundred and three hundred dollars and it prevents the kind of problems I described above from happening in the first place.