The mechanics of discounting future money back to today
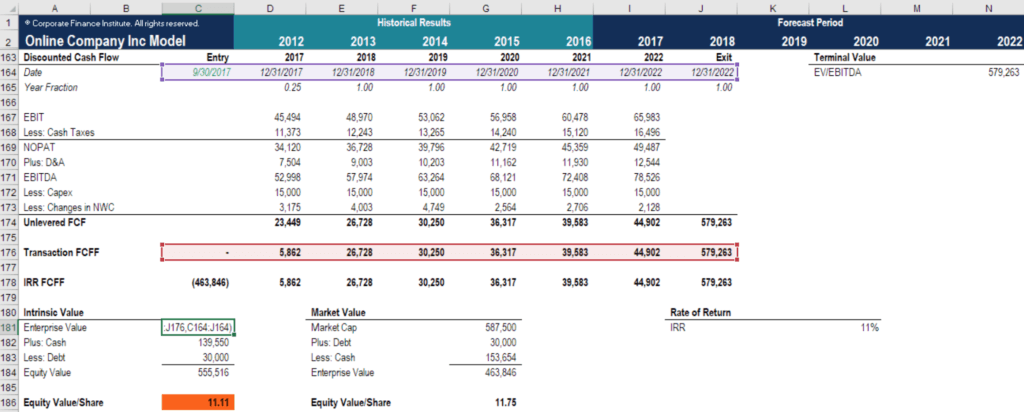
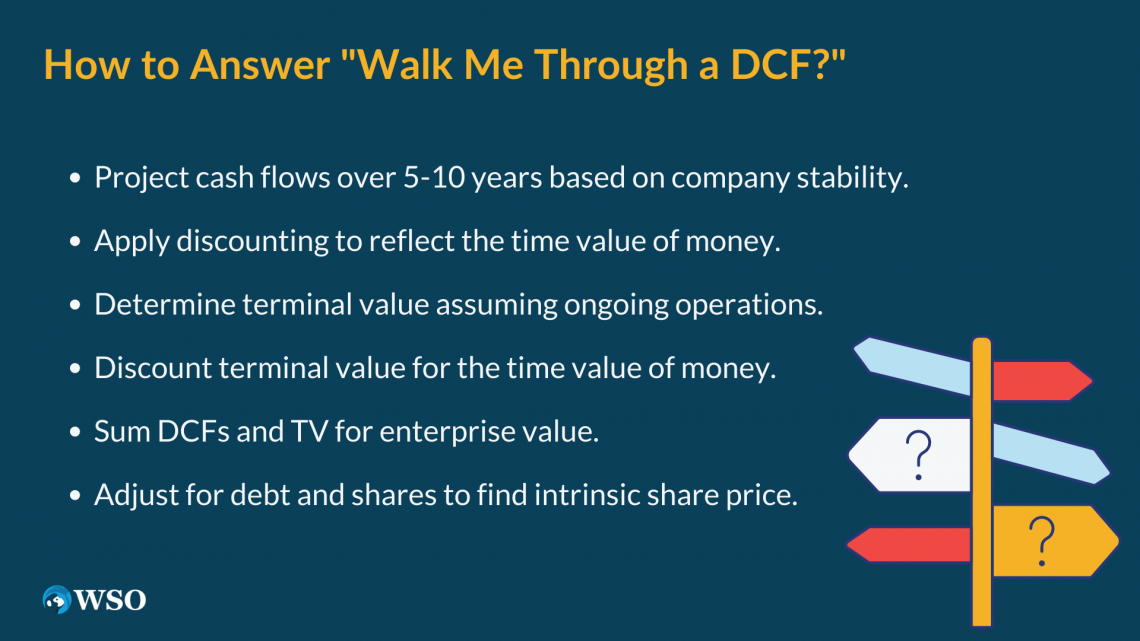
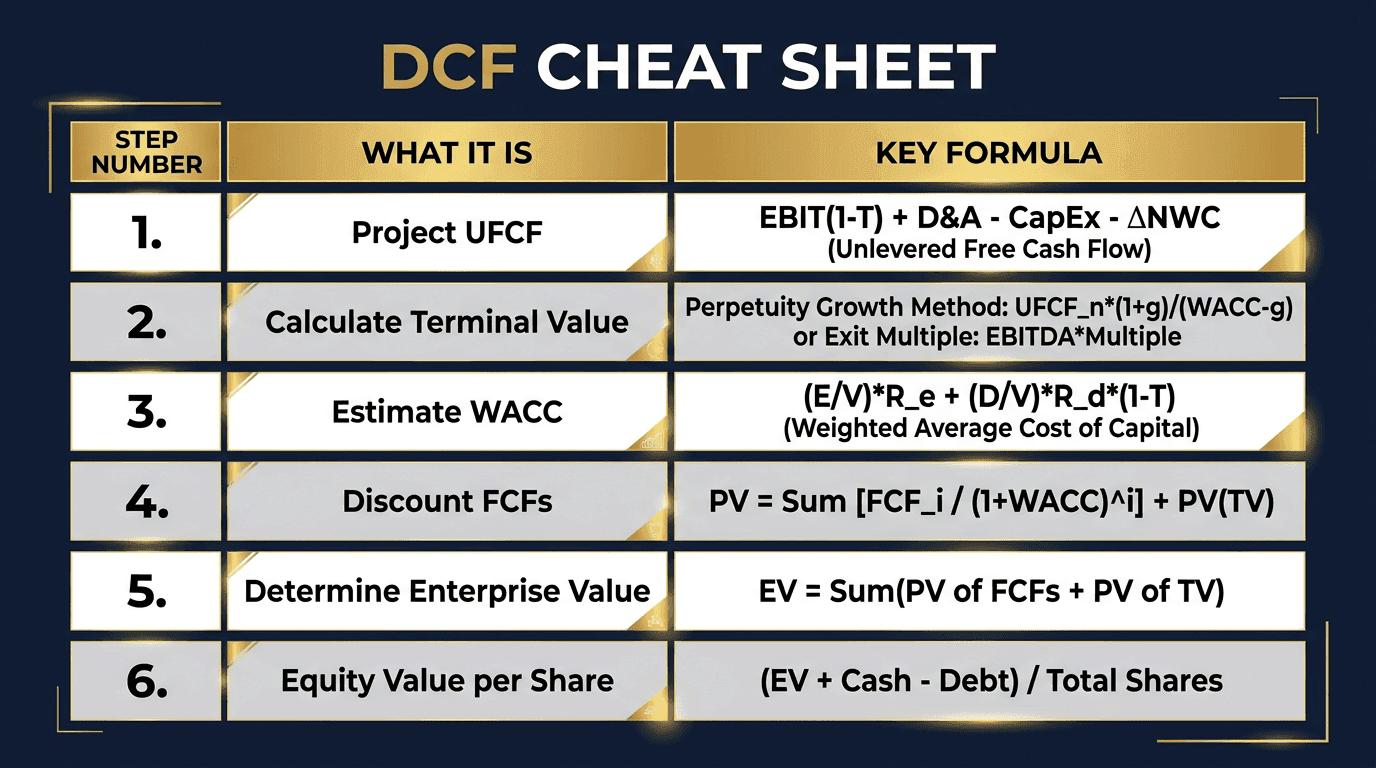
A DCF is just a way of figuring out what a stream of future cash flows is worth right now. You project the cash, you pick a discount rate, you slam everything into a formula, and you get a number. That number is your intrinsic value estimate. Nothing mystical about it. The real work isn't the math, it's deciding what goes into the math. Here is how I actually walk through one when someone asks me to Walk Me Through A Dcf. First step is always free cash flow to the firm, not net income. FCF tells you what is actually available to pay everyone who has a claim on the business — debt holders, equity holders, whoever. Start with EBIT, add back depreciation and amortization because those are non-cash charges, subtract taxes on a cash basis, subtract the change in working capital, and subtract capital expenditures. That gives you unlevered free cash flow for each year you are projecting out.
Walk Me Through A Dcf from start to terminal value
After you have your projected FCFs, usually five to ten years depending on the business, you need a terminal value. The Gordon Growth Model is the standard approach. You take the final year's FCF, grow it by a sustainable long-term rate, and divide by the discount rate minus that growth rate. Most people use three percent for the terminal growth rate because anything higher without strong justification looks lazy, and the discount rate is typically your weighted average cost of capital. Then you discount everything back. Each projected FCF gets divided by one plus WACC raised to the power of the year. The terminal value also gets discounted back to present value even though it represents all cash beyond year ten. Add those two pieces together and you have enterprise value. Subtract net debt and you arrive at equity value per share. I remember running into a specific problem with a small manufacturing company where working capital was eating the entire valuation. Their accounts receivable had been drifting from thirty days to fifty-five days over two years, and when I pulled the change in working capital into the FCF model, it tanked every single projected year. The deal looked terrible on paper. The workaround was digging into their actual invoice data and finding that forty percent of that AR increase came from a single customer who was effectively using the company as a short-term lender. I normalized that out by keeping the AR at a rolling sixty-day sales average rather than letting the raw balance sheet spikes distort the projection, which brought the valuation back to something reasonable.
The discount rate is where most people mess up. WACC is not a number you pull out of thin air. It is cost of equity times the equity weight plus cost of debt times the debt weight times one minus the tax rate. Cost of equity comes from CAPM, which means you need a beta, a risk-free rate, and an equity risk premium. Using a raw industry beta from a financial data site is dangerous because betas vary wildly depending on the time window and the regression methodology. I always re-lever and un-lever the beta manually to match the target company's actual capital structure instead of trusting the published number. Another counter-intuitive thing nobody talks about enough is that higher growth does not always mean higher valuation in a DCF. When you force high growth into the early years, working capital and capex tend to consume more cash, which can compress free cash flow right when your model needs it to look impressive. I have seen models where a company with moderate five percent growth had a higher intrinsic value than a company projecting twenty-five percent growth because the high-growth company needed to reinvest almost everything it earned just to sustain that expansion. The free cash flow margin collapsed and the terminal value could not compensate for it. There is also the sensitivity analysis piece that separates amateurs from people who actually use this at work. A single DCF output is meaningless without testing how sensitive it is to your assumptions. I run a quick two-variable data table changing WACC between eight and twelve percent and terminal growth between two and four percent. The result is usually a range spanning thirty to fifty percent of the base case number, which tells you immediately how much confidence you should actually have in the valuation.
Get the Full Details

The biggest limitation of a DCF is that it is almost entirely garbage-in-garbage-out. If your revenue assumptions are wrong by even ten percent, the output moves dramatically because you are compounding those errors over five or ten years. A DCF also breaks down completely for companies with negative free cash flows, cyclicals during a trough, or businesses where capital requirements are unpredictable. I would not waste my time trying to force a DCF on a pre-revenue biotech company or a commodity mining firm with volatile capex cycles. For those situations, relative valuation with EBITDA multiples or scenario analysis with real option modeling gives you something closer to useful. The process itself usually takes me between forty-five minutes and two hours for a standard mature company, longer if the capital structure is messy or the working capital dynamics need that kind of normalization I mentioned. Spreadsheet time is fast. The slow part is digging through financial statements to validate that your inputs are not just plausible but defensible when someone asks you about them. That is where the actual skill lives, not in knowing the formula.