Getting Through the Wall Street Prep Financial Statement Modeling Exam
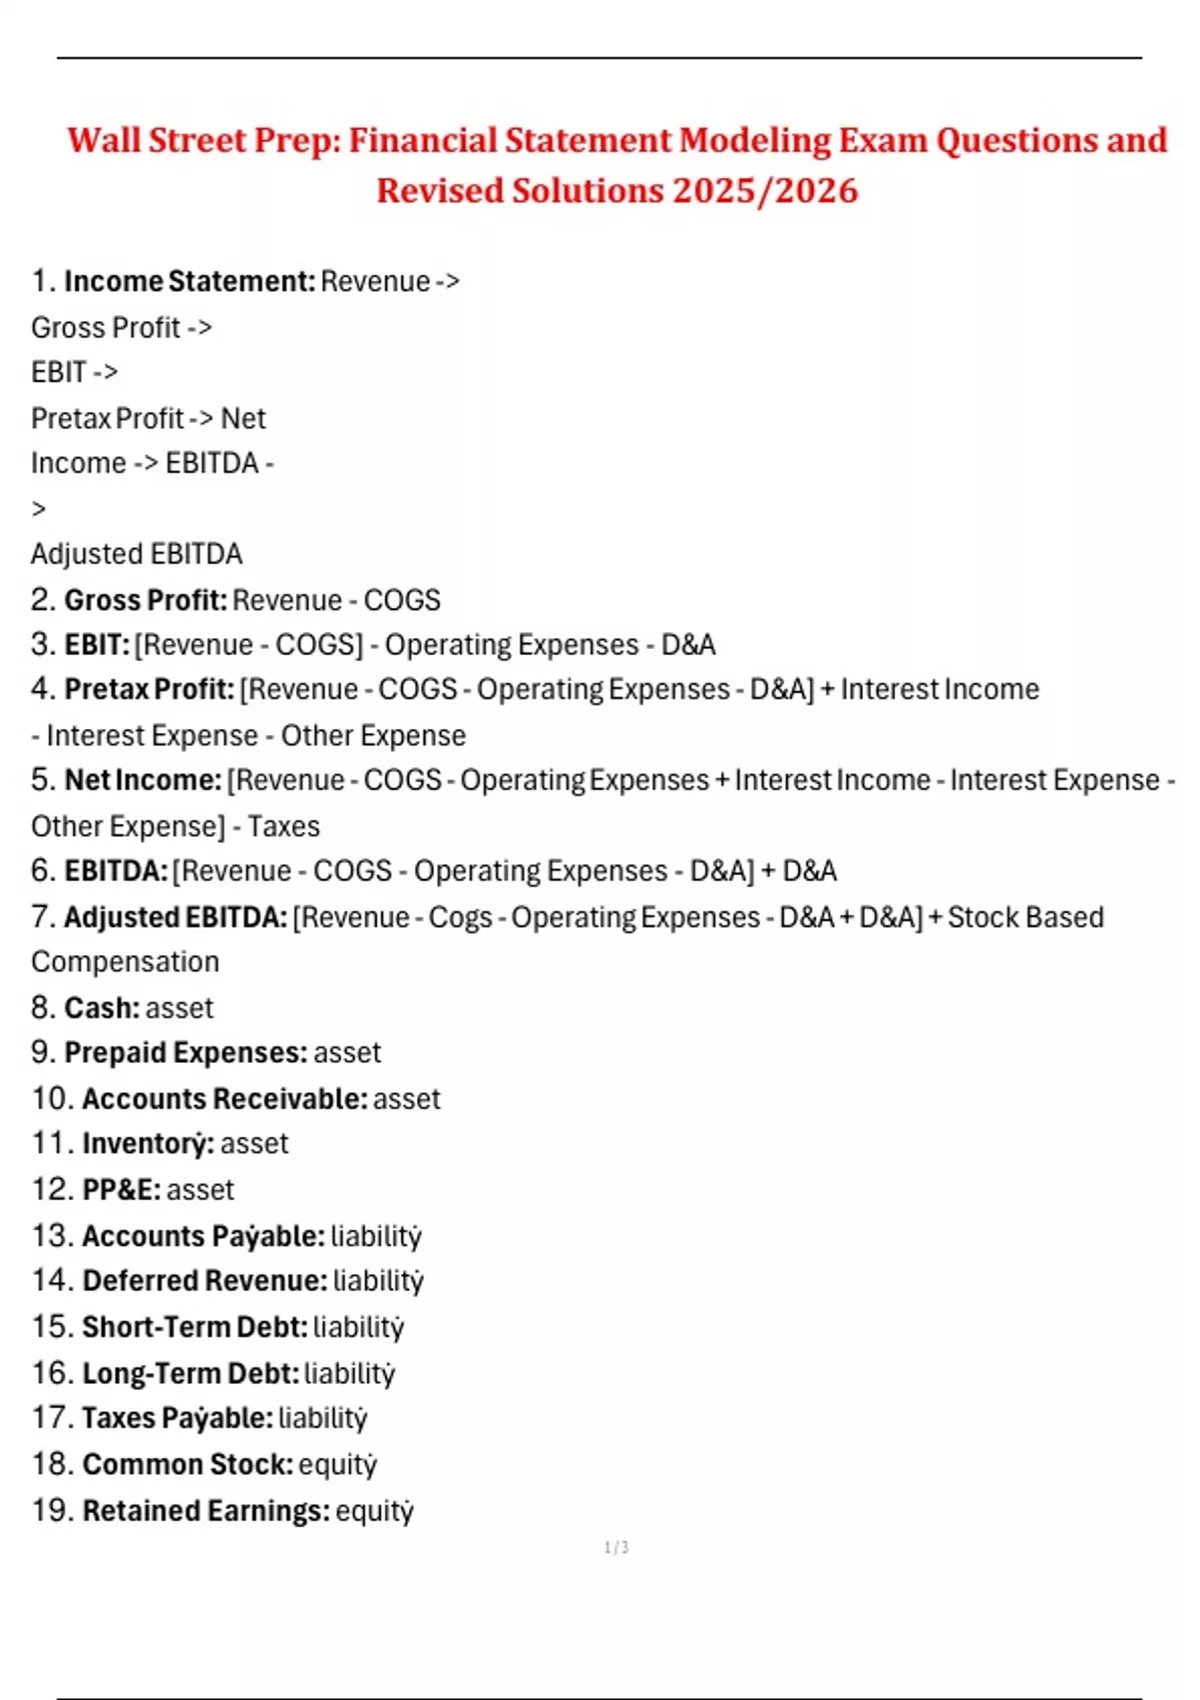
The Wall Street Prep Financial Statement Modeling Exam tests whether you can build a basic three-statement model from scratch in a timed setting. It is not a gentle introduction to financial modeling. The interface is clunky, the timer does not stop for bathroom breaks, and the grading rubric is strict about formatting details most people overlook until they fail. I have proctored a few of these myself and also taken it when getting my team on board. The exam gives you a raw Excel file with historical income statement, balance sheet, and cash flow data, then asks you to project three forward years while keeping everything balanced. You need to link all three statements properly, handle working capital, capex, debt, and depreciation. Everything ties through the cash flow statement, which means if you make one small mistake early, you will likely spiral by year two.
What You Actually Face During the Wall Street Prep Financial Statement Modeling Exam
The test interface loads your Excel file, and you work inside a locked-down browser session. There are no copy-paste shortcuts in some versions, which slows people down who rely heavily on keyboard navigation. The timer runs continuously. Most candidates finish in about 45 to 75 minutes if they are comfortable with three-statement modeling, but first-timers often blow past the time limit because they keep going back to fix broken links. One thing nobody warns you about is the cash flow statement formatting. WSPrep expects you to place changes in working capital accounts as separate line items rather than netting them into one line. When I took the exam cold, I combined receivables, payables, and inventory into a single working capital line. The system flagged it, and I had to rework three years of cash flows. That cost me roughly eight minutes and a dent in my confidence. The workaround was simple enough, but in the moment it felt like the walls were closing in. You just split them out properly and move on. The grading looks at five areas: income statement projections, balance sheet balance, cash flow statement accuracy, linkages between statements, and assumptions. The assumptions section is where most people lose points. You need explicit assumption cells that drive your projections, not hardcoded numbers inside formulas. If your revenue growth is baked directly into a SUMPRODUCT without a referenced assumption cell, the grader marks it down.
The Practical Workflow That Actually Works
Start with revenue. Build your growth assumptions first, then apply them to last year's revenue line. Depreciation should link back to your fixed asset schedule, which you build early. Do not defer that. Many candidates skip the fixed asset schedule until the end and then panic because depreciation does not flow into accumulated depreciation correctly. Working capital needs its own sub-schedule. Receivables days, payable days, inventory days. Calculate the projected balances using those day metrics, then derive the changes for the cash flow statement. Keep the day counts as explicit assumption cells. Your cash flow statement should show the changes from that schedule, not manual entries. The balance sheet is where things collapse for most people. You need to build a debt schedule too, even at a basic level. Enter your starting debt balance, assume repayments or new borrowings, calculate interest expense based on average debt, and flow that to the income statement. Then plug the missing cash figure to make the balance sheet balance, or better yet, let cash be the calculated output rather than forcing a plug. The grader prefers a self-balancing model over a hardcoded plug cell.
Get the Full Details
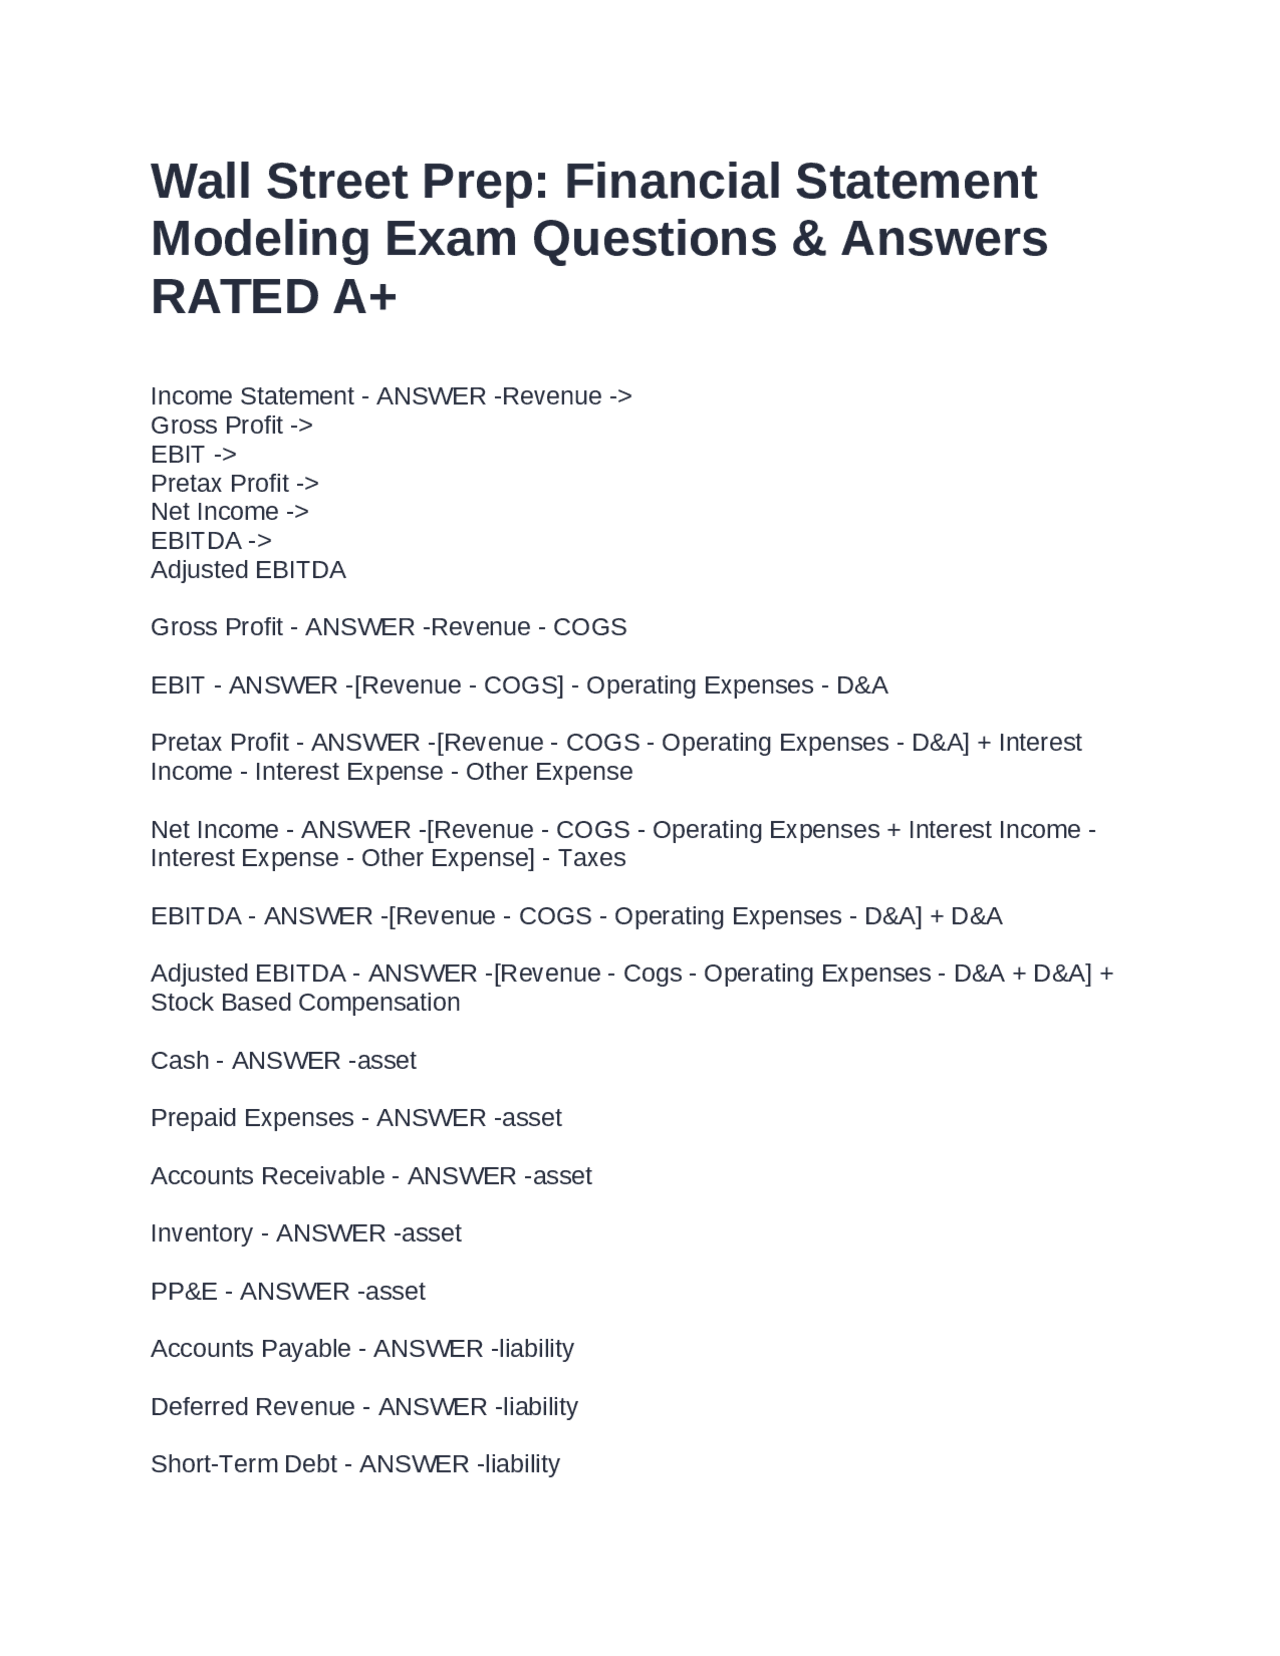
I learned the hard way that the cash balance calculation order matters more than most people realize. If you compute net income, then depreciation, then working capital changes, then capex, then interest and tax, your cash flow from operations and investing and financing lines will cascade correctly. Mess up the tax calculation by applying it to earnings before interest instead of after, and your net income will be wrong, which cascades into retained earnings, which cascades into your balance sheet. I once lost 12 minutes rechecking three years of tax calculations because I used EBIT instead of EBT as the tax base. Make sure you apply the tax rate to earnings before tax, not revenue minus operating expenses.
Common Pitfalls That Cost Points
One counter-intuitive issue is circular references. Some students try to make interest expense circular by referencing average debt, which itself depends on cash, which depends on interest. The exam software may not handle circular references well, and even if it does, the grader may penalize you for not breaking the circle with a simple iterative approximation or a helper cell. Break it out explicitly. Calculate interest on beginning-of-year debt in the first pass, or use a dedicated interest calc cell that does not depend on the ending cash balance. That is the professional approach and what the exam expects. Another pitfall is forgetting that accumulated depreciation needs to roll forward. Beginning accumulated depreciation plus current year depreciation equals ending accumulated depreciation. If you link this incorrectly, your fixed assets net will be wrong, and your balance sheet will not balance. I have seen models where people linked ending accumulated depreciation directly to the current year depreciation line without the rollforward, which creates a broken linkage that only shows up when you try to balance the sheet. Formatting also matters more than you think. The WSPrep rubric checks for consistent number formatting, proper sign conventions on the cash flow statement, and clear separation between inputs and calculations. Use color coding if you want: blue for hardcoded inputs, black for formulas. This is standard practice on Wall Street and the exam expects it. Mixing input colors with formula colors makes your model look amateurish and costs you points on presentation.
When This Exam Falls Short
Here is the honest part. The Wall Street Prep Financial Statement Modeling Exam is useful for validating that you understand the mechanics of three-statement modeling. It is not useful for teaching you how to actually model a business. The scenarios are generic, the time pressure rewards speed over rigor, and it does not test sensitivity analysis, scenario management, or any of the things that matter in real deal work. You can pass this exam and still struggle to build a model that handles complex debt structures, minority interests, or consolidation entries. If your goal is to get a job in investment banking or equity research, this exam is a decent checkpoint, but it is not sufficient preparation on its own. You should supplement it with actual deal modeling practice, preferably on live companies with messy data. The exam environment is too clean and too controlled to reflect reality. Real models break in ways that this test never prepares you for. For the exam itself, practice builds the speed you need. Time yourself on a full three-statement model under 60 minutes before you take the real thing. Most people who rush through it without prior timed practice miss at least one linkage error that costs ten minutes of debugging. Build the model in the right order, keep your assumption cells clean, and do not touch the cash balance as a plug unless absolutely necessary. That is how you get through it without losing points on preventable errors.