Understanding NYS Assessment Receivables in Practice
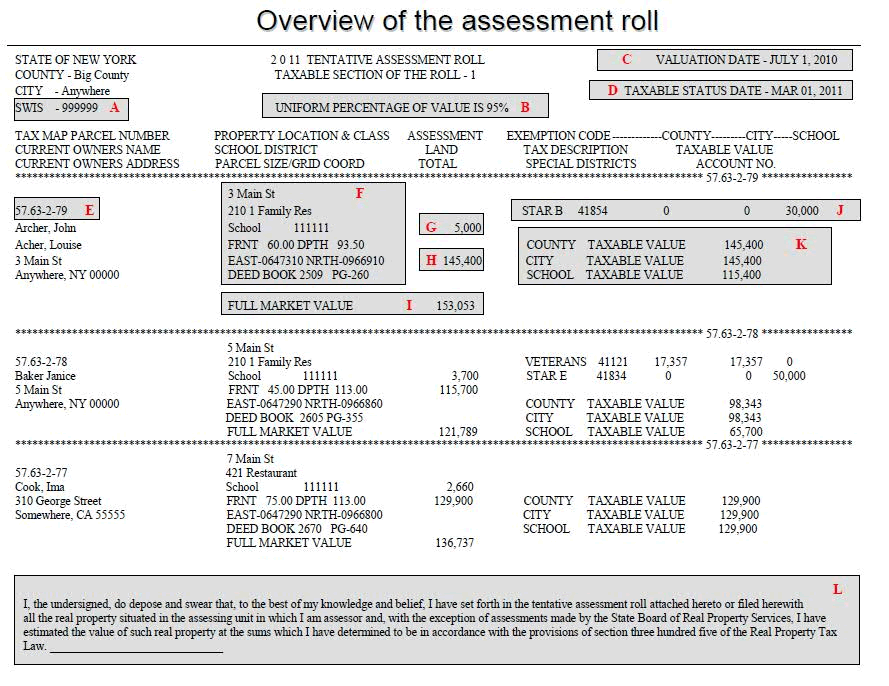
Assessment receivables show up on every municipal and school district balance sheet in New York State that levies property-related charges. They represent money owed to the locality by property owners for taxes, special assessments, or surcharges that have been formally levied but not yet collected. On the books, you will see them split into current receivables and delinquent receivables, with separate tracking for real property, personal property, and special ad valorem lien (SAVL) obligations. The mechanism is straightforward but the execution gets messy fast. The local tax assessor determines the taxable value, the taxing jurisdiction sets the rate or assessment amount, and the tax clerk or finance office records the receivable when the roll is certified. Collection happens through the county tax bureau during the annual collection cycle, and any unpaid amounts move into delinquency with penalties and interest accumulating according to NYS Real Property Tax Law section 921.
What Is Nys Assessment Receivables and How It Actually Works
I deal with this on the municipal finance side regularly. The core question most people have is whether assessment receivables are the same thing as tax receivables. They overlap significantly but are not identical. A special assessment for a sidewalk improvement or a sewer district charge is recorded as an assessment receivable even though it is not a general property tax. School district charges like highway maintenance assessments or fire district special levies also fall into this category. The distinguishing factor is that the amount is tied to a specific parcel or a defined group of parcels rather than being a blanket levy across the entire jurisdiction. Here is where beginners consistently mess up the accounting treatment. Under New York State comptroller guidance and GASB standards, you need to record the gross receivable first and then apply a separate allowance for uncollectible amounts. Do not net the two. I have seen districts skip the allowance entirely and just report the face value, which looks cleaner on a one-page summary but completely misrepresents the collectibility position. The allowance should be calculated using either the percentage-of-receivables method based on historical write-off trends or the aging method if your system supports it. For typical New York school districts and small towns, a reserve of 2 to 5 percent of gross assessment receivables is the norm, but that ratio jumps significantly in districts with high vacancy rates or in rural areas where property values are low and the tax base is thin. The collection window adds another layer of complexity. New York State has a very specific timeline. Taxes become delinquent after the final payment date set by each jurisdiction, which is usually late January or early February for school districts and most general purpose governments. Once delinquent, the county takes over collection and the receivable moves from the municipality's books to the county's delinquent tax roll. The municipality still carries the receivable but reclassifies it, and the county applies statutory penalties and interest. If the property goes to tax sale, the receivable is ultimately written off against the delinquent tax redemption fund or the general fund depending on how your local resolution structures it.
One edge case that costs people a lot of sleep involves mixed fiscal years and mid-year transfers. If a school district or special district changes its fiscal year or consolidates with another jurisdiction, the assessment receivables do not simply transfer dollar for dollar. You have to reconcile the certified roll as of the transition date, account for any payments already collected by the old jurisdiction, and handle any properties that were newly assessed or newly exempt during the gap period. I worked through this exact scenario when a small Upstate New York school district merged its operations with a neighboring corridor district. The transition date did not align with the tax roll certification date, which meant approximately 14 percent of the receivables were sitting in a reconciliation limbo for nearly eight months. The workaround was to establish a clear cutoff protocol with the county tax director upfront, pull a pre-certification roll to identify every parcel that would change hands, and build a temporary holding account in the general ledger that tracked each receivable against its originating jurisdiction until the transfer was finalized. That protocol cut the reconciliation time from roughly three weeks per cycle down to about four days once we had the template in place. Another counter-intuitive point that almost nobody flags: assessment receivables can appear healthy on the surface while the underlying collectibility is degrading. The reason is that New York State allows a wide range of tax abatements and exemptions that get recorded after the initial levy. A property that shows a full assessment receivable on the certified roll might later receive a STAR exemption, a basic STAR credit, or a home improvement exemption that reduces the actual cash collected. Your receivable ledger needs to account for these downstream adjustments, or your cash flow projections will consistently overshoot by 3 to 8 percent depending on how many exempt properties sit in your district. For practical record-keeping, the most reliable setup uses a subsidiary ledger that tracks each receivable by parcel ID, originating levy, due date, delinquency status, penalty and interest accrual, and the current collection phase. The general ledger control account stays reconciled to that subsidiary on a monthly basis. If you are running this on a spreadsheet instead of a proper accounting system, at minimum use a separate tab for current receivables, delinquent receivables, and estimated uncollectibles, and never mix cash receipts against delinquent balances without a clear allocation rule. The state audit staff will pull that reconciliation immediately.
Get the Full Details

The downside of this whole system is that it is inherently backward-looking. Assessment receivables tell you what was levied and what has been collected to date, but they do not predict future collections in volatile markets. When property values drop sharply or a major employer leaves the district, the receivable balance stays fixed on the books while the actual collectibility deteriorates. The allowance method catches this eventually, but there is always a lag of one to two collection cycles before the numbers reflect the reality on the ground. The only real mitigation is to run quarterly collectibility reviews that factor in recent sale prices, vacancy trends, and any pending exemptions rather than waiting for the annual audit to surface the problem.