Why Profit Gets Misunderstood
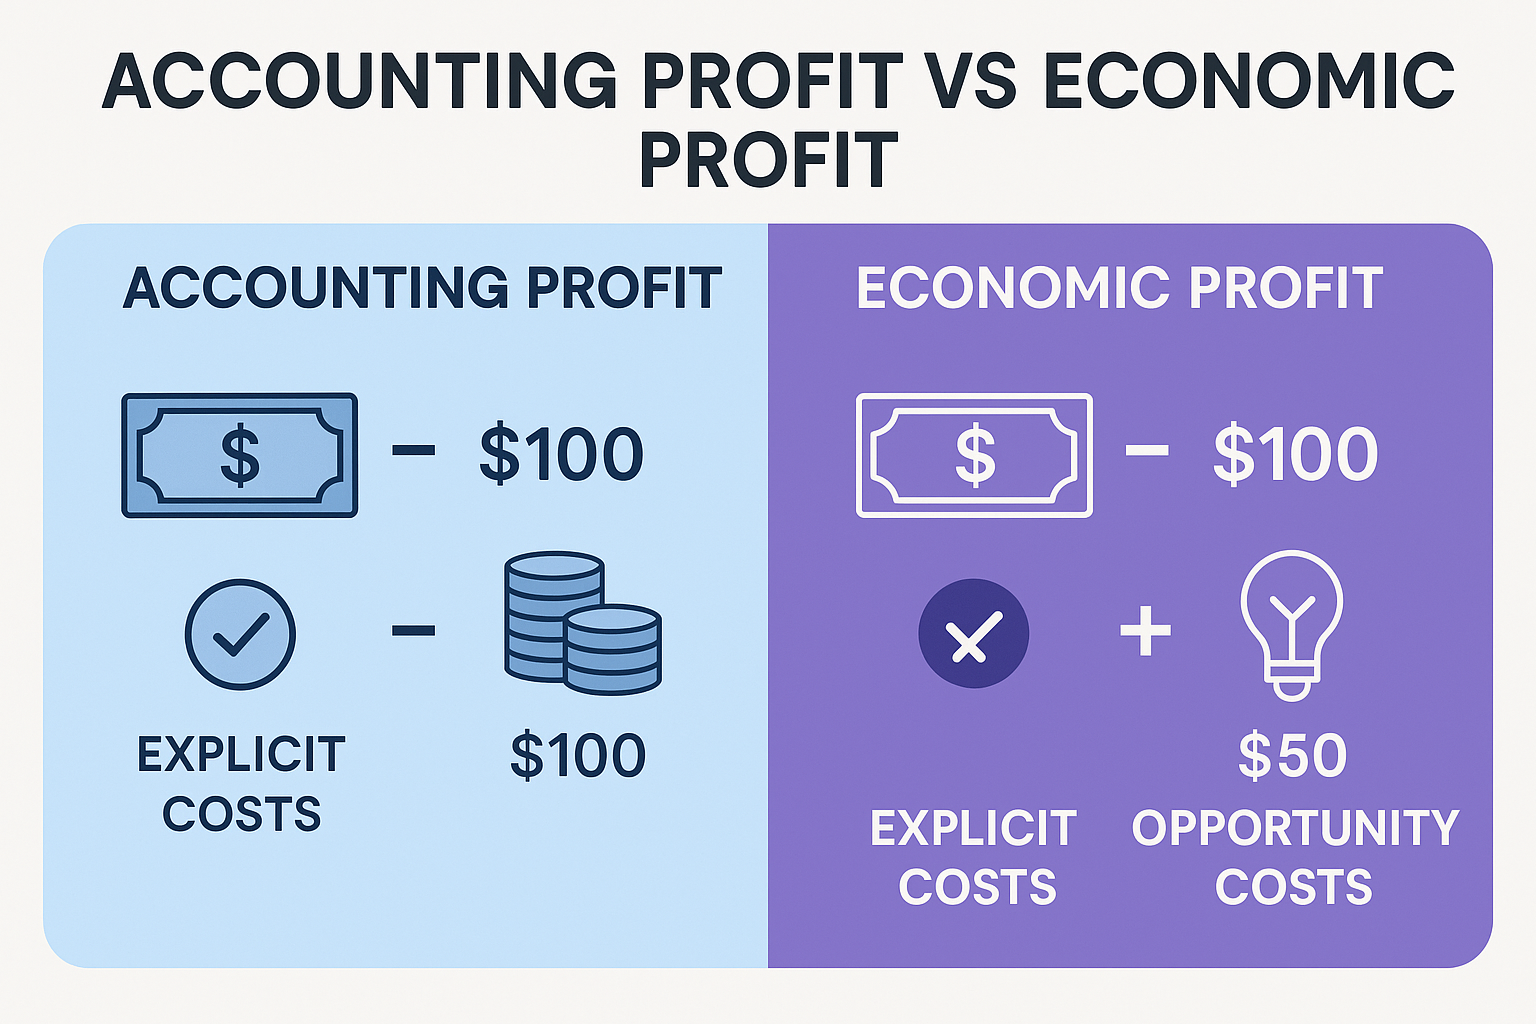
Profit in an economic system is straightforward if you stop reading textbooks that treat it like a moral statement. It is the residual value remaining after all costs are accounted for. That is it. Most people confuse accounting profit with economic profit, and that confusion causes real mistakes in business decisions and policy debates. The difference matters. Accounting profit simply subtracts explicit costs from revenue. Economic profit subtracts both explicit costs and opportunity costs. A factory making fifty thousand dollars in accounting profit while the owner could have earned eighty thousand doing something else is actually at a loss from an economic standpoint. People rarely think this way though. They see the positive number and celebrate.
What Is Profit In An Economic System
The core definition involves three components. Revenue minus explicit costs minus implicit costs equals economic profit. Explicit costs are things that show up on an invoice. Rent, wages, materials, utilities. Implicit costs are the next best alternative use of resources already committed to this venture. When you use your own building instead of renting it out, the foregone rent is an implicit cost. When you work full-time in your own company instead of taking a salaried job, that salary is an implicit cost. I worked with a mid-market manufacturing firm a few years back where the owner was convinced the company was thriving because it showed steady accounting profits year after year. We ran the numbers properly including opportunity costs of his capital and his time and discovered the business was actually destroying value. The capital tied up in machinery and inventory could have returned roughly twelve percent in a diversified portfolio. The business was earning about seven percent on that same capital. He had been watching the income statement and missing the real picture entirely. This happens constantly. The workaround was switching their internal reporting to include a capital charge calculation so every division saw their economic profit alongside accounting profit. It took about two weeks to restructure the reporting template and another month to get management to adjust their behavior based on the new numbers. Market structure changes how profit functions. In perfect competition, economic profit tends toward zero in the long run because entry and exit erode any excess returns. This is not a theory-only concept. I have seen commodity trading desks where new entrants drove margins down to barely covering cost of capital within eighteen months of a price spike attracting attention. The initial wave of profit disappears as capacity expands.
Monopolies and oligopolies sustain positive economic profit longer because barriers to entry prevent the competitive erasure. But even there, profit gets compressed by regulation, substitution threats, or technological disruption. The real insight nobody talks about is that sustainable profit usually comes from creating temporary barriers, not from existing in a comfortable position. Patents expire. Networks get disrupted. Consumer preferences shift.
Get the Full Details
How Profit Actually Works In Practice
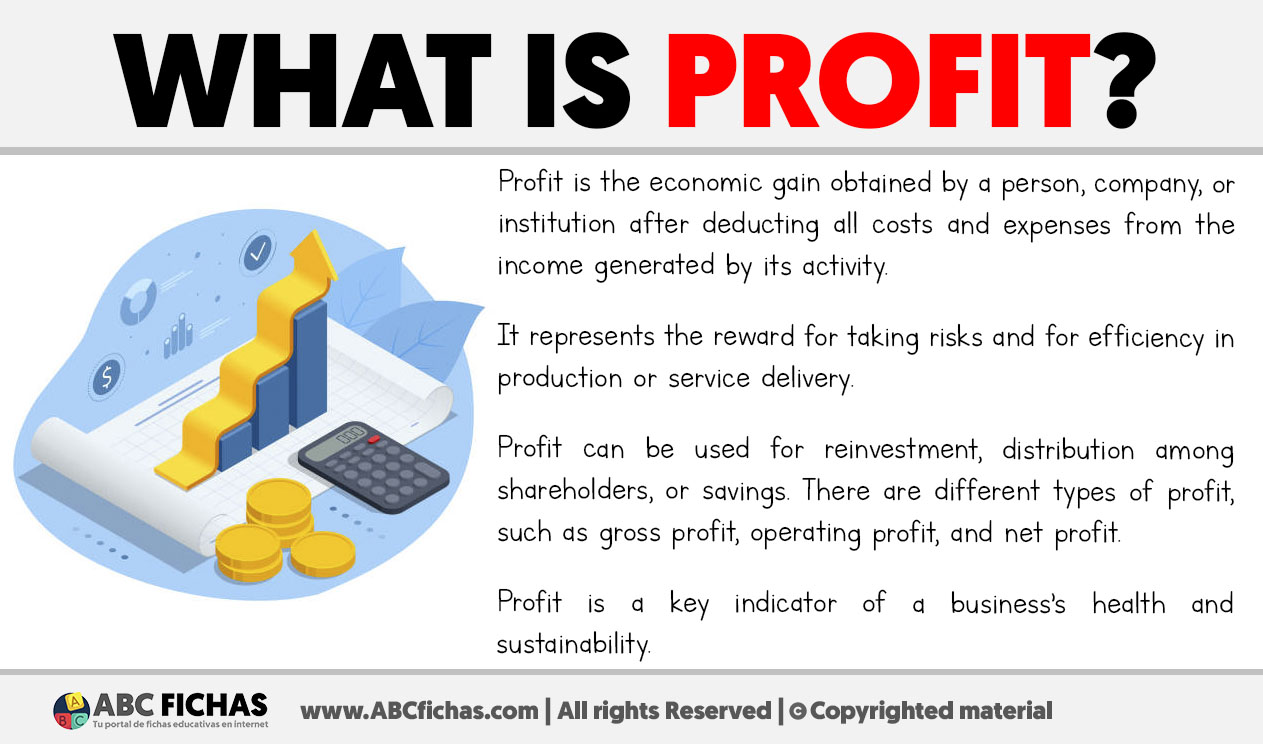
The mechanism is simple. A buyer values a good more than the cost of producing it. The difference is the profit opportunity. If someone will pay one hundred dollars for a chair and it costs eighty dollars to make, that twenty dollar gap is potential profit. The market pushes this gap toward zero through competition, but new opportunities constantly open somewhere else. Innovation creates fresh gaps. Regulatory changes create gaps. Information asymmetries create gaps. Profit is the signal that tells resource allocators where value is being created or destroyed. One thing beginners consistently miss is that profit is not the same as cash flow. A company can be profitable on paper and run out of money. I watched a software services firm collapse this way. They had strong revenue growth, decent margins on paper, but their payment terms required upfront material costs while clients paid net sixty. The accounting profit looked fine. The bank account told a different story. Economic profit considerations would have flagged this cash conversion cycle problem much earlier if they had been looking at the full picture including working capital requirements. The counterintuitive part is that zero economic profit is actually a healthy state for a competitive industry. It means all resources are being used efficiently and earning their next best alternative return. Positive economic profit attracts competition. Negative economic profit drives exit. Both movements are the market doing its job.
There is also a time dimension that most people ignore. Profit calculations depend entirely on the time period you are measuring. A retail store might show monthly economic losses during build-out and then substantial economic profits once customer volume stabilizes. Cutting measurement too short makes everything look worse than it is. Cutting it too long averages out important cycles. The sweet spot depends on your industry, but two to five years is typical for service businesses and three to seven years for capital-intensive operations. I learned this the hard way evaluating a restaurant group. Their first location lost money for fourteen months before reaching break-even, then turned consistent positive economic profit after that. An investor looking at only the first six months would have passed on what became a solid returning business. The workaround was building pro forma models with location-specific ramp-up curves rather than applying aggregate company-level metrics to individual units. The biggest practical problem with measuring profit accurately is allocating shared costs. Corporate overhead, brand marketing, centralized IT systems. These benefit multiple business units but there is no clean way to split them. Different allocation methods can swing a division from showing positive to negative economic profit without changing actual performance. This is why sophisticated organizations use direct tracing wherever possible and only allocate when unavoidable, and they disclose their allocation methodology openly so stakeholders can adjust for it.
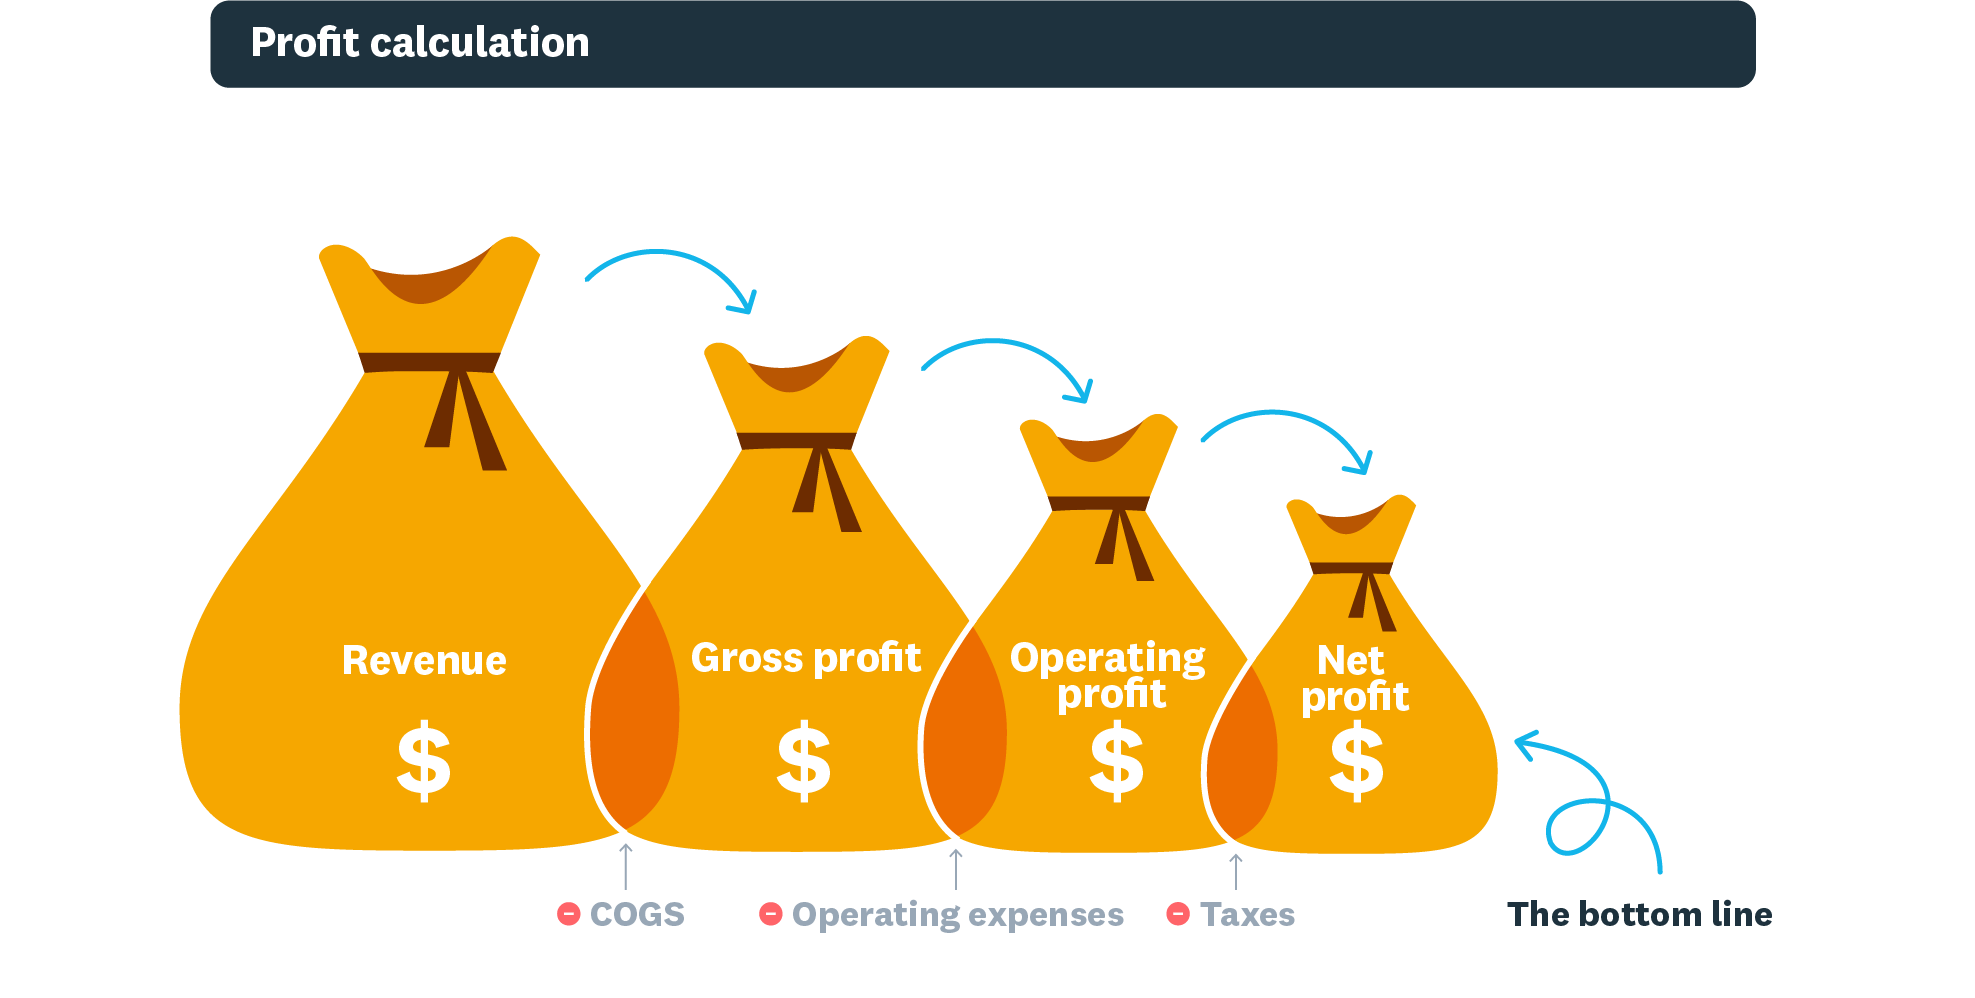
Government policy treats profit differently depending on the goal. Tax systems focus on accounting profit because it is verifiable and harder to manipulate. Competition policy focuses on economic profit because that indicates market power. Investors look at free cash flow to profit ratios because they care about actual distributable returns. Each lens is useful. Each is incomplete alone. The bottom line for anyone actually working with profit calculations is to stop treating it as a single number and start treating it as a family of related measures. Accounting profit, economic profit, operating profit, net profit margin, return on invested capital, free cash flow margin. They tell different stories. The right one depends on what decision you are trying to make. Cost accounting systems that feed into profit measurement are notoriously unreliable when they rely on arbitrary allocation bases. I have seen allocation rates shift product profitability by thirty percent simply because the denominator changed from machine hours to direct labor hours. The products did not change. The measurement method did. This is why activity-based costing exists and why most companies still ignore it because implementing it properly requires data infrastructure most organizations do not have.
There is also the behavioral angle that gets overlooked. How you define profit shapes how people behave. When bonuses tie to accounting profit, people cut R&D and maintenance. When they tie to economic profit with a full capital charge, they become more careful about tying up capital in low-return projects. The metric you choose becomes the behavior you get. This is not a criticism of any particular approach. It is just the mechanical reality of incentive design. If you want to apply this to real decisions, start by calculating your own opportunity costs honestly. What could your capital earn elsewhere? What could your time earn elsewhere? Then subtract those from your accounting profit. If the number is still positive, you are creating genuine economic value. If it is negative, you need to either improve the business or reallocate your resources. Most people who say they are making money are actually consuming wealth by staying in their current venture instead of moving to a better one. That is not always the wrong choice. Loyalty, passion, and strategic patience have value too. But you should know the real number before you make that call. The market does not reward profit for its own sake. It rewards the creation of value that exceeds the cost of resources consumed. Profit is just the accounting for that gap. Understanding which accounting you are using and what it actually measures is the difference between making good decisions and following a number that looks good on a spreadsheet while quietly destroying value underneath.