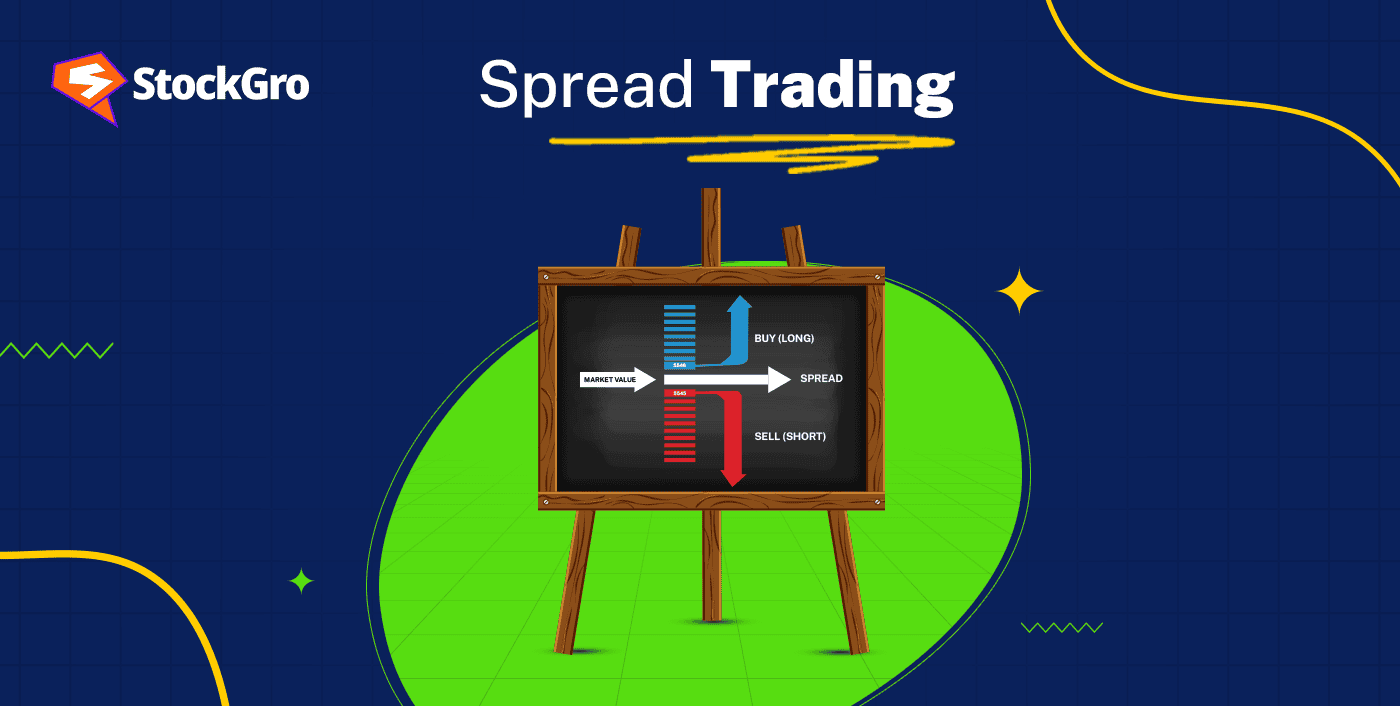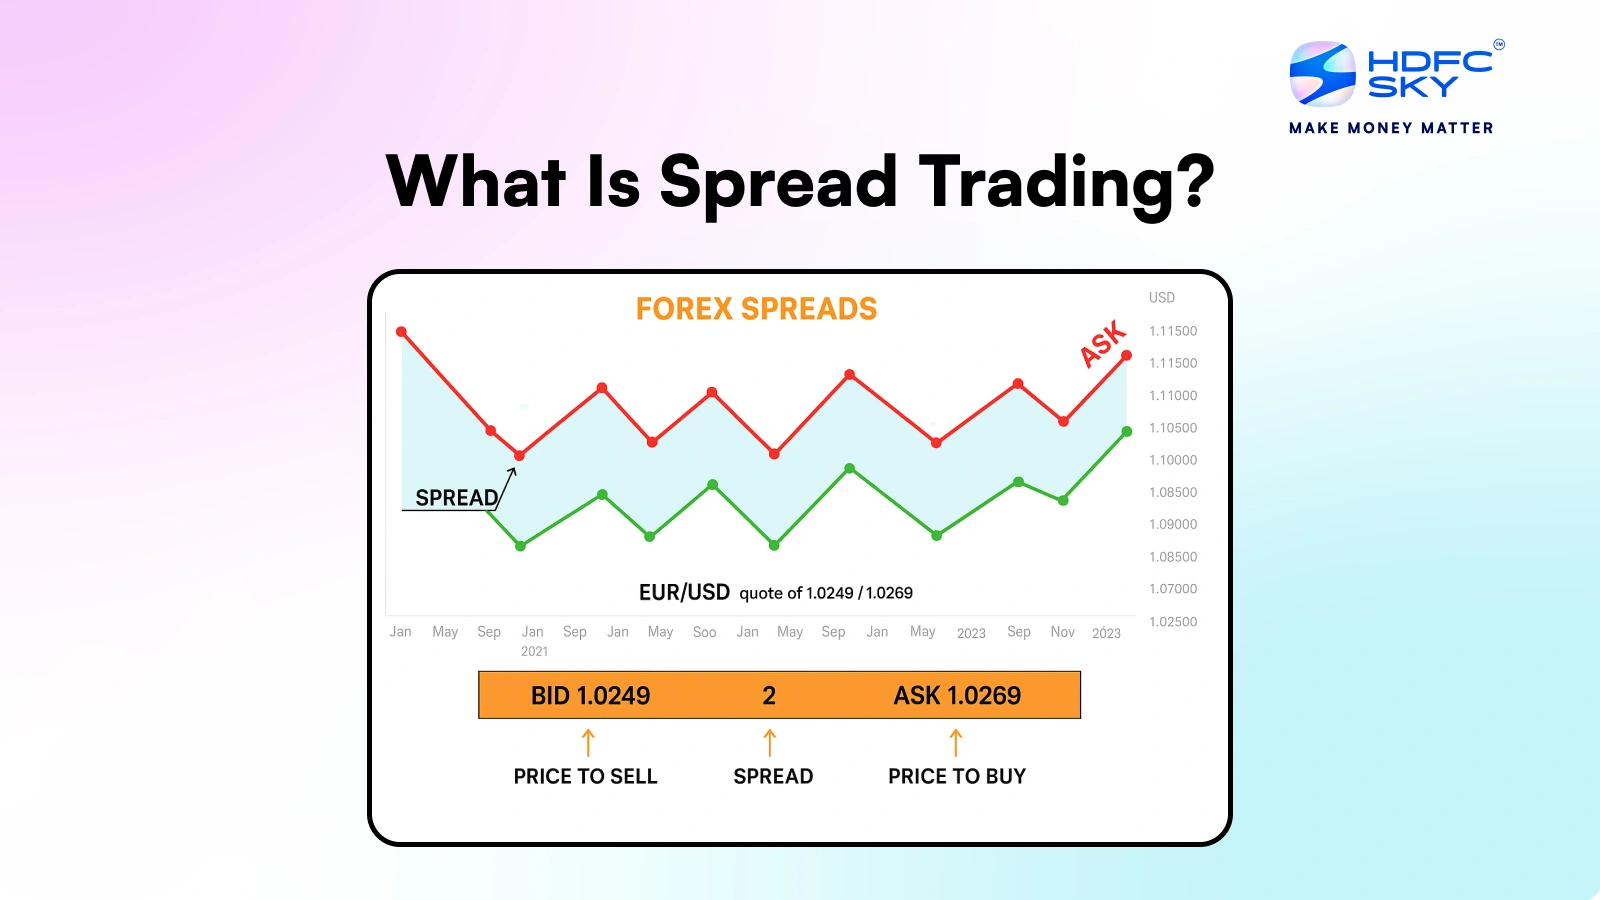
Spreads are just the gap between two related prices
Most people think spread trading means buying one thing and selling another at the same time. It's closer to that than it looks, but the details matter more than the definition. When you trade a spread, you're not betting on whether a commodity goes up or down overall. You're betting on whether the difference between two contracts gets bigger or smaller. Take corn. You might sell a nearby futures contract and buy a contract six months out. If the relationship between the two shifts in your favor, you close both legs and pocket the difference. The absolute price of corn doesn't matter nearly as much as how the two contracts move relative to each other.
What Is Spread Trading and Why It Exists
The concept has been around since futures markets first started matching orders in the 1800s. Merchants and farmers naturally hedged against seasonal price swings by locking in prices for delivery at different times. Eventually someone noticed that the price gap between, say, December wheat and March wheat moved in predictable ways, and trading that gap became its own thing. Today you see spreads across just about every asset class. Equity spreads — buying one stock while shorting another in the same sector. Commodity calendar spreads — same commodity, different expiration. Intermarket spreads — crude oil versus heating oil, or gold versus silver. Fixed income too. Treasury spreads are a whole different world from equity spreads. People use them because they tend to be less volatile than outright positions. If the whole market drops twenty percent, a well-constructed spread can lose far less. That's the theory anyway. In practice it depends entirely on what you're spreading and how correlated the two legs really are.
Here's the part nobody tells you when they're selling you on spread trading: the margins are cheaper, sure, but the profit per contract is also dramatically smaller. You're taking on less directional risk, so you're leaving money on the table compared to a pure long or short position. You're trading upside potential for reduced drawdown. That's the deal. You either accept it or you're trading the wrong instrument. I spent two years working with bond ETF spreads during the 2022 rate hiking cycle. The models looked fine on paper. The 2-year versus 10-year Treasury spread was compressed to historical lows, which supposedly meant it had to expand. The problem was timing. It stayed compressed for eleven months. I was right about the direction eventually, but the position was underwater for almost a full year before it moved in my favor. Most people blow up on spreads not because they pick the wrong direction but because they run out of patience or margin before the thesis plays out.
Get the Full Details

How to actually set one up
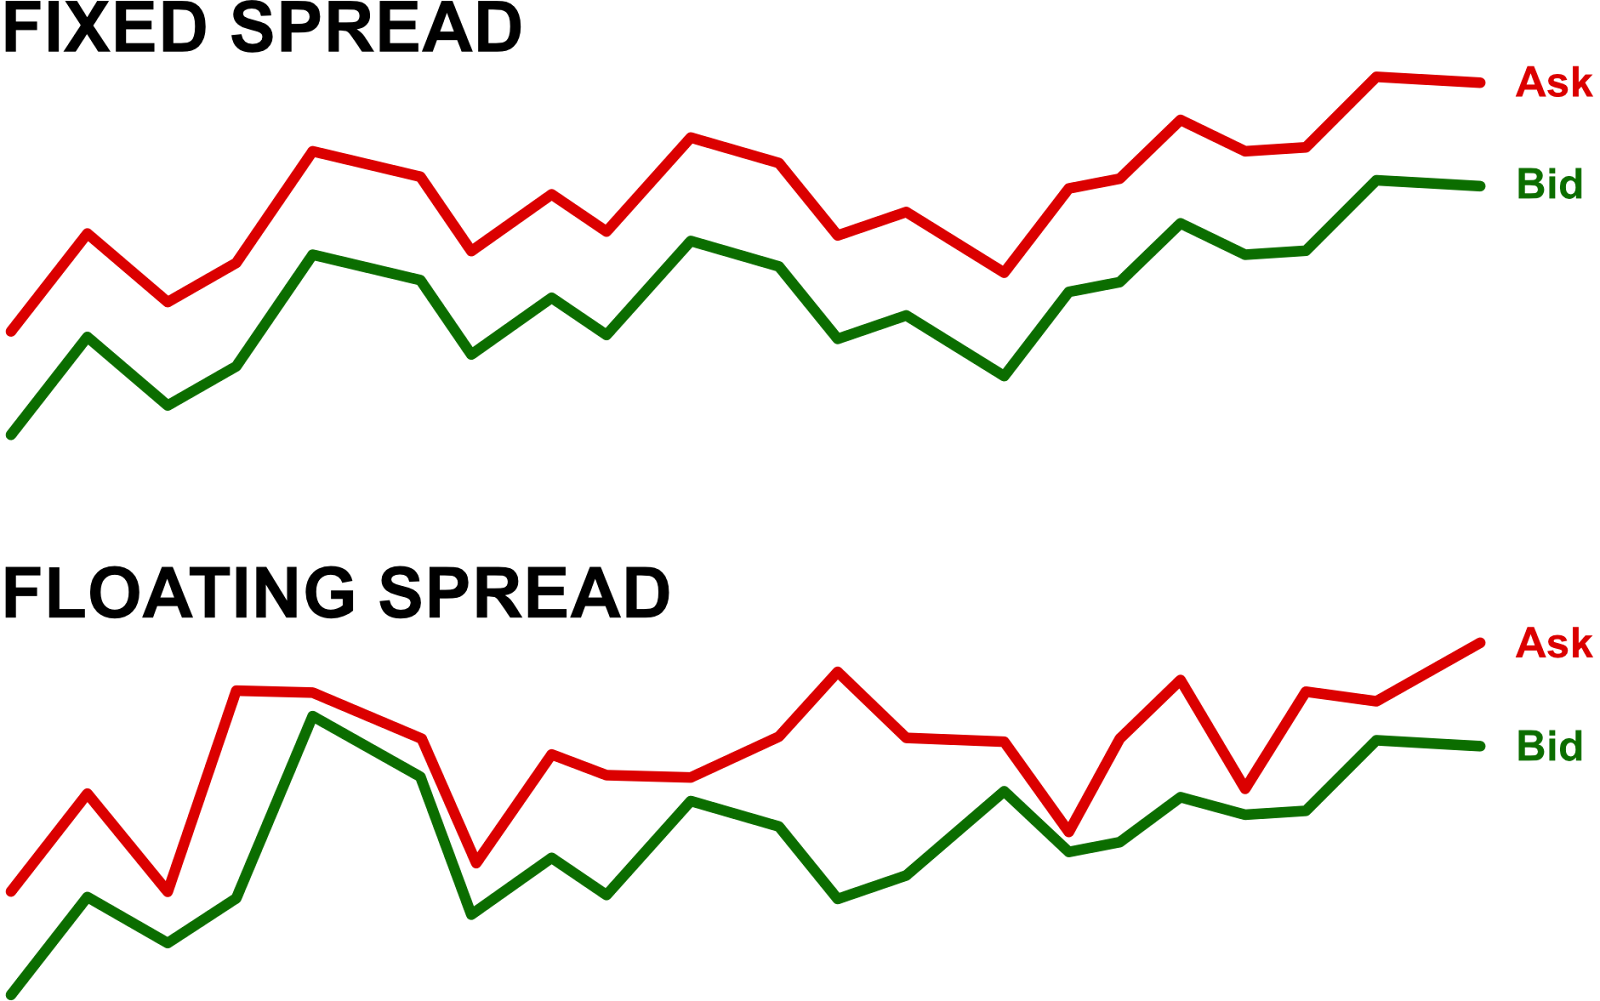
First you pick your spread type. Calendar, inter-commodity, or inter-market. Each one has different margin requirements, different execution complexity, and different risk profiles. Then you check the correlation. Not the headline number, the rolling correlation over different windows. Two things might look perfectly correlated over the last thirty days and have a completely different relationship over the last three years. I use a rolling 60-day correlation check on every spread I consider. Anything under 0.7 is a yellow flag. Under 0.5 and I'm usually walking away unless there's a fundamental reason I'm confident about. Next comes entry. Spreads trade differently than single instruments. They often have wider bid-ask spreads themselves, especially in illiquid contracts. You need to place limit orders on both legs simultaneously or use a spread order if your broker supports it. If you fill one leg and not the other, you're suddenly exposed to the underlying risk you were trying to hedge. That happens more often than people admit, particularly around earnings or economic releases when liquidity pulls away.
Sizing is where most traders screw up. You might think that because margin is lower, you should go bigger. Don't. The margin discount is misleading. Brokerages give you a margin break on spreads because the risk is lower, but they don't reduce it proportionally to the actual risk reduction. A lot of the time you end up with more notional exposure per dollar of margin than you think. I had a client who ran a platinum versus palladium ratio spread in early 2023. He sized it based on the margin requirement alone, which looked tiny compared to a single-metal position. The spread tightened against him for six weeks, then went parabolic in the wrong direction. He got margin called on a position he thought was conservative. We rebuilt his approach using a fixed notional sizing rule instead of a margin-based one. It was less exciting but kept him alive.
The mechanics under the hood
When you open a spread, you're entering two linked orders. A debit spread costs you money to enter and profits if the spread moves in your predicted direction. A credit spread does the opposite — you collect cash upfront and make money if the spread moves against you in a specific way. Options spreads follow the same logic but add time decay as a factor you have to watch constantly. Rolling is the other thing that separates people who do this regularly from people who dabble. Spreads don't just sit there. As contracts expire, you roll the near leg into the next expiration. That costs money in commissions and slippage. On a tight spread with low volatility, those roll costs can eat your entire edge over a year. I track roll cost as a percentage of expected spread movement. If rolling costs more than ten percent of the typical range I expect the spread to move, I reconsider whether the trade is worth the operational drag. Execution quality matters more than most people realize. A spread that looks good on your screen might trade three ticks away from the quoted price once you actually try to fill it. Algorithmic execution on spreads is better than it was five years ago, but it's still a problem in less liquid contracts. I always split fills across multiple sessions if the spread isn't actively traded. It adds time but saves a significant amount in slippage.
There's also the matter of monitoring. A single-stock position you can set alerts on and forget. A spread has two legs, each with its own liquidity profile, each reacting to different news. A geopolitical event might hit one commodity hard while leaving the other untouched. The spread could widen or compress based on factors that have nothing to do with the relationship you were originally trading. I keep a watchlist of everything that moves either leg independently. If I'm trading a corn versus soy spread, I'm tracking weather, export reports, ethanol demand, and biodiesel policy. All of it matters.
When spreads don't work
They don't work when the historical relationship breaks down permanently. That sounds obvious but traders chase it constantly. Two commodities that have traded in a range for twenty years can decouple. I saw it with natural gas and electricity spreads in Texas during the winter storms a couple years back. The correlation went to zero and stayed there for months. Anyone who was short the spread thinking mean reversion was coming got crushed. Spreads also fail when liquidity dries up. The best spreads in the world are useless if you can't get in or out at a reasonable price. This happens most often in off-month futures contracts, emerging market pairs, and any spread involving products with narrow trading windows. And there's the tax complication in the US. Section 1256 contracts get sixty-forty treatment regardless of how long you hold them. Most spreads qualify, but not all. If you're trading certain commodity spreads inside a non-Section 1256 vehicle, the tax outcome can be worse than a simple long position. I always run the tax calculation before placing the trade. It takes about ten minutes and saves a lot of headaches at filing time.
If you're just starting out, equity pair trading is probably the gentlest entry point. You pick two stocks in the same industry, check their historical spread, and trade the divergence. Less regulatory complexity than futures, no expiration dates to manage, and plenty of data available. Once you understand the mechanics there, moving to commodity calendar spreads or bond spreads is a logical next step. The hardest part isn't finding a spread. It's knowing when to walk away from one. Spreads feel safer than single positions, so people hold them too long. They tell themselves the relationship will hold. Sometimes it does. Sometimes it doesn't. The ones who last are the ones who set a hard exit rule before they enter and stick to it regardless of how reasonable the original thesis seemed at the time.