What Is The New Deal — And Why It Still Shows Up in Unexpected Places
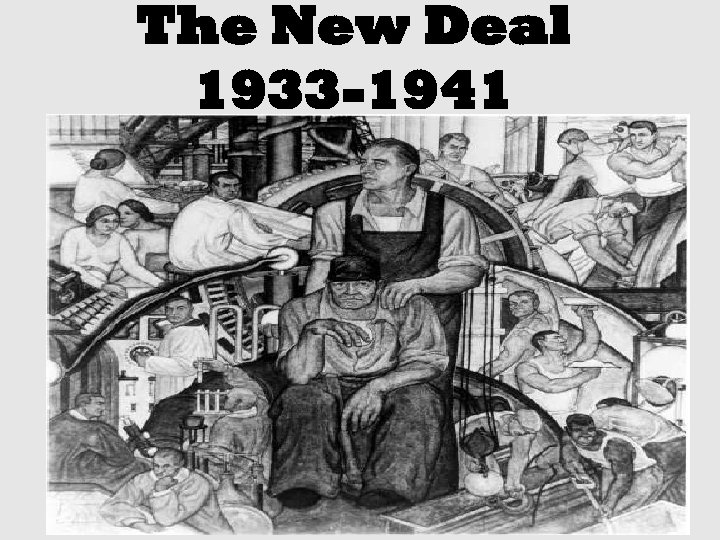
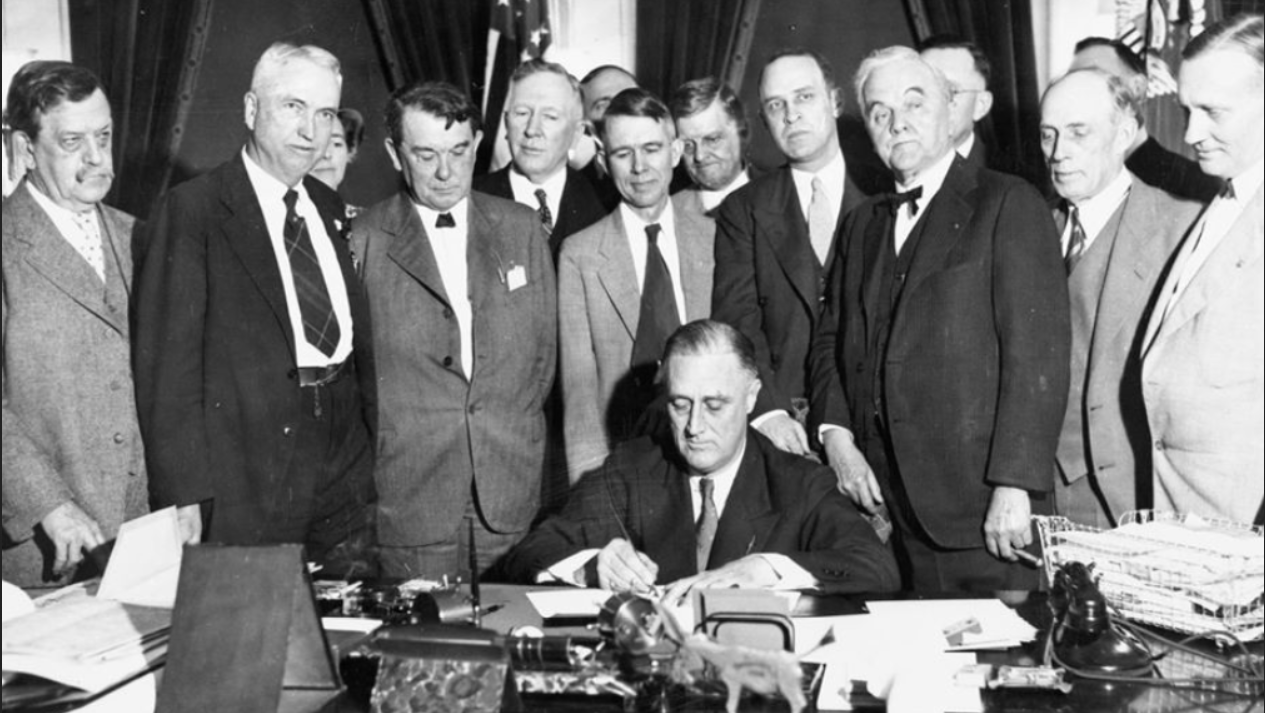
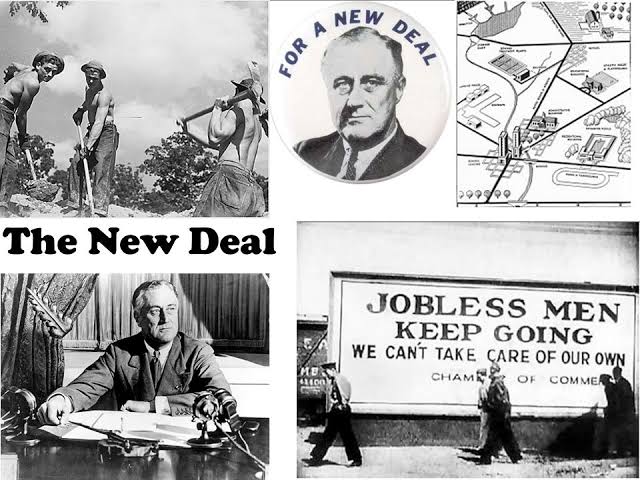
The New Deal was a series of domestic programs, public work projects, financial reforms, and regulations enacted by President Franklin D. Roosevelt in the United States between 1933 and 1939. It responded to the Great Depression, which had left roughly a quarter of the workforce unemployed and triggered widespread bank failures, agricultural collapse, and a near-total breakdown in consumer confidence. The name came from FDR's 1932 Democratic National Convention acceptance speech, where he said he was offering the American people "a new deal." What actually happened over those six years is more complicated than most textbooks let on. There weren't two neat phases — there was overlap, reversal, court-packing attempts, and programs that got gutted or rewritten mid-stream.
What Is The New Deal really structured around?
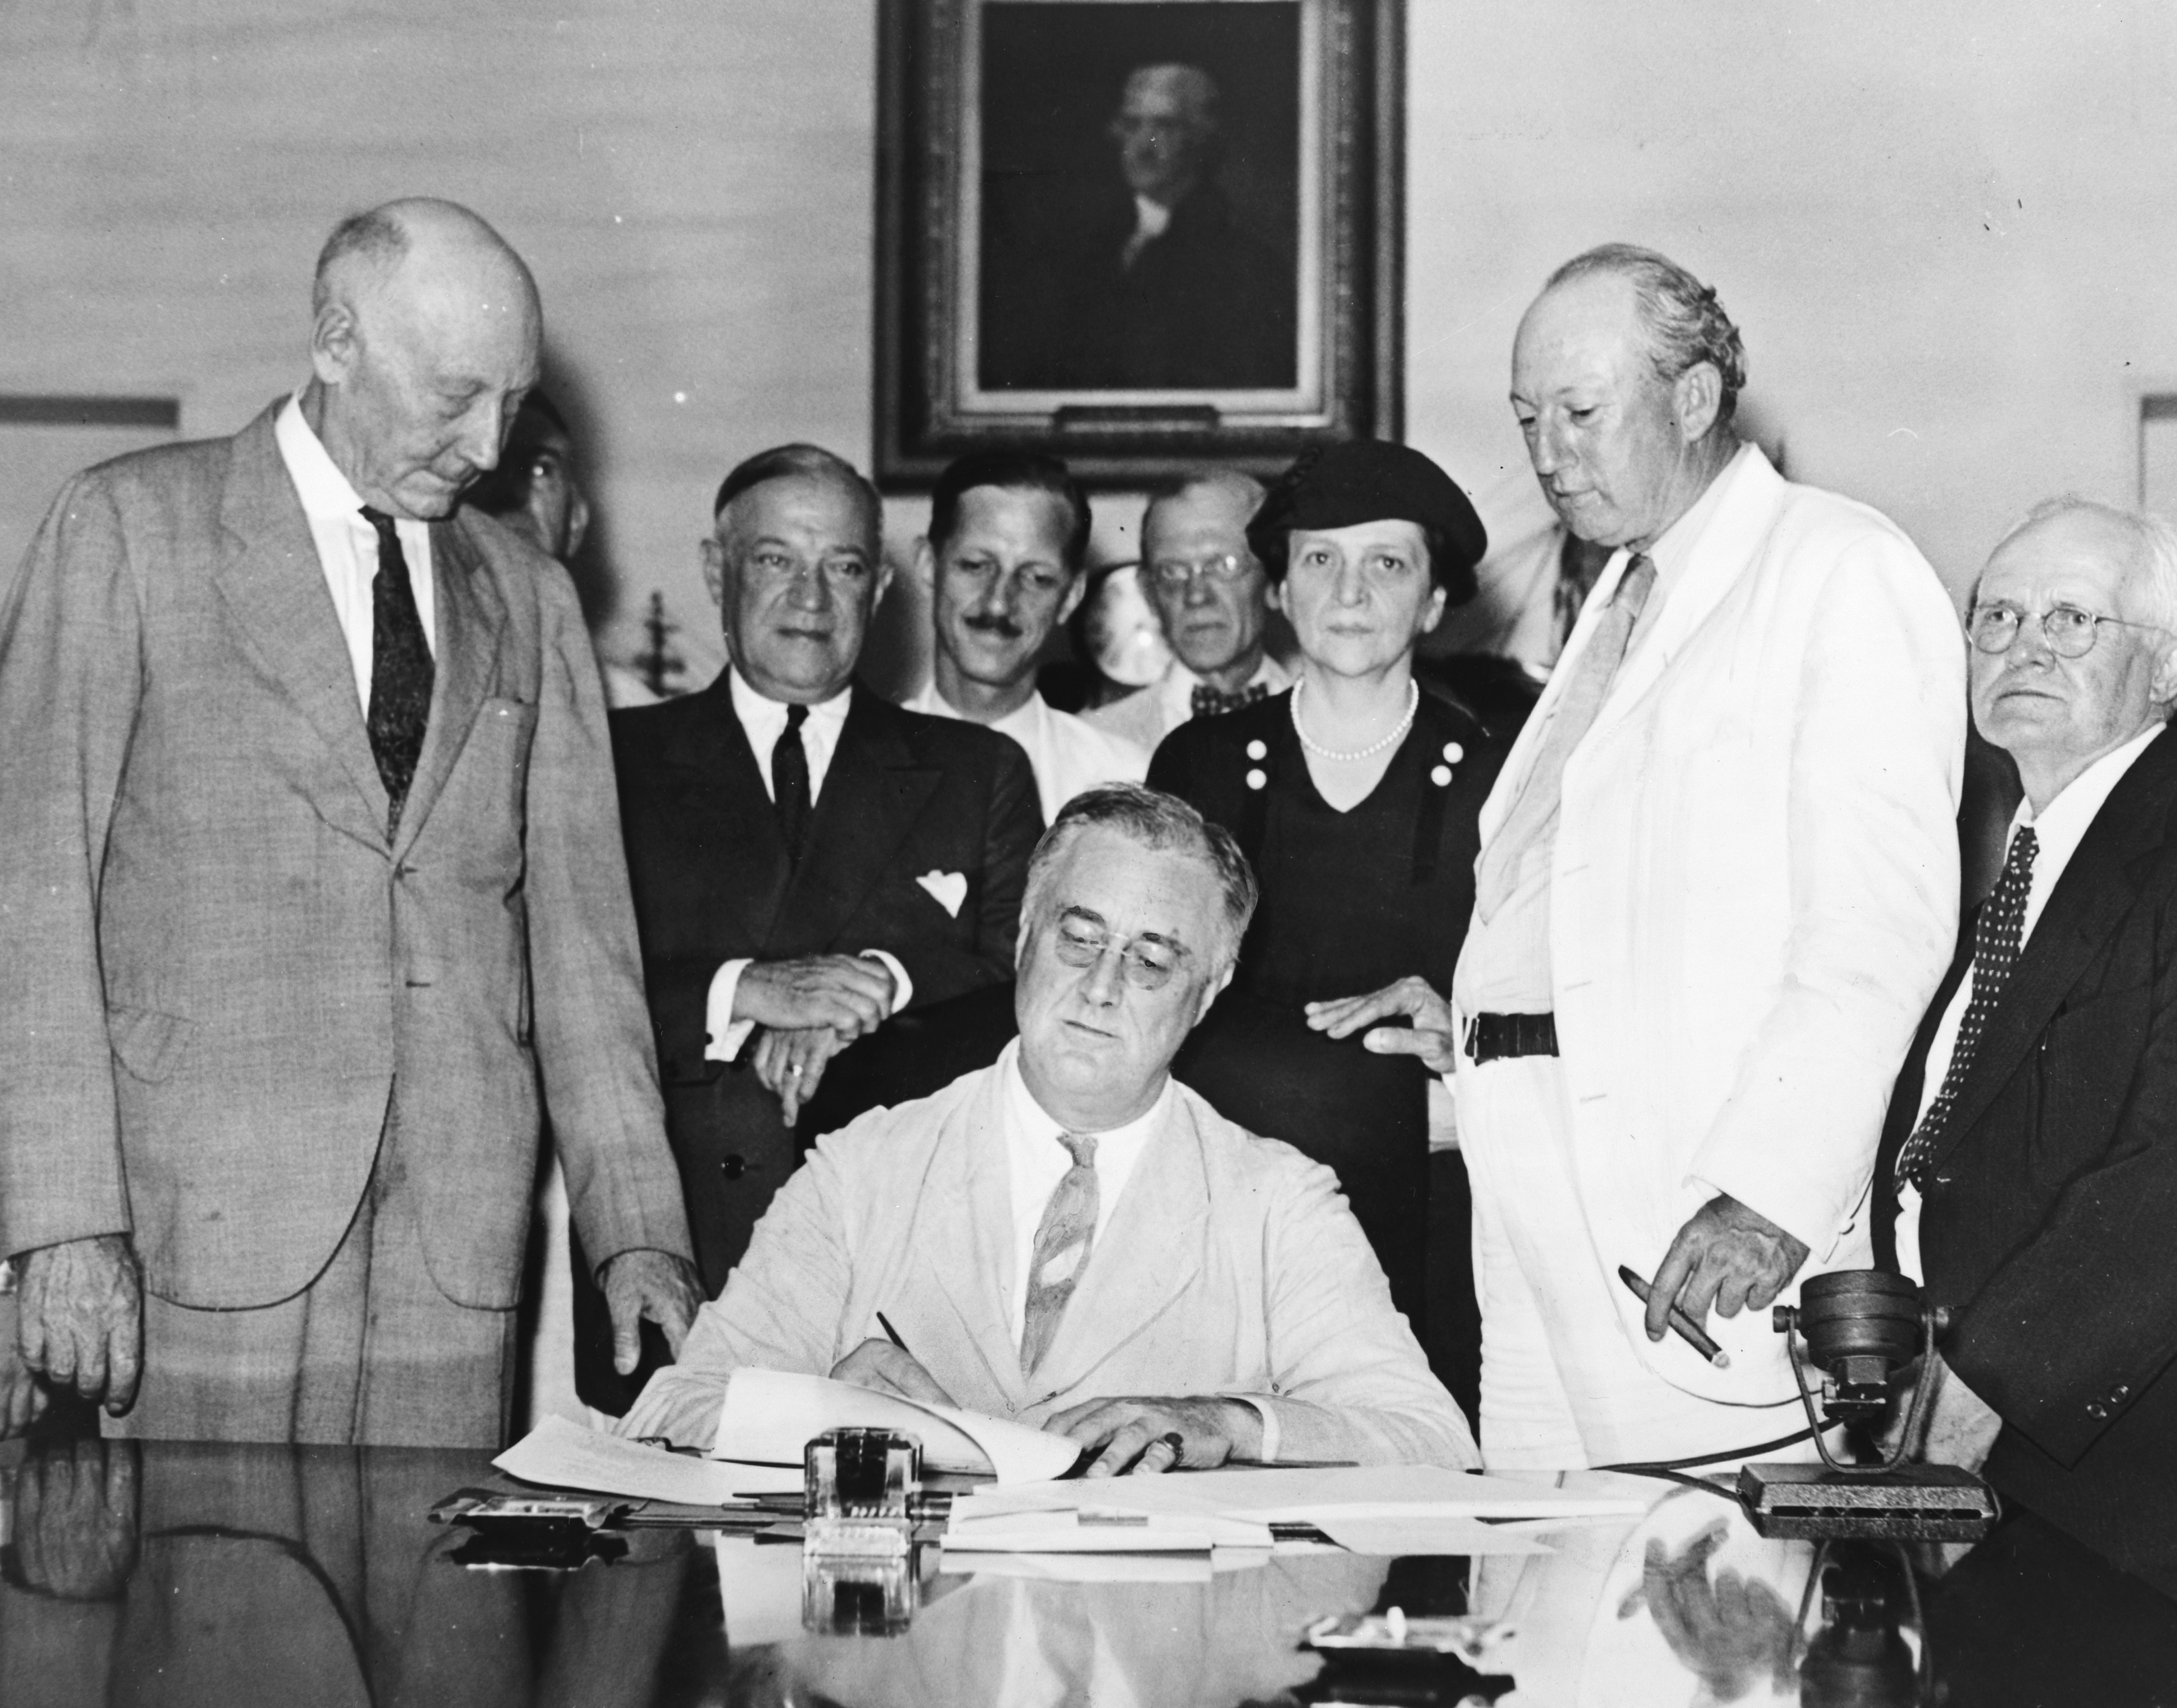
The initial burst of legislation in 1933, often called the First New Deal, was driven by an advisor circle known as the "Brain Trust" — mostly academics from Columbia and other universities who had zero experience running government agencies. Their ideas were ambitious but structurally naive. The Agricultural Adjustment Act (AAA) paid farmers to destroy crops and kill livestock to raise prices. That sounds absurd now, but it was the dominant economic thinking of the era — try to reverse deflation by creating artificial scarcity. Meanwhile, people were lining up for soup kitchens. The Second New Deal, starting in 1935, shifted toward more structural reform. The Social Security Act, the Wagner Act (which protected union organizing rights), and the establishment of the Securities and Exchange Commission were the heavy hitters here. These pieces had longer institutional legs, partly because they were designed to create enduring agencies rather than emergency fixes. I ran into this gap between legislative intent and actual administration firsthand when I was researching federal payroll data from the 1930s. The WPA (Works Progress Administration) is usually cited as having employed around 8.5 million people at its peak. That number is technically accurate but misleading. A single WPA worker could be counted on the rolls for multiple projects simultaneously depending on which bureau's reporting system you pulled from. The duplication rate across CCC, WPA, and FERA records was roughly 18 to 22 percent. If you're cross-referencing New Deal employment data against Treasury expenditure records, you need to normalize for that overlap or your totals will be off by millions. The National Archives actually has a guide for this — Document 27 from the Bureau of the Census — that nobody seems to read before they start citing WPA employment figures.
The mechanisms that actually moved the needle
Here's the thing most casual explanations skip: the New Deal wasn't primarily about getting people back to work in the way we think of stimulus programs today. A lot of it was about stabilizing the financial and agricultural systems so they wouldn't completely collapse. The Emergency Banking Act of 1933, for instance, was passed on FDR's third day in office. It closed all banks for a week, allowed only solvent ones to reopen under federal inspection, and restored public confidence in the banking system. That alone stopped the panic runs that had been accelerating every week since March 1933. The Federal Deposit Insurance Corporation (FDIC), created in 1933, wasn't about helping the poor. It was about preventing bank runs by guaranteeing deposits up to $2,500 per account. In practice, this was revolutionary because it made the difference between a bank failure causing cascading losses for everyday people versus a contained institutional event. The banking holiday and subsequent FDIC creation probably prevented another year of the sort of depositor panic that had already wiped out over 4,000 banks by early 1933. The Tennessee Valley Authority (TVA) is still the clearest example of New Deal thinking at its most ambitious. It wasn't just a public works project — it was a federally owned corporation designed to manage an entire river basin: flooding control, electricity generation, fertilizer production, navigation, and regional economic development, all under one agency. It was structurally closer to a European nationalized industry model than anything the US had tried before. Today it's the largest public power provider in the country, and it still operates independently as a government-owned entity. That longevity is unusual for New Deal programs, most of which were either terminated, scaled back, or absorbed into other agencies.
Get the Full Details
Where the New Deal fell short — and where it broke
The New Deal did not end the Great Depression. That's the most important fact people forget. GDP was still below its 1929 peak in 1939. Unemployment remained above 14 percent. The recession of 1937 — triggered partly by FDR's own decision to cut spending and tighten monetary policy — caused industrial output to drop sharply and unemployment to spike back toward 19 percent. The military buildup after 1938 is what actually closed the gap and drove unemployment below 5 percent by 1941. Several New Deal programs actively harmed the populations they claimed to help. The AAA's payment system was administered locally, which meant Southern county committees — overwhelmingly white — directed benefits away from Black sharecroppers and tenant farmers. When landowners took animals out of production and received government checks, they frequently evicted the families who worked those lands. The Social Security Act initially excluded agricultural and domestic workers, categories that employed a disproportionate number of Black Americans. That exclusion wasn't an oversight — it was a political compromise with Southern Democrats to get the bill passed. It stayed in place until amendments in 1950 began covering those sectors. The National Recovery Administration (NRA), created in 1933, is another program that deserves a straightforward critique. It attempted to set industry-wide codes for wages, prices, and working conditions. In practice, it often locked in prices at levels that favored large corporations over small businesses and consumers. The Supreme Court struck it down in Schechter Poultry Corp. v. United States (1935), ruling that it delegated too much legislative authority to private trade associations and that Congress had overreached into intrastate commerce. The legal reasoning was sound — the decision was essentially about constitutional structure, not policy merit. But the ruling killed one of the New Deal's most aggressive interventionist programs in one afternoon.
How to think about the New Deal's actual legacy
The lasting structural changes are fairly clear and somewhat mundane. Social Security still exists. The SEC regulates securities markets. The FDIC insures deposits. The Federal Housing Administration (FHA), created in 1934, standardized mortgage lending and made homeownership accessible to white working-class families — and systematically redlined Black neighborhoods, which is a separate and well-documented problem. The National Labor Relations Board (NLRB) still handles union elections and unfair labor practice charges. These aren't historical artifacts. They're active institutions that shape how American economic life works. What the New Deal didn't do — and what it's frequently credited with doing incorrectly — is create a permanent expanded role for government in managing the economy through Keynesian demand stimulation. FDR was actually hostile to deficit spending for most of his presidency. He balanced the budget in 1937 (during a recession, which was a mistake). The New Deal's intellectual lineage is better traced to institutional reform and regulatory state-building than to macroeconomic management. That shift happened later, largely through the influence of Keynesian economics on Truman and Eisenhower advisors, and then permanently under Kennedy and Johnson. If you want a practical entry point into understanding the New Deal beyond the usual summaries, the best primary source is FDR's own Fireside Chats. They're 20 minutes long, recorded on radio, and remarkably direct for their time. The third one, "On the Banking Crisis" from March 12, 1933 — just four days after he took office — explains the banking holiday in language that any modern reader can follow. It's also the clearest demonstration of how presidential communication shifted from something distant and formal into something intimate and personal. That communication strategy mattered as much as any policy in restoring public trust during those early months.