Understanding Antitrust Law
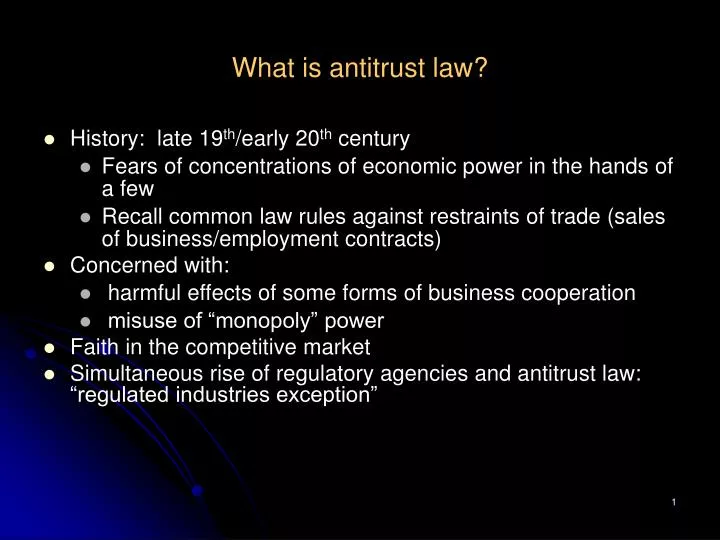
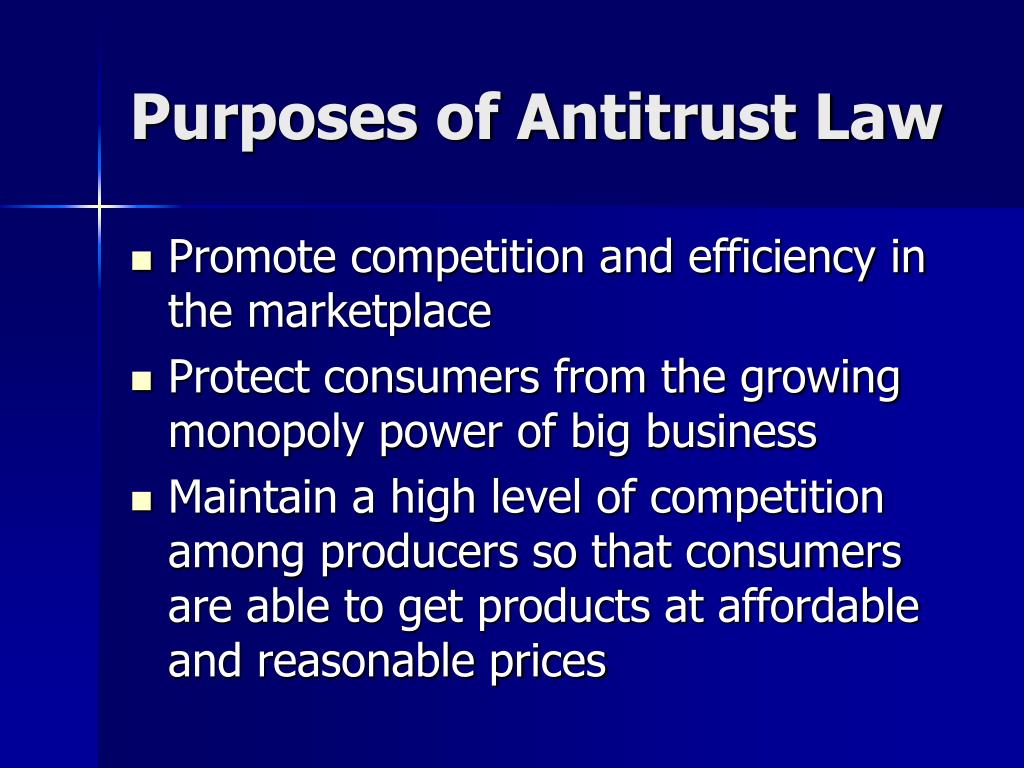
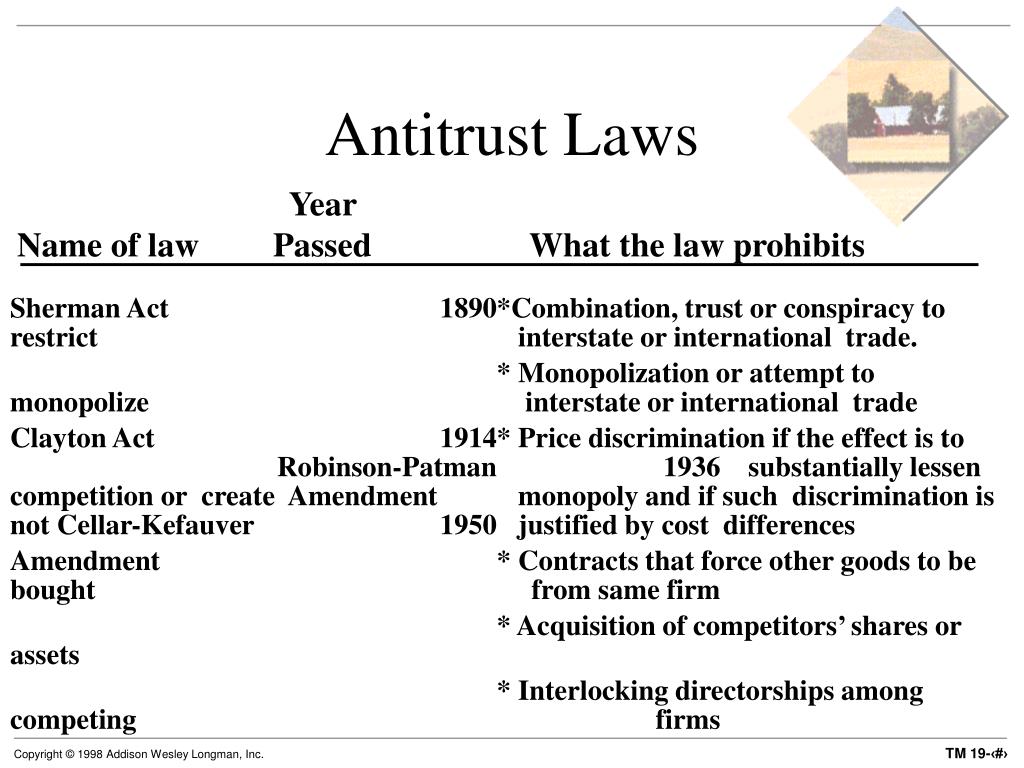
Antitrust law exists because markets don't regulate themselves properly. When a few companies control enough of a sector, they stop competing and start extracting value from everyone else. The law intervenes to keep competition alive, whether that means breaking up monopolies, blocking mergers, or prosecuting price-fixing schemes. At its core, antitrust law protects consumers by ensuring markets remain competitive. It targets three main problems: monopolies that eliminate rivals, cartels that coordinate pricing between competitors, and mergers that would concentrate too much market power in one entity. The primary goal is maintaining conditions where multiple companies can realistically compete, which keeps prices down and innovation moving. The Sherman Act of 1890 was the first major US federal legislation addressing this. Standard Oil and AT&T are textbook examples of what happens when the law doesn't catch problems fast enough. Both became so dominant that they effectively controlled entire industries. Breaking them up took years of litigation and reshaped how regulators approach enforcement today.
There's a practical reality most people miss about antitrust enforcement. It doesn't punish companies for being big. Being a monopoly isn't illegal unless you acquire or maintain that position through anti-competitive conduct. Microsoft faced antitrust scrutiny in the late 1990s not because Windows had market share, but because it bundled Internet Explorer with the operating system in ways that made rival browsers structurally disadvantaged. The case settled with behavioral remedies rather than a breakup. That's the modern approach. Merger review is where antitrust work happens most frequently now. The FTC and DOJ evaluate proposed acquisitions before they close. They look at whether the combined entity would have the power to raise prices or reduce output. The relevant market definition is everything here. Narrow it too much and any merger looks harmless. Make it too broad and you miss real competitive harm. I dealt with a case involving a regional healthcare network acquiring a smaller provider. On paper, the combined market share looked manageable. But when you factored in referral patterns and insurance network positioning, the acquisition would have effectively blocked competitors from accessing key provider relationships. We redefined the relevant geographic market based on where patients actually traveled for specialized care rather than just zip code boundaries. The merger got blocked on that basis.
Here's something counter-intuitive about antitrust that trips up a lot of people: consumer welfare isn't the only standard. Price matters, but so does quality, choice, and innovation. Some analysts argue the current consumer welfare standard is too narrow because it focuses heavily on price effects. If a company can offer free products funded by ad revenue, traditional price-based analysis doesn't capture the harm. Platform economics complicate this further. Network effects mean that the most popular service becomes more valuable simply because more people use it. That's not anti-competitive behavior in the traditional sense. It's a natural market dynamic that can still produce monopolistic outcomes. Regulators are still working through how to handle this. The EU's Digital Markets Act takes a different approach by designating large platforms as gatekeepers and imposing specific obligations rather than relying solely on after-the-fact enforcement. There's a significant limitation to antitrust enforcement that people rarely discuss. It's slow and expensive. Litigation can take years. By the time a case resolves, the market may have already shifted entirely. Tech companies often move faster than regulatory processes can respond. This creates a window where anti-competitive behavior can entrench itself before regulators even begin their investigation.
Get the Full Details

Another practical issue is the evidence problem. Modern anti-competitive strategies are rarely documented explicitly. Companies don't write memos saying they're trying to monopolize a market. They structure contracts, pricing, and partnerships in ways that achieve similar outcomes while appearing legitimate. Proving intent requires digging through internal communications and business decisions, which is time-consuming and uncertain. There's also a question about whether antitrust is the right tool for every situation. Some industries naturally consolidate due to high fixed costs or economies of scale. Airlines, utilities, and telecommunications face this constantly. Force competition where it can't viably exist and you end up with subsidizing losses or service degradation. Regulators sometimes prefer sector-specific oversight over general antitrust enforcement for these cases. The Clayton Act of 1914 filled gaps the Sherman Act left open. It specifically targeted exclusive dealing arrangements, tying agreements, and interlocking directorates. The Robinson-Patman Act of 1936 addressed price discrimination. Together these statutes form a framework that's now over a century old, applied to industries the original drafters couldn't have imagined.
If you're researching a specific case or industry, start with the FTC and DOJ merger guidelines. They outline the analytical framework regulators use. Market share thresholds give a rough initial filter, but they're not definitive. The horizontal merger guidelines describe how the agencies evaluate competitive effects including unilateral and coordinated interaction concerns. One thing worth noting is the growing international dimension. Antitrust enforcement increasingly involves multiple jurisdictions. A single merger might require approval from the EU, the US, China, and several other countries. Each jurisdiction has different standards and timelines. Companies planning cross-border transactions need to factor in compliance across all relevant regimes, not just their home country's rules. The European Commission has been more aggressive than US regulators in recent years. Google received three separate fines totaling over five billion euros for different anti-competitive practices. Amazon faced a formal investigation into its marketplace practices. The US has been more cautious, partly due to differing interpretations of consumer welfare and partly due to resource constraints at enforcement agencies.
For businesses operating in regulated sectors, the practical takeaway is that compliance matters more than ever. Mergers and acquisitions need careful pre-closing antitrust analysis. Pricing strategies should avoid anything that could be interpreted as coordination with competitors. Exclusive contracts and loyalty programs warrant review when market share reaches significant levels. The cost of prevention is always less than the cost of defense. Antitrust law isn't perfect. It operates reactively, moves slowly, and faces genuine difficulty keeping pace with market evolution. But it remains the primary mechanism for addressing concentrated market power. Without it, there's no systematic check on companies that grow large enough to dictate terms to everyone else.