Figuring Out Your Mortgage Eligibility
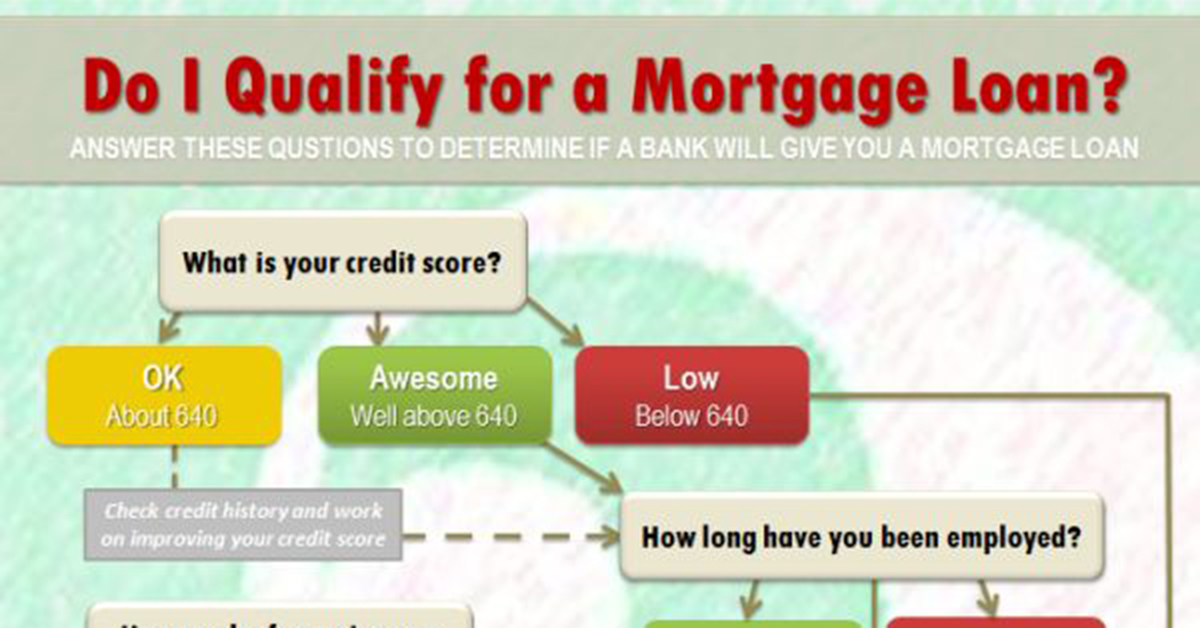
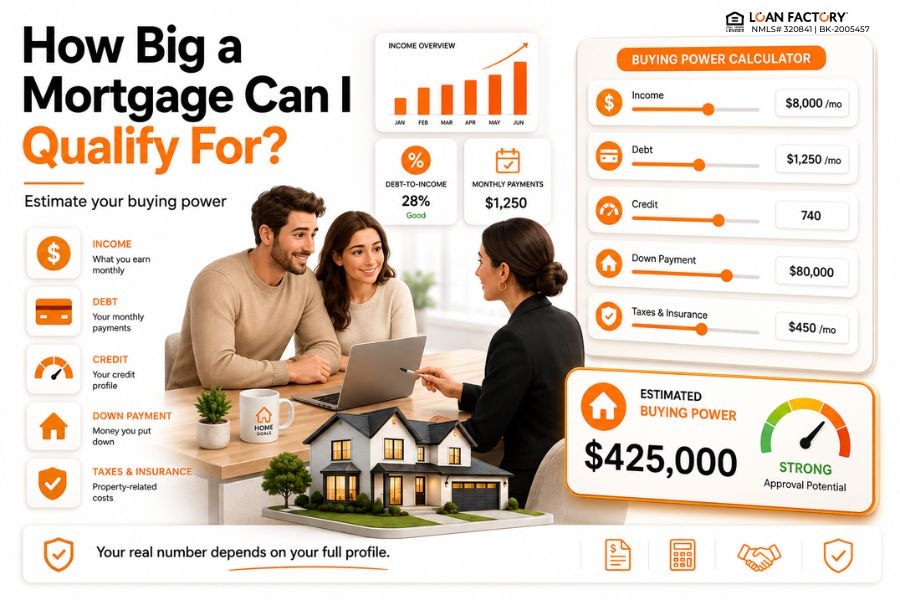
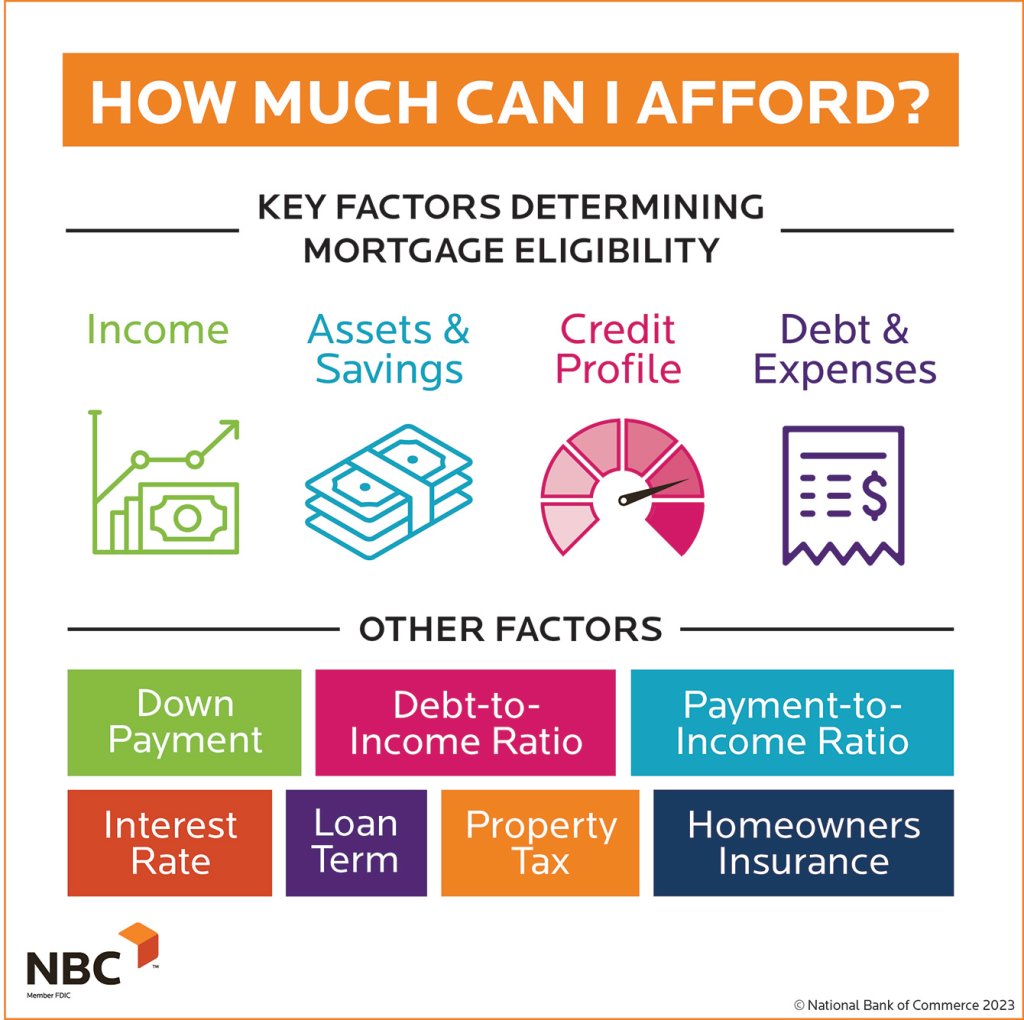
Mortgage qualification comes down to a handful of numbers that lenders weigh against each other, and they do not give a damn about your dreams. The standard framework revolves around credit score, debt-to-income ratio, available down payment, and employment history. Every lender has slightly different thresholds, but the underlying math is essentially the same across the board. You run the numbers yourself first, then approach lenders with a realistic picture instead of a hopeful guess. Most conventional loans require a minimum credit score of 620, though you will get meaningful rate improvements at 740 and above. Federal Housing Administration loans dip down to 580 with a three and a half percent down payment, or 500 with a ten percent down payment if your credit profile is otherwise solid. Veterans Affairs loans have no hard minimum score in most cases, but individual lenders impose their own floors, usually around 580 to 620. Your debt-to-income ratio is where a lot of people get tripped up. Lenders prefer to see it below forty-three percent, and some conventional programs push the limit to fifty percent with strong compensating factors. DTI includes everything: car payments, student loans, credit card minimums, child support, the works. Divide your total monthly debt obligations by your gross monthly income and you have your number. I had a borrower once who had a $42,000 student loan with an income-driven repayment plan showing a monthly obligation of twenty dollars. The lender used that twenty dollars in the DTI calculation instead of the full projected payment, and it saved the deal. If your student loans are in an IDR plan, make sure you ask the lender to use the lower actual payment amount for DTI purposes. Most will do it, but not all, and the difference can be thousands of dollars in qualifying power.
Down payment requirements vary dramatically by loan type. Conventional loans can go as low as three percent for first-time buyer programs, but putting less than twenty percent triggers private mortgage insurance, which adds five to one percent to your annual cost until you reach twenty percent equity. FHA requires three and a half percent but bundles mortgage insurance into the loan for the life of the loan if you put less than ten percent down. That is a critical distinction. PMI can be dropped once you hit twenty percent equity. FHA upfront and annual MIP stays whether you want it to or not. This means a four percent down payment on an FHA loan can actually cost more over five years than a six percent down payment on a conventional loan because of the insurance premium structure. Employment history matters more than people realize. Two years of consistent employment in the same field is the standard requirement. Gap between jobs, self-employment income, or commission-heavy compensation can complicate things significantly. Self-employed borrowers need two years of complete tax returns, and lenders will often use the lower of the two years if income has fluctuated. I worked with a client whose income spiked in one year due to a contract bonus and dropped the following year. The lender used the lower year, which knocked his qualifying amount down by nearly eighty thousand dollars. He ended up switching to an asset depletion program where they looked at his liquid assets divided by thirty-six instead of his income, and that got him qualified for the home he wanted. It is a niche workaround, but it exists and saves deals that would otherwise fall apart. Asset reserves are another hidden requirement that catches people off guard. Many lenders want to see two to six months of mortgage payments in reserve after closing. This means cash left over after you pay the down payment, closing costs, and any required reserves. If you have been liquidating retirement accounts to fund a down payment, you may not have enough reserves left to qualify. Some lenders will count gifted funds toward reserves, but not all, and gifted funds usually cannot come from a party with an interest in the transaction. Money from your spouse or parents is generally fine. Money from your future employer or investment group is not.
There are practical strategies people miss. Getting pre-approved before you shop is not the same as being pre-qualified. Pre-approval means a lender has pulled your credit, verified your income and assets, and given you a specific dollar amount. Pre-qualification is a loose estimate based on information you provided without verification. When you make an offer on a house, sellers care about pre-approval letters, not pre-qualification guesses. Also, do not open new credit accounts or make large purchases on credit during the application process. A hard inquiry can drop your score by five to ten points, and a new auto loan or credit card balance can push your DTI over the edge before you even submit the application. The biggest bottleneck in this process is timing. Lenders require fresh documentation. Your pay stubs, bank statements, and employment verification expire. If your approval takes longer than sixty days, you will likely need to resubmit everything. I have seen deals fall apart because a buyer waited too long between pre-approval and making an offer, and by the time they were ready, their documentation had expired and their financial situation had shifted. Lock your rate early, move quickly once you find a property, and keep your financial life unchanged from application to closing. Any deviation—a new job, a large deposit, a missed payment—will trigger additional review and delay closing or kill the loan entirely. If your DTI is too high and you cannot reduce it through debt payoff, look into nonQM loan products. These are portfolio loans that do not follow the strict DTI rules of conventional or government-backed programs. They usually carry higher interest rates and require larger down payments, but they accommodate self-employed borrowers, investors, and people with complex income situations that standard lenders cannot process. Not every broker carries these products, so you may need to seek out a specialist lender if conventional routes are blocked.
Get the Full Details

Run your own numbers first using a reliable mortgage calculator. Input your actual credit score range, your total monthly debts, your gross income, and your available down payment funds. Compare conventional, FHA, and VA options side by side including the ongoing cost of mortgage insurance. The cheapest monthly payment is not always the cheapest overall cost. A higher rate with PMI might cost more in the long run than a slightly lower rate with a larger down payment that avoids insurance entirely. Do the math on the total cost over five years, not just the payment amount.