What Limits Actually Do For You
Limits are the operating system of calculus. Without them you have arithmetic; with them you get derivatives, integrals, and everything sandwiched between. Most textbooks introduce limits as a formal prerequisite before moving on to differentiation, which is technically correct but misses the point. Limits matter because they solve real problems you hit when working with continuous quantities—problems that algebra alone cannot handle. I remember grading a mid-term where three students wrote that the derivative of x^2 at x = 3 was 6 because (3+h)^2 - 9 / h simplifies to 6. When I asked what happened to h, one student said it just disappears. It doesn't disappear. You evaluate the limit as h approaches zero, and that's the entire mechanism. The simplification step is just algebraic cleanup; the limit is what gives the result meaning. That confusion shows up everywhere, not just in intro courses.Why Are Limits Important In Calculus
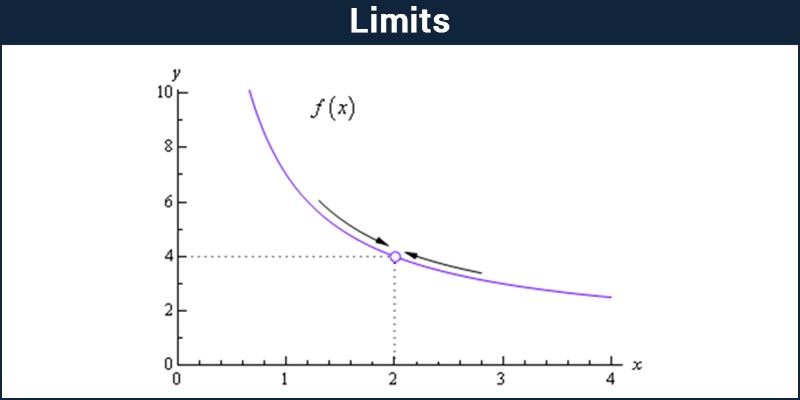
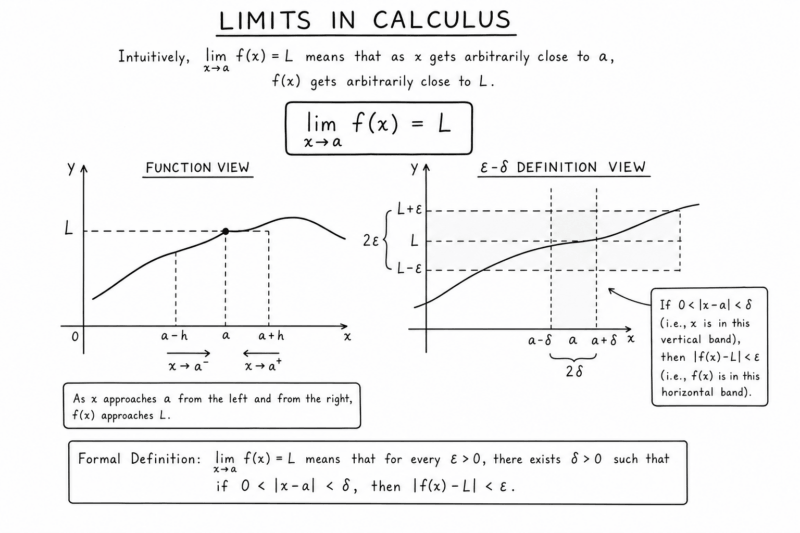
The short answer is that limits let you talk about instantaneous change. Velocity at a single moment, slope at a single point, area under a curve—none of these exist as finite differences. They exist as values that quantities approach. A limit captures that approach without requiring you to actually reach it, which is the only way to define something like an instantaneous rate of change. Consider the average rate of change over an interval. You divide a finite difference by a finite time span. Make that span smaller, and your approximation gets better. But you never get the exact value unless you take the limit as the span goes to zero. That limit is the derivative. Skip the limit, skip the derivative. Same logic applies to Riemann sums and the definite integral. You approximate area with rectangles, then take the limit as the number of rectangles goes to infinity. The limit is what turns an estimate into an exact value. Here is a practical example that comes up constantly. The function f(x) = sin(x)/x is undefined at x = 0. Direct substitution gives 0/0, which is meaningless. But the limit as x approaches 0 equals 1. That limit lets you assign a value at the undefined point and make the function continuous. Engineers do this kind of thing all the time when modeling physical systems that have singularities in their equations. The epsilon-delta definition exists because limits need precision. Saying "gets closer and closer" is intuitive but insufficient for proof. Epsilon-delta makes it rigorous: for every epsilon greater than zero, there exists a delta greater than zero such that if the distance between x and c is less than delta, then the distance between f(x) and L is less than epsilon. This definition handles cases where intuition fails, like functions that oscillate infinitely near a point or have jump discontinuities.Common Pitfalls
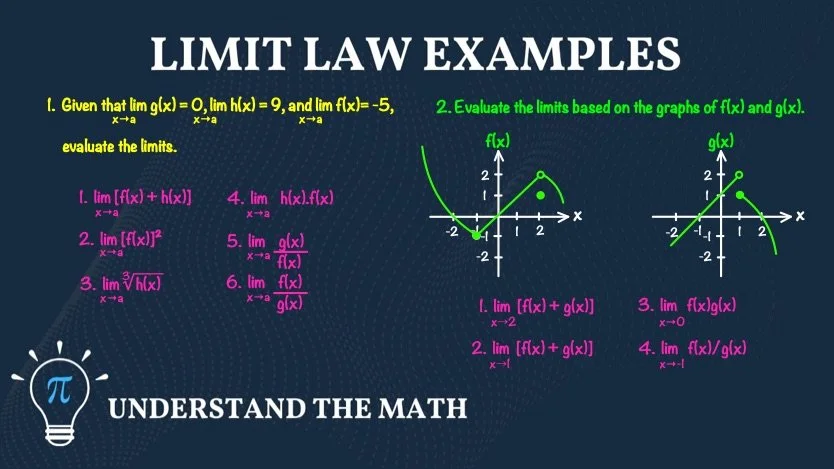
Students routinely plug in the target value instead of evaluating the limit. If f(x) = (x^2 - 4)/(x - 2), plugging in x = 2 gives 0/0. The limit as x approaches 2 is 4, found by factoring the numerator to (x-2)(x+2) and canceling the common factor. The function itself is still undefined at x = 2. Confusing the limit with the function value is a mistake that shows up in integration techniques and series expansions too. Another frequent error is assuming limits always exist. They do not. The function g(x) = 1/x has no limit as x approaches 0 because the left-hand limit is negative infinity and the right-hand limit is positive infinity. These one-sided limits disagree, so the two-sided limit does not exist. Writing lim x0 1/x = is sloppy notation at best and wrong at worst. The proper statement is that the limit does not exist, though the one-sided limits can be described separately. One-sided limits matter more than people realize. Consider h(x) = |x|/x. The right-hand limit as x approaches 0 is 1. The left-hand limit is -1. The function has a jump discontinuity at 0, and the two-sided limit does not exist. This distinction is critical when working with piecewise functions, Fourier series convergence, and signal processing applications.A Limitation Worth Noting
Get the Full Details
How Limits Connect to Everything Else
Continuity depends on limits. A function is continuous at c if the limit as x approaches c equals f(c). Discontinuous functions break many theorems. The Intermediate Value Theorem requires continuity on a closed interval. The Extreme Value Theorem requires continuity on a compact set. Without limits, you cannot define continuity, and without continuity, calculus theorems lose their guarantees. Differentiability implies continuity but not vice versa. The absolute value function is continuous everywhere but not differentiable at 0 because the left and right derivatives differ. This non-differentiable point exists precisely because the limit defining the derivative does not converge to a single value from both sides. Understanding this relationship helps when analyzing optimization problems and numerical stability. The Fundamental Theorem of Calculus links limits, derivatives, and integrals in one statement. If f is continuous on [a,b] and F is an antiderivative of f, then the definite integral from a to b of f(x)dx equals F(b) - F(a). The definite integral is defined as a limit of Riemann sums. The antiderivative exists because of continuity, which is itself defined through limits. Everything traces back.Practical Application
In physics, limits define instantaneous velocity and acceleration. The position function s(t) gives average velocity over [t, t+h] as (s(t+h)-s(t))/h. The derivative s'(t) is the limit of this expression as h approaches 0. This limit exists for smooth motion but fails at points where the trajectory has corners or discontinuities, like a ball bouncing off the ground. At those points, the velocity is undefined, and the limit does not exist. In economics, marginal cost is the derivative of the cost function, defined through a limit. Marginal revenue works the same way. These concepts guide pricing decisions and production levels. The limit interpretation ensures you are measuring the rate of change at a specific quantity level, not over a range. In computer graphics, limits appear in rendering algorithms. Ray tracing uses limit processes to approximate how light behaves at surfaces. Gradient-based optimization in machine learning relies on derivatives defined through limits. Even loss function minimization traces back to the same concept.Advanced Insight
The Heine definition of limits uses sequences instead of neighborhoods. A limit of f(x) as x approaches c equals L if and only if for every sequence x_n converging to c (with x_n c), the sequence f(x_n) converges to L. This equivalence is useful for proving non-existence of limits. If you can find two sequences approaching c that produce different limiting values for f, the limit does not exist. The sequence approach also generalizes more easily to metric spaces and topological contexts where epsilon-delta notation becomes cumbersome. Improper integrals extend the concept of limits to infinite intervals and unbounded functions. The integral from 0 to infinity of e^(-x)dx is defined as the limit as b approaches infinity of the integral from 0 to b of e^(-x)dx. This limit equals 1. Without the limit framework, you could not assign a finite value to an integral over an infinite domain.When Limits Fail