How Mortgage Calculators Actually Work for Wisconsin Borrowers
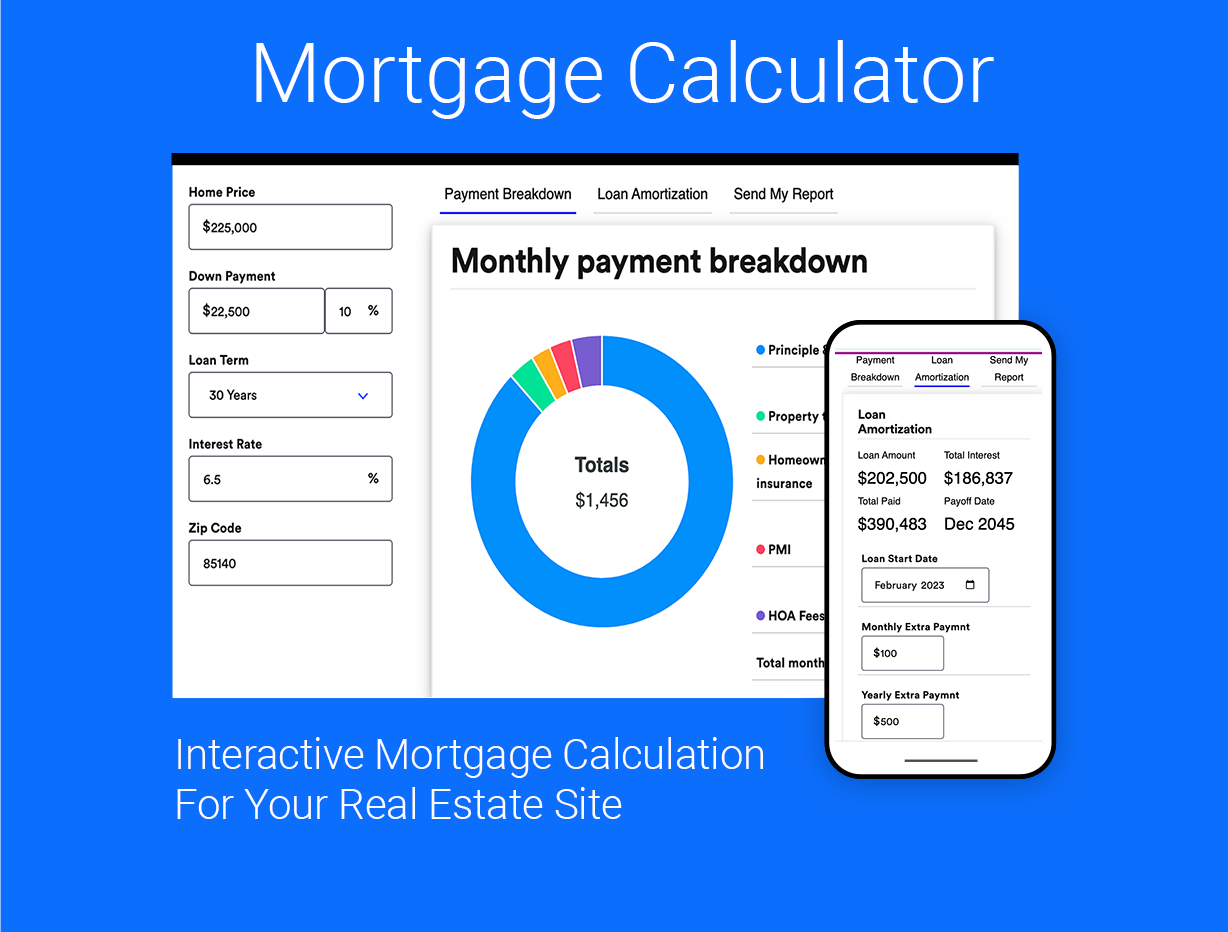
Most people treat mortgage calculators like magic boxes where you punch in numbers and get back a single monthly payment. That is not what they do. A mortgage calculator breaks your loan into its component parts and shows you how each piece contributes to the total. The base payment covers principal and interest. Then you add property taxes, homeowners insurance, and sometimes private mortgage insurance or HOA fees. Wisconsin does a few things differently from most states, so using a generic national calculator will often give you a number that is $50 to $150 too low on the final result. I worked through a file last month where the borrower was comparing quotes from three lenders. The calculator on lender A's website showed $1,847 per month. Lender B's showed $1,923. Lender C was at $1,798. The actual difference between the three was less than forty dollars. The calculators were giving wildly different answers because each one made a different assumption about how to handle the property tax line. That is the kind of thing that happens when you pick a calculator that was built in another state and never adjusted for Wisconsin's high property tax counties.
How to Use a Wisconsin Mortgage Calculator
Start by gathering the three numbers you absolutely need before you open any tool. The loan amount, which is the purchase price minus your down payment. The interest rate the lender has quoted you, stated as an annual percentage rate. And the loan term, which is usually 30 years or 15 years for conventional loans. After those three, you need your property tax figure. This is where most people make a mistake. Do not estimate this from memory. Pull the most recent property tax bill for the home you are buying, or ask the seller's agent for the prior year's statement. Wisconsin properties are assessed annually, and the tax amount can vary significantly even between two homes on the same street. Enter the loan amount into the calculator first. Then the interest rate. Then the term. The calculator will compute your principal and interest payment using the standard amortization formula. After that, take the annual property tax and divide it by 12 to get the monthly portion. Do the same with your annual homeowners insurance premium. If your down payment is less than 20 percent, the calculator should add PMI automatically, but verify this before you trust the output. Some online calculators omit PMI entirely unless you specifically toggle it on. In Wisconsin, there is a quirk with property tax calculations that trips up even experienced agents. The state uses fiscal years that do not always align with calendar years, and many municipalities levy special assessments for things like sewer upgrades or road improvements that appear on the tax bill but never show up in Zillow's estimated tax field. I had a borrower who used a popular free calculator that pulled estimated taxes from a public database. The number it returned was $240 per month. The actual tax bill was $412 per month because the property had a special assessment that had not yet been fully disbursed in the county records. The calculator missed it by over $2,000 a year. The workaround was simple: I stopped using any calculator that relied on automated tax estimates and switched to having the borrower provide the actual prior year tax statement from the county auditor's office. That changed the accuracy of the calculation immediately.
What the Numbers Mean When You Read Them
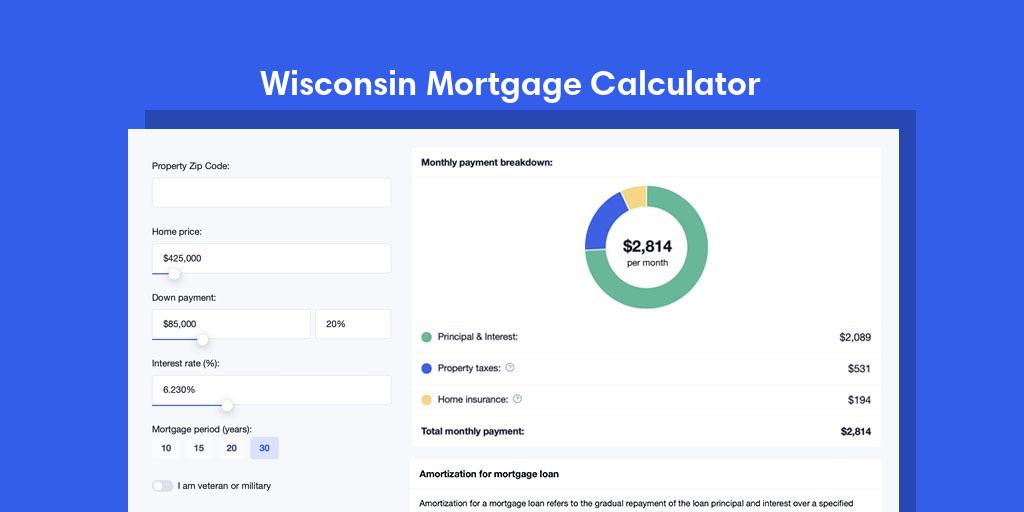
When you see a monthly payment of $2,100 from a calculator, that number is usually broken down into four pieces. Principal and interest make up the largest share and goes directly toward paying down the loan balance over time. Property taxes are held in an escrow account by the lender and paid to the county once or twice a year depending on your municipality. Homeowners insurance goes into the same escrow account and is paid to your insurer annually. Private mortgage insurance, if applicable, is a separate monthly charge that protects the lender, not you, and drops off once your loan balance reaches 80 percent of the home's original value. The debt-to-income ratio is another number you should understand before you submit an application. Lenders in Wisconsin generally want to see a front-end ratio below 28 percent, meaning your total housing payment should not exceed 28 percent of your gross monthly income. The back-end ratio, which includes car payments, student loans, credit cards, and all other debt, typically needs to stay under 36 percent, though some programs allow up to 43 percent. A calculator will not tell you your DTI unless you enter your total monthly debt obligations. Most people skip that step and then get confused when their application gets flagged during underwriting. Here is something most calculators do not warn you about. The interest rate you see advertised is rarely the rate you actually close with. Lenders offer rate credits, sometimes called lender credits, where they lower your interest rate in exchange for you paying higher closing costs. A $300,000 loan at 6.75 percent with a 1 percent credit might drop you to 6.25 percent, but you would pay roughly $3,000 extra in fees at closing. Whether that is worth it depends on how long you plan to keep the loan. If you move or refinance within three years, the higher closing cost eats any monthly savings you gained from the lower rate. If you stay five years or more, the lower payment compounds into real money. A good Wisconsin Mortgage Calculator will let you compare both scenarios side by side, but most free online tools do not have this feature built in.
Get the Full Details
Wisconsin-specific factors that change your payment Property taxes in Wisconsin rank among the highest in the nation. The state average effective property tax rate sits around 1.85 percent of assessed value, which is well above the national average of roughly 1.07 percent. In counties like Racine, Kenosha, and Milwaukee, the rates can push higher. If you are buying a $350,000 home in a high-tax county, your annual property tax could be $6,500 or more. That adds nearly $540 per month to your payment compared to a low-tax area. This is not a small detail. It is the single biggest variable that separates a calculator number from reality in Wisconsin. Another Wisconsin nuance is the homestead exemption. If you intend to occupy the property as your primary residence, you may qualify for a reduction in the assessed value of your home, which lowers your property tax bill. The standard exemption reduces the taxable value by $15,000. There are additional exemptions for veterans, seniors, and disabled persons that can reduce it further. A calculator that does not account for the homestead exemption will overstate your monthly payment. You need to apply the exemption manually or use a tool that includes it.
Condo and townhome purchases add another layer. If the property you are buying is part of a condominium association, the monthly HOA fee is a real expense that the lender will factor into your DTI calculation. Lenders typically count 50 percent of the HOA fee against you if the association has adequate reserves, or 100 percent if the reserve study is incomplete. Some calculators ignore this entirely, which means your approved loan amount could be higher than what the lender actually allows once they review the HOA documents.
Pitfalls That Make Calculators Misleading
The biggest problem with free online mortgage calculators is that they present a single number as fact when it is actually an estimate built on a chain of assumptions. Every assumption introduces error. The interest rate may be a display rate rather than the actual rate offered to your profile. The property tax may come from a public database that is 12 to 24 months stale. The homeowners insurance estimate might be based on a generic national average rather than a quote for your specific property and location. PMI assumptions vary by lender and by credit score tier. Each unadjusted assumption adds drift to the final number. I once ran a comparison for a client who was evaluating whether to buy down his rate with points. The calculator he found online showed a monthly savings of $63 per month by paying two points at closing. The math looked solid on the surface. But the calculator did not account for the fact that his property tax reassessment was scheduled for the following year based on the new purchase price. Once the reassessment hit, his escrow payment jumped enough that the net monthly savings shrank to $21. Over five years, that difference added up to roughly $2,500, which is close to the cost of the points themselves. The calculator was not wrong in a mathematical sense. It was just missing context that mattered. Another common failure mode is how calculators handle Adjustable Rate Mortgages. Wisconsin borrowers sometimes consider ARMs, particularly the 5/1 or 7/1 variants. A basic calculator will show you the initial teaser rate and compute a payment based on that. It will not show you what the payment looks like after the first adjustment, which is usually capped at 2 percent per period but can still represent a significant jump. If you only look at the initial payment, you may qualify for a loan you cannot actually afford once the rate resets. Any calculator you use should have an ARM scenario builder that shows payments across multiple adjustment periods.

The down payment assumption is another place where calculators frequently mislead. Many tools default to a 20 percent down payment figure even when you enter a different amount. This happens because the developers assume most users are looking at conventional loans with standard down payment benchmarks. If you are putting down 5 percent with an FHA loan, or 3 percent with a USDA loan, or 0 percent with a VA loan, the calculator may still apply PMI at a rate meant for a conventional loan with less than 20 percent down. The difference between FHA mortgage insurance and conventional PMI is substantial. FHA requires an upfront premium plus a monthly MIP that lasts the life of the loan in most cases. Conventional PMI can be removed once you hit 20 percent equity. A poorly configured calculator will treat them the same way, and your monthly number will be off.
A Practical Tool for Wisconsin Borrowers
If you want a calculator that handles Wisconsin's specific variables without requiring you to manually adjust every field, I recommend using a tool that allows you to input actual county property tax rates and select the homestead exemption option. The downloadable spreadsheet version of a Wisconsin Mortgage Calculator is useful because it lets you build your own scenario with real data from the county assessor's office instead of relying on generic estimates. You can find a version that includes fields for county tax rate, homestead exemption, special assessments, HOA fees, and VA or FHA loan flags at the link below. Download Wisconsin Mortgage Calculator Spreadsheet When you fill it out, use the actual tax bill from the prior year for the property you are evaluating. Cross-reference the amount with the county's official tax rate for that municipality to make sure the numbers align. If the property has not been sold recently and you do not have a prior tax bill, contact the county assessor's office directly. They will provide the current assessed value and the tax rate, which you can multiply to get a reliable annual figure. Enter that into the spreadsheet. Then toggle on the $15,000 homestead exemption if you plan to occupy the home. The spreadsheet will adjust the taxable value automatically and recalculate your monthly tax payment. This simple adjustment alone can change the monthly total by $100 or more in high-tax counties.
When a Calculator Is Not Enough
No calculator replaces a lender's actual approval process. The numbers you see online are estimates based on the inputs you provide. Underwriters will verify your income, assets, employment history, credit score, and the appraised value of the property. They may disapprove a loan that a calculator suggested you qualified for, or they may approve a larger loan than the calculator implied. The calculator is a planning tool, not a commitment. It tells you what the payment might look like. It does not tell you what you will actually be approved for. I have seen borrowers become fixated on a calculator number and then feel blindsided when their actual closing disclosure showed a higher payment. The most common reason is that the calculator assumed a certain credit score tier, and the lender's actual rate lock came out higher due to the borrower's credit profile. Another frequent cause is that the appraisal came in below the purchase price, which changes the loan-to-value ratio and triggers a different PMI requirement or a higher interest rate tier. None of that shows up in a basic calculator. The best approach is to use the calculator as a starting point, not a final answer. Run a few scenarios with different down payment amounts and interest rates to understand the range of possible payments. Then take those numbers to a licensed Wisconsin mortgage professional who can give you a real Loan Estimate based on your actual financial profile. The Loan Estimate is a legally binding document that details your true costs and payment, and it is the only number that matters when you are ready to move forward with an application.